The Offer

Company Overview
Ethos Technologies, Inc. (LIFE) is a technology-driven life insurance platform company with the mission of democratizing access to life insurance by transforming how policies are bought, sold, and underwritten through a fully digital, vertically integrated, three-sided ecosystem serving consumers, agents, and insurance carriers. The Company addresses longstanding inefficiencies in legacy life insurance—slow, complex, and opaque underwriting and distribution—by enabling a 100% digital application and underwriting process with fast risk decisions, transparent pricing, and minimal friction, while providing agents with an end-to-end operating system to improve productivity and accelerate case management and payments. For carriers, the platform expands distribution reach and improves risk selection without Ethos assuming balance sheet risk, resulting in a capital-light, scalable model.
Key Highlights
Primary Offering: 10,526,315 Class A Shares
Use of proceeds:
- Net Proceeds and Offering Economics: Ethos Technologies, Inc. (LIFE) expects to receive net proceeds of approximately USD 82.6 million from the offering, assuming an IPO price of USD 19.00 per share (midpoint of the range), after deducting underwriting discounts, commissions, and estimated offering expenses. Importantly, the Company will not receive any proceeds from the sale of shares by selling stockholders. The stated objectives of the offering include strengthening capitalization and financial flexibility, establishing a public market for the Company’s Class A common stock, and supporting an orderly distribution of shares for selling stockholders.
- Primary Use: RSU Net Settlement Tax Obligations: A significant portion of the net proceeds is expected to be allocated toward USD 41.8 million of anticipated tax withholding and remittance obligations related to the RSU Net Settlement, based on assumptions of a USD 19.00 fair market value per share at settlement and an assumed 39.2% tax withholding rate. The Company highlighted that these obligations are sensitive to pricing and tax-rate changes, with each USD 1.00 change in IPO price impacting the RSU-related tax payment by approximately USD 2.2 million, while each 1.0% change in withholding rate would alter the obligation by approximately USD 1.1 million, absent changes to other assumptions.
- Remaining Proceeds: Corporate Flexibility and Strategic Optionality: The Company intends to use the remaining net proceeds for general corporate purposes, including working capital, operating expenses, and capital expenditures, while retaining broad discretion over allocation. Additionally, LIFE may deploy a portion of proceeds toward acquisitions or strategic investments in complementary businesses, products, services, or technologies, although no material agreements or commitments are currently in place. Pending deployment, unused proceeds are expected to be invested in investment-grade, interest-bearing instruments, such as money market funds, corporate notes and bonds, certificates of deposit, commercial paper, and U.S. government-backed obligations.
Dividend policy:
The Company has never declared or paid cash dividends and currently expects to retain all available funds and any future earnings to support ongoing business development and expansion, with no anticipated dividends in the foreseeable future. Any future dividend decision will remain entirely at the Board’s discretion and will be contingent upon prevailing financial performance, capital needs, contractual and regulatory constraints, and other relevant considerations, including potential restrictions under future agreements.
Ethos Technologies (LIFE): Technology-Led Expansion Opportunity Across the U.S. Life Insurance Value Chain
- Life Insurance Coverage Gap and Structural Demand Tailwinds: Ethos Technologies, Inc. (LIFE) is positioned to address a persistent and structurally large U.S. life insurance underpenetration opportunity, supported by recurring life-stage triggers that continuously generate new demand for coverage. In 2024 alone, the U.S. recorded 3.6 million births, 5.0 million home purchases, 19.3 million college enrollments, 4.1 million individuals turning 65, and 12.5 million people experiencing bereavement, each representing major life events that typically elevate insurance need. Despite this consistent demand creation, the industry continues to reflect a material coverage gap, with 42% of American adults in 2024 acknowledging a need for coverage but remaining uninsured due to perceived cost and product complexity, highlighting a large, unmet need that remains structurally addressable through simplification and digitisation.
- Large Addressable Market with Scalable Product Expansion Pathway: Ethos seeks to close this gap through streamlined digital underwriting and product accessibility, including the ability to instantly underwrite 95% of applicants based on internal data, substantially improving speed, transparency, and approval rates. The Company operates across major life insurance product categories—Term, Whole Life, and Indexed Universal Life—which collectively represented approximately USD 12.6 billion of annual new policy premiums in 2024, supported by persistent demand through economic cycles and an estimated ~10 million new policies purchased annually over the past decade. Importantly, as the platform expands into adjacent and incremental categories such as Variable Universal Life and Fixed Indexed Annuities, management estimates the market opportunity could expand materially to over USD 140 billion of new premiums annually, implying a long runway for monetisation and multi-product scaling.
- Industry Disruption Drivers: Carrier Legacy Constraints and Distribution Shift: The structural limitations of legacy carriers reinforce the opportunity for modern platform-led entrants, as most large insurers operate with outdated, siloed infrastructure and manual underwriting systems that inhibit speed, consistency, and scalable distribution. Modernisation remains difficult given that many leading carriers are 100+ years old, and system migration complexity often results in continued dependence on third-party legacy platforms with fragmented data architectures. Concurrently, the industry distribution model is shifting away from captive channels toward independent intermediated distribution, with independent agents accounting for 53% of premiums in 2023, up materially over the prior decade. This broker-led paradigm requires carriers to compete through agent enablement, improved underwriting efficiency, and product competitiveness—conditions which structurally favour a platform that can integrate carriers, agents, and consumers within a unified ecosystem.
- Platform Differentiation and Competitive Moat Supporting Long-Term Growth: Ethos’ competitive positioning is anchored in a fully digital, extensible platform capable of rapid product iteration, real-time pricing adjustments, and integrated underwriting and administration, enabling superior efficiency versus traditional insurers and fragmented insurtech offerings. The model is further strengthened by a multi-carrier approach that supports broad risk coverage and flexible product routing, enhancing consumer-policy matching and improving agent value proposition. With 500,000+ cumulative policies activated, Ethos has developed a meaningful data moat that enhances underwriting accuracy, pricing precision, and marketing conversion through closed-loop learning—particularly valuable in life underwriting where rare-condition incidence can be below 0.01%. Early-mover positioning and deep carrier relationships further reinforce barriers to entry, supported by large historical investments in platform development and distribution capabilities, which collectively underpin a credible pathway to sustained scale, improved unit economics, and durable network effects across the life insurance ecosystem.
Financial Highlights (Results of Operations) (Expressed in USD) (9MFY25, ended September 30)
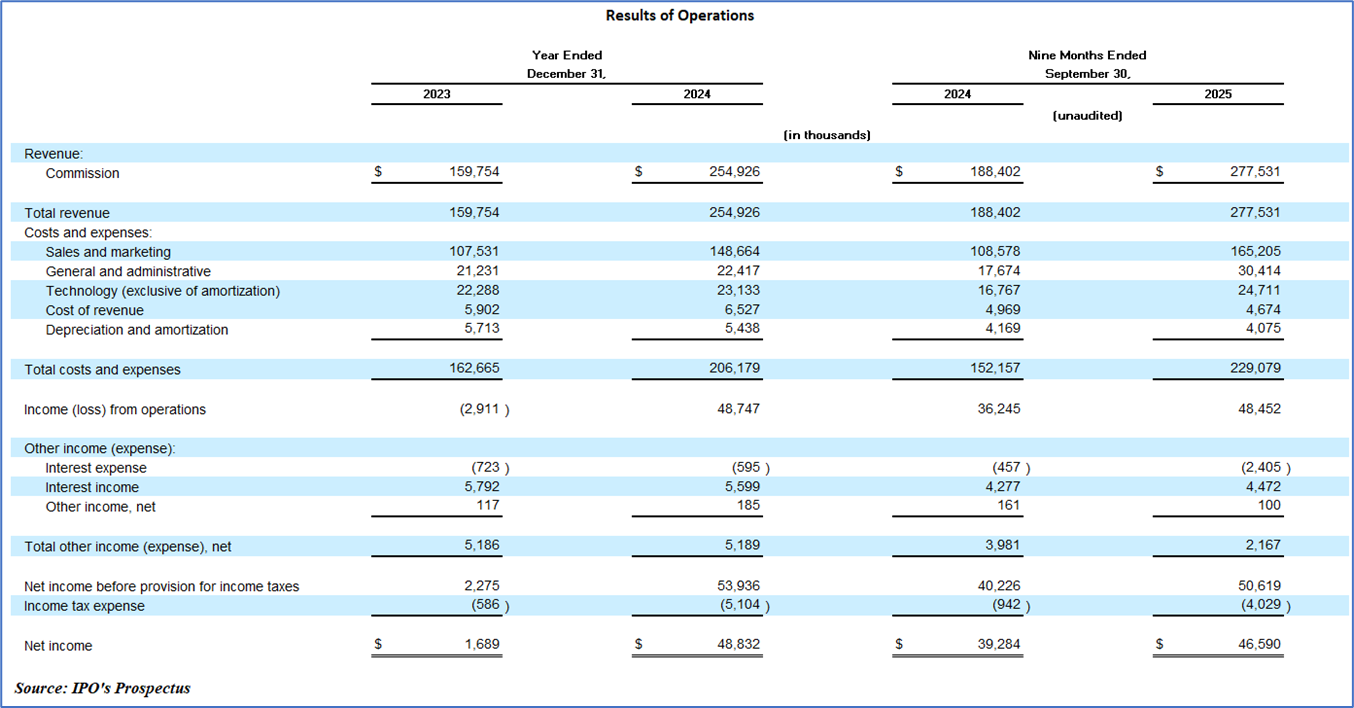
- Revenue Expansion and Channel Mix Shift: Ethos Technologies, Inc. (LIFE) delivered strong top-line expansion in the nine months ended September 30, 2025, with total revenue rising 47% YoY to USD 277.5 million from USD 188.4 million. Growth was underpinned by a 61% increase in activated policies, reflecting effective scaling across both distribution engines. Notably, the revenue mix continued to diversify, with DTC revenue increasing 24% YoY to USD 168.3 million, while third-party channel revenue more than doubled (+106%) to USD 109.2 million, largely driven by accelerated growth in Whole Life Insurance products sold primarily through third-party agents, which also contributed to a 9% decline in ARPU due to lower average coverage sizes.
- Sales and Marketing Investments to Drive Scale: Sales and marketing spend expanded materially to support growth, increasing 52% YoY to USD 165.2 million, representing 60% of revenue (vs. 58% in the prior period). The increase was predominantly attributable to a sharp rise in agent payments and advertising, reflecting higher policy volumes and active investment in both performance acquisition and brand-building. Specifically, agent payments increased 69% to USD 63.1 million, while advertising spend rose 43% to USD 69.5 million, indicating meaningful reinvestment into the growth engine. Additional pressure came from higher underwriting costs related to non-activated policies (linked to higher application volumes) and incremental personnel costs associated with headcount expansion to support operational scale.
- Operating Cost Base Expansion with Disciplined Gross Cost Structure: General and administrative expenses rose 72% YoY to USD 30.4 million (11% of revenue), driven by higher stock-based compensation linked to the 2025 Tender Offer, increased headcount, and elevated professional services costs. Technology expenses (excluding amortisation) increased 47% YoY to USD 24.7 million, remaining stable at 9% of revenue, reflecting continued investment in platform expansion, hosting, and software infrastructure while preserving relative cost discipline as scale improves. In contrast, cost of revenue declined 6% to USD 4.7 million, improving to 2% of revenue, mainly due to reduced evidence provider costs, while depreciation and amortisation remained broadly stable, highlighting a cost structure that continues to preserve high gross profitability despite growth-driven operating expense increases.
- Other Income/Expense Movements and Profitability Quality Indicators: Below-the-line items showed notable volatility, with interest expense increasing materially to USD 2.4 million due to liabilities associated with the sale of commissions receivable (partially offset by reductions in prior liabilities), while interest income increased modestly by 5% to USD 4.5 million on higher average cash and investment balances. Income tax expense increased sharply to USD 4.0 million, largely driven by valuation allowance adjustments tied to temporary differences. Overall, the financial profile remains characterised by high-margin economics and scaling efficiency, supported by strong unit-level performance metrics including gross margin of 98%, contribution margin of 41%, and Adjusted EBITDA of USD 63.2 million (23% margin) for 9M 2025, reflecting continued monetisation strength and operating leverage despite elevated growth investments.
Key Management Highlights
Risk Associated (High)
Investment in the IPO of “LIFE” is exposed to a variety of risks such as:
- Regulatory and Compliance Risk: Ethos Technologies, Inc. (LIFE) operates in a tightly regulated insurance environment, and any compliance lapses in underwriting governance, marketing, data usage, or policy servicing could lead to regulatory action, financial penalties, and reputational damage.
- Persistency and Revenue Model Sensitivity: Because LIFE recognizes expected lifetime commissions upfront, its reported revenue and profitability are highly sensitive to persistency assumptions; weaker retention, higher lapses, or an unfavorable product/channel mix shift could compress ARPU and trigger negative revenue adjustments.
- Carrier and Third-Party Distribution Dependence: The platform’s growth depends on maintaining strong carrier partnerships and scaling its agent-led channel, exposing LIFE to risks from carrier pricing/commission changes, underwriting tightening, and agent quality or chargeback issues that may pressure conversion and margins.
Conclusion
Ethos Technologies, Inc. (LIFE) is a technology-led life insurance platform aiming to simplify distribution and underwriting via a vertically integrated ecosystem connecting consumers, agents, and carriers, while remaining capital-light as carriers retain insurance risk. The IPO includes 10.53 million Class A shares, with estimated net proceeds of ~USD 82.6 million (at USD 19.00/share midpoint), of which ~USD 41.8 million is expected to fund RSU-related tax obligations, with the remainder allocated toward general corporate purposes; no dividends are expected in the near term. The Company targets the U.S. life insurance undercoverage gap (notably 42% unmet need), supported by technology-enabled underwriting (instant decisions for ~95% of applicants) and product expansion potential beyond core categories. Financially, LIFE delivered strong scale in 9M 2025, with revenue increasing 47% YoY to USD 277.5 million on a 61% rise in activated policies, driven by rapid third-party channel growth (+106%), while maintaining high profitability metrics (gross margin 98%, adjusted EBITDA margin 23%) despite elevated growth investments; key risks include regulatory exposure, persistency-driven revenue sensitivity, and dependence on carrier and agent partners.
Hence, given the financial performance of the company, use of proceeds, and associated risks “Ethos Technologies Inc. (LIFE)” IPO seems “Attractive" at the IPO price.
Past performance is not a reliable indicator of future performance.

 NZ
 UK
 US
 AU
 IND

 CA
 Please wait processing your request...