Advanced Micro Devices, Inc
Advanced Micro Devices, Inc (NASDAQ: AMD) is a global semiconductor company specializing in high-performance computing, graphics, and visualization technologies. The company operates across three primary segments: Data Center, Client & Gaming, and Embedded. Its Data Center portfolio includes AI accelerators, server CPUs, GPUs, DPUs, FPGAs, SmartNICs, and adaptive SoCs. The Client & Gaming segment offers desktop and notebook processors, discrete GPUs, chipsets, and semi-custom SoCs, while the Embedded segment provides embedded processors and adaptive computing solutions. AMD markets its products under well-known brands such as EPYC, Ryzen, Ryzen PRO, and Virtex UltraScale+.

Recent Developments
AMD Secures Landmark 6-Gigawatt AI Infrastructure Deal with Meta, Strengthening Its Position in the Global AI Race
- AMD and Meta Forge 6-Gigawatt AI Infrastructure Partnership: AMD and Meta Platforms have announced a multi-year, 6-gigawatt agreement to power Meta’s next-generation AI infrastructure using multiple generations of AMD Instinct GPUs. The partnership will begin with a custom MI450-based Instinct GPU deployment in the second half of 2026, alongside 6th Gen AMD EPYC CPUs, codenamed “Venice,” and powered by AMD’s ROCm software stack. The infrastructure will be built on the jointly developed Helios rack-scale architecture under the Open Compute Project, enabling scalable, high-performance AI systems optimized for Meta’s workloads. This collaboration significantly deepens the companies’ existing relationship, positioning AMD at the center of one of the industry’s largest AI infrastructure expansions.
- Strategic Diversification and Long-Term Roadmap Alignment: As Meta seeks to diversify beyond Nvidia, the agreement strengthens AMD’s role as a strategic AI compute partner. Meta will serve as a lead customer for next-generation EPYC processors, including “Venice” and the workload-optimized “Verano,” reinforcing CPUs as a critical pillar of AI orchestration alongside GPUs. The companies have aligned their silicon, systems, and software roadmaps to deliver energy-efficient, performance-optimized AI platforms at gigawatt scale. Meta has already deployed millions of EPYC CPUs and substantial volumes of Instinct MI300 and MI350 GPUs, underscoring the depth of the collaboration.
- Financial Impact: To align long-term incentives, AMD has issued Meta a performance-based warrant for up to 160 million AMD shares, vesting in tranches as GPU shipment and technical milestones are achieved. The structure ties vesting to both deployment scale and stock price thresholds, reinforcing execution accountability. AMD expects the partnership to drive substantial multi-year revenue growth and be accretive to non-GAAP earnings per share.
Financial and Operational Performance Review for the year ended December 2025 (FY2025)
- Record Revenue Expansion and Earnings Growth: Advanced Micro Devices, Inc. delivered a defining performance in fiscal year 2025, achieving record revenue of USD 34.6 billion, representing a 34% year-over-year increase. The strong topline growth was broad-based, driven primarily by robust demand across the Data Center and Client & Gaming segments.
In the fourth quarter of FY2025, revenue reached a record USD 10.3 billion, up 34% year-over-year, supported by accelerating demand for EPYC server processors, Instinct GPUs, and Ryzen processors. Net income and earnings per share also demonstrated meaningful improvement, reflecting strong operating leverage and favorable product mix.
- Margin Expansion and Operating Profitability: Profitability metrics strengthened materially during the year. For Q4 FY2025, non-GAAP gross margin expanded to 57%, compared to 54% in Q4 FY2024, driven primarily by favorable product mix and strong data center performance.
On a full-year basis, non-GAAP operating income increased to USD 7.8 billion in FY2025, up 27% year-over-year. Operating margin improvement reflected higher revenue scale, improved product mix, and disciplined execution, partially offset by increased research and development investments to support AI roadmap expansion.
Segment Performance Analysis
- Data Center: AI-Led Growth and Market Share Gains: The Data Center segment emerged as the primary growth engine. Q4 FY2025 data center revenue reached USD 5.4 billion, increasing 39% year-over-year. The growth was driven by accelerating adoption of fifth-generation EPYC processors and the continued ramp of Instinct MI350 series GPUs.
For the full year, Data Center revenue totaled USD 16.6 billion, reflecting a 32% year-over-year increase. Operationally, the company expanded hyperscaler deployments, launched over 500 new AMD-based cloud instances during 2025, and significantly broadened enterprise EPYC adoption. The rapid scaling of the Instinct AI portfolio and ROCm software ecosystem further strengthened AMD’s competitive positioning in high-performance and AI computing markets.
- Client & Gaming: Strong Consumer and Commercial Momentum: The Client & Gaming segment delivered substantial growth during FY2025. Q4 revenue increased 37% year-over-year to USD 3.9 billion, driven primarily by record Ryzen processor sales and strong Radeon GPU demand.
For the full year, segment revenue reached USD 14.6 billion, marking a 51% year-over-year increase. Desktop CPU sales achieved record levels for multiple consecutive quarters, while commercial PC adoption accelerated with more than 40% year-over-year growth in commercial Ryzen sell-through during Q4. Operationally, AMD expanded its AI PC portfolio with Ryzen AI 400 series processors and strengthened its gaming ecosystem through new GPU launches and AI-powered upscaling technologies.
- Embedded Segment: Stabilization and Design Win Momentum: The Embedded segment recorded Q4 FY2025 revenue of USD 950 million, up 3% year-over-year, reflecting improving end-market demand, particularly in test, measurement, and aerospace applications.
Although full-year embedded revenue declined 3% year-over-year to USD 3.45 billion, the company reported record design wins totaling USD 17 billion in FY2025. Operationally, AMD strengthened its adaptive and embedded portfolio with new EPYC Embedded, Versal, and Ryzen AI embedded solutions, positioning the segment for renewed growth in industrial, automotive, and edge AI applications.
Financial Strength and Cash Generation
- Cash Flow Generation and Balance Sheet Strength: AMD demonstrated strong cash generation and balance sheet resilience in FY2025. During Q4 FY2025, the company generated USD 2.3 billion in operating cash flow and USD 2.1 billion in free cash flow. At year-end, cash, cash equivalents, and short-term investments totaled approximately USD 10.6 billion, while total debt remained stable at approximately USD 3.2 billion. Additionally, AMD repurchased USD 1.3 billion of shares during FY2025, reinforcing its capital allocation discipline and commitment to shareholder returns.
- Strategic Outlook and Long-Term Growth Trajectory: Management highlighted a strong outlook for fiscal 2026, with Q1 revenue guidance of approximately USD 9.8 billion and continued momentum expected in the Data Center and AI businesses. Looking ahead, AMD expects to grow Data Center revenue at greater than 60% annually over the next three to five years, scale its AI business to tens of billions in annual revenue by 2027, and deliver sustained operating leverage through disciplined investment and execution. The company’s expanding AI accelerator roadmap, rack-scale Helios platform, and next-generation MI450/MI500 series products position it favorably within the multiyear AI and high-performance computing demand cycle.
Key Risks:
- Customer Concentration & Execution Risk: The large-scale Meta deployment increases reliance on a single hyperscale customer, exposing AMD to potential order timing shifts, milestone delays, or contract renegotiations.
- Competitive Pressure from Nvidia and Custom Silicon: Intensifying competition in AI accelerators and Meta’s continued development of in-house AI chips could limit AMD’s long-term share gains or pricing power.
- Manufacturing & Supply Chain Constraints: Dependence on third-party foundries and advanced packaging capacity (e.g., TSMC) may create production bottlenecks that impact timely GPU ramp-up.
- Warrant Dilution & Performance Milestones: The performance-based warrant for up to 160 million shares may create dilution risk and is contingent on shipment and stock price targets, adding financial and execution complexity.
Technical Observation (on the daily chart):
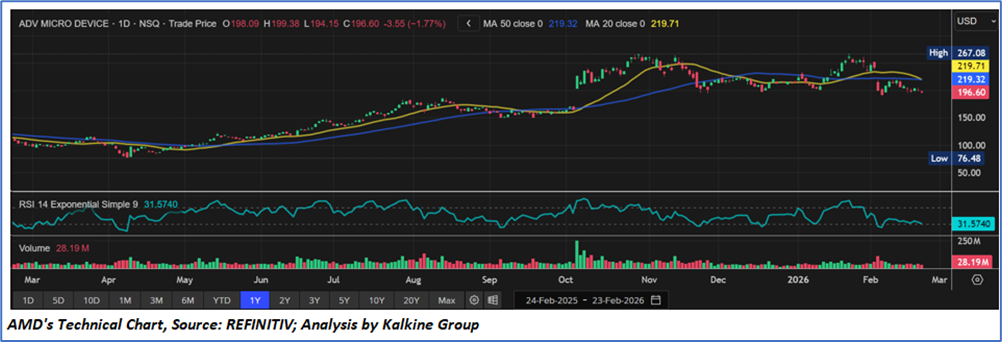
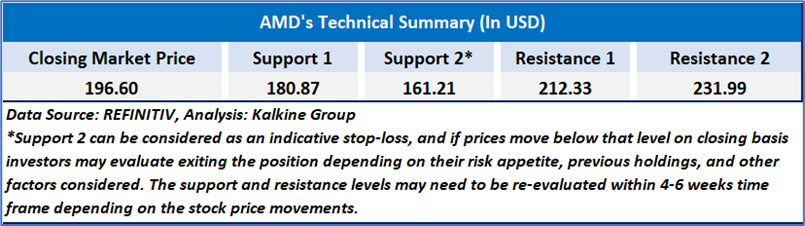
AMD’s stock is currently in a short-term corrective phase after peaking near recent highs, with price trading below its 20-day and 50-day moving averages, indicating near-term weakness. The RSI is hovering close to oversold levels, suggesting momentum has softened and a potential technical bounce may emerge. Immediate support is seen around the 190 zone, while resistance lies near the 215–220 range.
AMD delivered a record-breaking performance in FY2025, achieving 34% revenue growth to USD 34.6 billion, driven by strong demand across Data Center and Client & Gaming segments. The company expanded margins, generated robust free cash flow, and strengthened its balance sheet while accelerating adoption of EPYC CPUs and Instinct AI GPUs. With expanding hyperscaler partnerships, growing AI deployments, and sustained market share gains, AMD enters FY2026 with strong operational momentum and a clear pathway for continued top-line expansion and profitability growth.
Based on above-guidance production during Q4FY25, disciplined cost management, portfolio optimization, and strengthened balance sheet, a ‘Buy’ rating has been given Advanced Micro Devices, Inc (NASDAQ: AMD) at the closing market price of USD 196.60 as of Feb 23,2026.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is February 23,2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...