Hormel Foods Corporation
Hormel Foods Corporation (NYSE: HRL) is a global-branded food company. The Company develops, processes, and distributes a range of food products in a variety of markets. Its segments include Retail, Foodservice, and International. The Retail segment is primarily engaged in the processing, marketing, and sale of food products sold predominantly in the retail market. This segment also includes the Company’s MegaMex Foods, LLC joint venture.
Key Business and Financial Updates:
- Solid First Quarter Performance Supported by Portfolio Strength: Hormel Foods Corporation (NYSE: HRL) reported a constructive start to fiscal 2026, delivering first-quarter net sales of USD 3.03 billion alongside 2% organic net sales growth, marking the company’s fifth consecutive quarter of organic top-line expansion. Reported diluted earnings per share were USD 0.33, while adjusted diluted EPS reached USD 0.34. Operating income totaled USD 244 million, with adjusted operating income of USD 247 million, reflecting disciplined execution and resilient demand across the company’s diversified branded protein portfolio .
- Segment Performance Driven by Foodservice and International Momentum: Hormel’s quarterly performance was led by strong results in its Foodservice and International divisions. Foodservice net sales increased 7%, with segment profit rising 13%, supported by pricing actions, customized solutions, premium prepared proteins, and branded pepperoni offerings. International net sales advanced 8%, while segment profit increased 10%, driven by multinational operations, stronger China demand, and export growth led by SPAM® luncheon meat. In contrast, the Retail segment faced pressure, with net sales declining 2% and segment profit down 19%, reflecting strategic exits from non-core private-label categories, softer deli demand, and elevated input and logistics costs .
- Portfolio Optimization Enhancing Strategic Focus: Management continues to actively reshape the company’s portfolio toward higher-growth, value-added protein categories. During the quarter, Hormel finalized the sale of a majority interest in the Justin’s® branded business, generating a gain of USD 23.5 million. In addition, the company announced a definitive agreement to divest its whole-bird turkey business, expected to close by the end of the second quarter of fiscal 2026. These transactions are intended to reduce exposure to more volatile commodity-driven categories while reallocating resources toward branded, margin-accretive growth opportunities .
- Strong Cash Generation and Conservative Balance Sheet Position: Hormel maintained a robust financial profile during the quarter, generating USD 349 million in operating cash flow. Capital expenditures were USD 69 million, primarily directed toward the ambient meat snack facility in Jiaxing, China, and data and technology investments. The company returned approximately USD 160 million to shareholders through dividends during the quarter. Balance sheet strength remained notable, with cash on hand increasing to USD 868 million, up USD 197 million from the end of fiscal 2025, while inventories declined to USD 1.6 billion, reflecting improved working capital efficiency .
- Guidance Reaffirmed with Positive Earnings Outlook: For fiscal 2026, Hormel reaffirmed its net sales guidance range of USD 12.2 billion to USD 12.5 billion, with expected organic net sales growth of 1% to 4%. The company also reiterated adjusted diluted EPS guidance of USD 1.43 to USD 1.51, representing projected growth of 4% to 10%, while updating reported diluted EPS guidance to USD 1.37 to USD 1.46. Management’s maintained outlook reflects confidence in continued momentum from Foodservice, International growth, disciplined pricing execution, and the benefits of portfolio simplification initiatives.
Key Risks for Hormel Foods Corporation (NYSE: HRL):
- Retail Segment Margin Pressure and Volume Weakness: Hormel’s Retail segment continues to face pressure from declining volumes, softer packaged deli demand, elevated raw material costs, and higher logistics expenses. If consumer demand remains subdued or pricing actions fail to offset cost inflation, profitability within one of the company’s core segments could remain constrained.
- Commodity Input Cost and Supply Chain Volatility: As a global food producer, Hormel is exposed to fluctuations in key commodity inputs such as turkey, pork, beef, packaging materials, and transportation costs. Sudden increases in agricultural or freight costs, disease-related supply disruptions, or operational bottlenecks could pressure margins and create earnings volatility.
- Execution Risk in Portfolio Reshaping Strategy: Hormel is actively divesting lower-growth businesses and reallocating capital toward higher-margin branded protein categories. While strategically constructive, delays in transaction closings, weaker-than-expected redeployment returns, or disruption to existing revenue streams could reduce the anticipated benefits of this portfolio transformation.
Technical Observation (on the daily chart):
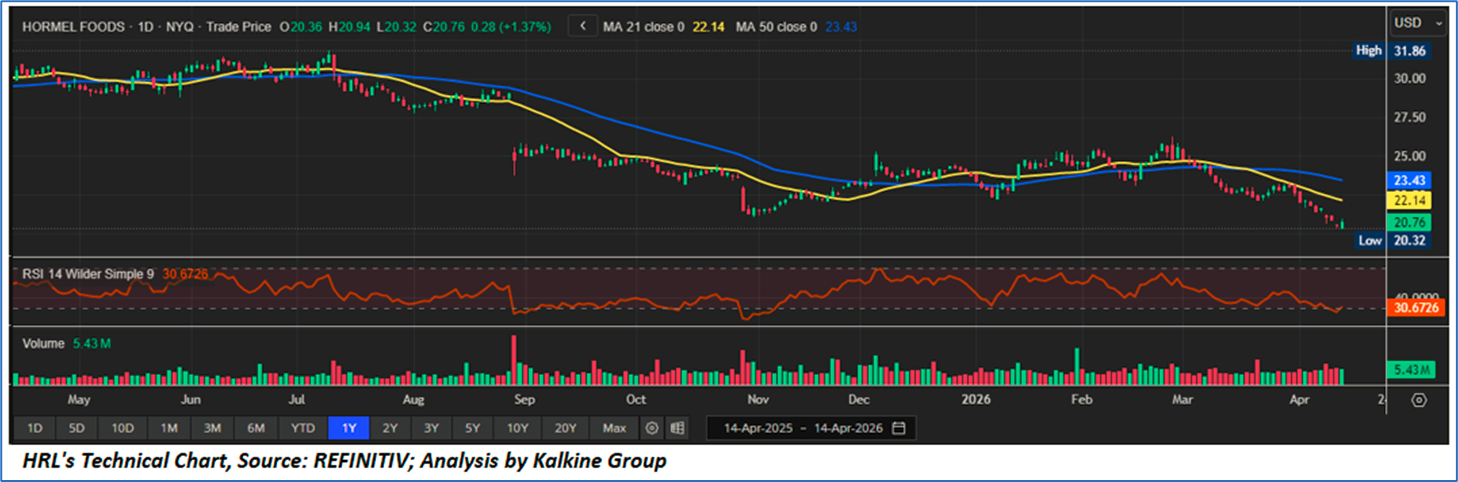
- Prevailing Downtrend Remains Intact with Weak Price Structure: Hormel Foods Corporation (NYSE: HRL) continues to trade within a well-defined medium-term downtrend, with the share price currently at USD 20.76, positioned below both the 21-day moving average of USD 22.14 and the 50-day moving average of USD 23.43. This negative moving-average alignment indicates persistent selling pressure and a lack of sustained bullish conviction. Over the broader one-year period, the stock has recorded a sequence of lower highs and lower lows, confirming continued technical weakness. The recent decline toward the lower end of the annual trading range further suggests that market participants remain cautious on near-term upside prospects.
- Momentum Indicators Reflect Oversold Conditions but Limited Reversal Confirmation: The 14-day Relative Strength Index is near 67, placing the stock close to oversold territory. While such readings can sometimes precede short-term technical rebounds, the absence of a decisive upward momentum reversal indicates that downside pressure has not yet fully exhausted itself. RSI remaining below the neutral 50 threshold reinforces the view that bearish momentum remains dominant. Volume activity appears elevated during recent declines, which may indicate distribution rather than accumulation, though stabilization near current levels could attract value-oriented buyers if broader sentiment improves.
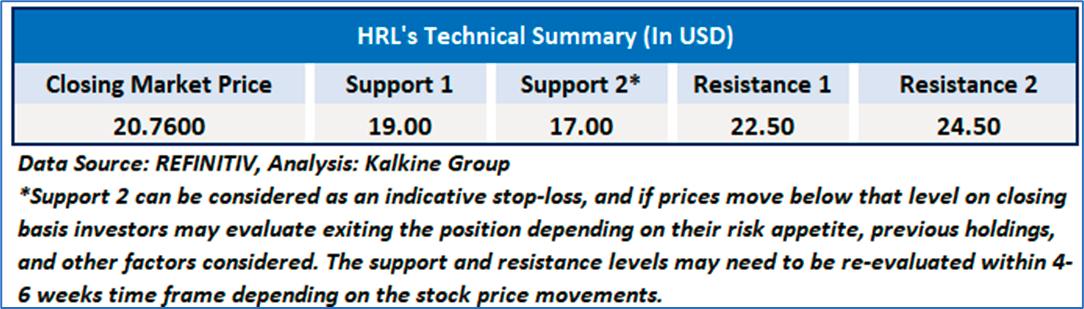
- Support, Resistance and Tactical Outlook: Immediate support is visible near the recent low zone of USD 20.32, which now represents a critical near-term technical floor. A sustained break below this level could expose additional downside toward the psychological USD 20.00 region, followed by deeper support zones if weakness persists. On the upside, initial resistance is located near the 21-day moving average at USD 22.14, with more significant resistance near the 50-day moving average at USD 23.43. A recovery above these levels would be required to improve sentiment and suggest a broader trend stabilization. Until then, HRL appears technically defensive, with any rallies likely to be viewed as recovery attempts within a prevailing downtrend.
Hormel Foods Corporation (NYSE: HRL) continues to exhibit a fundamentally stable profile supported by resilient first-quarter fiscal 2026 performance, with net sales of USD 3.03 billion, continued organic revenue growth, strong cash generation, and reaffirmed full-year guidance reflecting confidence in Foodservice and International momentum, portfolio optimization initiatives, and disciplined capital allocation . The company’s conservative balance sheet, ongoing shareholder returns, and strategic shift toward higher-margin branded protein categories reinforce its long-term defensive characteristics. However, margin pressure within the Retail segment, exposure to commodity cost volatility, and execution risks tied to portfolio restructuring remain relevant considerations. From a technical standpoint, the shares remain in a medium-term downtrend, trading below key moving averages with momentum indicators near oversold levels, suggesting cautious market sentiment despite the potential for short-term stabilization near support zones.
As per the above-mentioned price action, important support near USD 19.00- USD 20.00, momentum in the stock over the last month, and technical indicators analysis, a ‘WATCH’ rating has been given for Seabridge Gold Inc. (NYSE: SA), at the closing price of USD 20.76, as of April 14, 2026.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective, and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is April 14, 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...