Spruce Biosciences Inc
Spruce Biosciences, Inc. (NASDAQ: SPRB) is a biopharmaceutical company focused on developing and commercializing therapies for neurological disorders with significant unmet medical need. It has a diverse portfolio of product candidates addressing diseases with high unmet medical need and clear biology for treatment, for which there are either no approved therapies treating the underlying disease or suboptimal treatment options. Its pipeline consists of TA-ERT, Tildacerfont and Cortibon, and SPR202. TA-ERT is a fusion protein comprised of recombinant human alpha-N-acetylglucosaminidase.

Key Business and Financial Updates:
- BLA Submission on Track as FDA Interactions Turn Constructive: Spruce Biosciences is approaching its most consequential regulatory milestone yet, with a Biologics License Application submission for tralesinidase alfa enzyme replacement therapy (TA-ERT) targeted for the fourth quarter of 2026. The path cleared meaningfully in February 2026 following two productive Type B meetings with the FDA, during which regulators confirmed that integrated clinical study data combined with natural history data could potentially serve as an adequate and well-controlled study for review purposes. Critically, the FDA's acceptance of cerebrospinal fluid heparan sulfate non-reducing end as a reasonably likely surrogate endpoint unlocks the accelerated approval pathway — a regulatory route that historically reduces the time from submission to decision by 12 to 18 months relative to standard review timelines. With the BLA submission anticipated in Q4 2026 and an accelerated approval pathway now formally in scope, the regulatory risk profile for TA-ERT has shifted materially in the company's favour at a stage when most small-cap biopharmaceuticals are still navigating fundamental clinical uncertainty.
- Clinical Data Builds the Case for a Potential First-Ever MPS IIIB Treatment: Long-term data presented at the 22nd Annual WORLDSymposium in February 2026 added substantive clinical weight to TA-ERT's profile across two separate analyses. The first demonstrated that sustained TA-ERT administration produced rapid and durable reductions in heparan sulfate levels — the primary disease biomarker in MPS IIIB — while preserving both cognitive and non-cognitive clinical outcomes relative to natural history patients who received no treatment. The second analysis presented a directly controlled sibling comparison, showing that the treated patient displayed measurably superior cognitive, language, and motor functioning at a comparable age to the untreated sibling, providing rare within-family evidence of treatment effect. MPS IIIB affects an estimated 1 in 200,000 to 1 in 500,000 live births globally, placing it firmly in the ultra-rare disease category where single-arm studies and surrogate endpoint data are routinely accepted as a basis for regulatory approval. With no currently approved therapy for MPS IIIB anywhere in the world, TA-ERT would enter the market as an entirely uncontested first-in-class treatment for a patient population with no existing standard of care.
- Capital Position Engineered to Outlast the BLA Filing: Spruce's balance sheet at year-end 2025 carried USD 48.9 million in cash and cash equivalents, a figure that deliberately excludes the USD 15.0 million initial tranche received in January 2026 under the newly secured Avenue Capital growth facility. That facility provides access to up to USD 50 million in total, structured across four tranches — an initial USD 15 million already drawn and three additional tranches totalling USD 35 million available subject to conditions — over a 42-month term. Incorporating the January 2026 proceeds, the company's effective liquidity position at the start of 2026 stood at approximately USD 63.9 million. Management has guided that this combined capital base funds operations into early 2027, a runway that clears the anticipated Q4 2026 BLA submission by a meaningful margin. For context, the company's total cash burn in 2025 was approximately USD 39 million at the net loss level, suggesting the current capital structure provides roughly 18 to 20 months of operational coverage from the start of 2026 without requiring immediate equity dilution.
- Operating Expenses Fall 40% as the Company Pivots Its Entire Focus to TA-ERT: The financial transformation at Spruce between 2024 and 2025 is striking in its scale and reflects a deliberate strategic narrowing rather than simple cost cutting. Total operating expenses declined from USD 61.1 million in 2024 to USD 36.5 million in 2025, a reduction of approximately 40% in a single year. The primary driver was the cessation of all development activities related to tildacerfont for congenital adrenal hyperplasia, which had been the company's prior lead programme. Research and development expenses alone fell from USD 46.4 million to USD 19.5 million year over year, a decline of USD 26.9 million or roughly 58%, as the CAH programme costs rolled off. General and administrative expenses moved in the opposite direction, rising modestly from USD 14.6 million to USD 17.0 million, reflecting increased professional service fees associated with regulatory preparation and commercial infrastructure build. Non-cash stock-based compensation, embedded within total operating expenses, also declined from USD 5.3 million to USD 2.6 million, meaning the reduction in cash operating costs was even more pronounced than the headline figures suggest. The net loss narrowed from USD 53.0 million in 2024 to USD 39.0 million in 2025, a USD 14 million improvement that reflects the full financial benefit of the strategic pivot to a single high-conviction programme.
- Commercial Infrastructure and a Rare Voucher Create Asymmetric Upside: Spruce is constructing its commercial organisation with a level of deliberateness that signals genuine launch confidence rather than speculative positioning. The appointment of Dale Hooks as Chief Commercial Officer brings over three decades of rare disease commercialisation experience to a leadership team that now also includes two new senior hires in regulatory affairs and clinical development operations, all made within the first two months of 2026. In rare disease markets, where the commercial model depends on identifying a patient population that may number in the hundreds across entire national healthcare systems, the quality and timing of commercial capability building is often as determinative of launch success as the clinical data itself. Layered on top of the commercial build is a significant financial optionality event in the form of the Rare Pediatric Disease Priority Review Voucher, for which TA-ERT holds eligibility upon FDA approval. The PRV programme was reauthorised in February 2026 through September 2029, restoring certainty around this incentive. Priority Review Vouchers have historically transacted in the range of USD 100 million to USD 150 million in the secondary market, representing a potential non-dilutive capital inflow at the moment of approval that could fund a substantial portion of the commercial launch without requiring equity issuance.
Key Company specific risks for SPRB:
- Regulatory Approval Risk: FDA Acceptance Is Not Guaranteed Despite Positive Signals: Despite constructive Type B meeting outcomes, the FDA's use of the phrase "could potentially" regarding TA-ERT's surrogate endpoint data leaves meaningful regulatory uncertainty intact, and a complete response letter or request for additional studies remains a real possibility. An extended or unsuccessful review would delay commercialisation materially, pressure the stock, and accelerate cash consumption against a runway that does not extend significantly beyond the Q4 2026 BLA submission itself.
- Financing and Cash Runway Risk: Capital Is Sufficient but Not Abundant: With an effective liquidity position of approximately USD 63.9 million at the start of 2026, a 2025 net loss of USD 39.0 million, and operating costs expected to rise through the year, the company's cash buffer is functional but narrow, and the remaining USD 35 million under the Avenue Capital facility is conditional rather than guaranteed. Any regulatory delay pushing the approval timeline beyond early 2027 would likely force an equity raise or additional debt financing before product revenues materialise, introducing meaningful dilution risk for existing shareholders.
- Commercial Execution Risk: Launching in an Ultra-Rare Disease Market Is Operationally Complex: MPS IIIB affects as few as 1 in 500,000 live births, meaning the entire addressable U.S. patient population numbers in the hundreds, and successfully reaching those patients requires deeply specialised physician engagement, reimbursement negotiation, and access infrastructure that Spruce is still in the early stages of building. Even with a strong clinical profile, any shortfall in patient identification, payer coverage, or international market access could produce launch revenues that fall well short of investor expectations.
Technical Observation (on the daily chart):
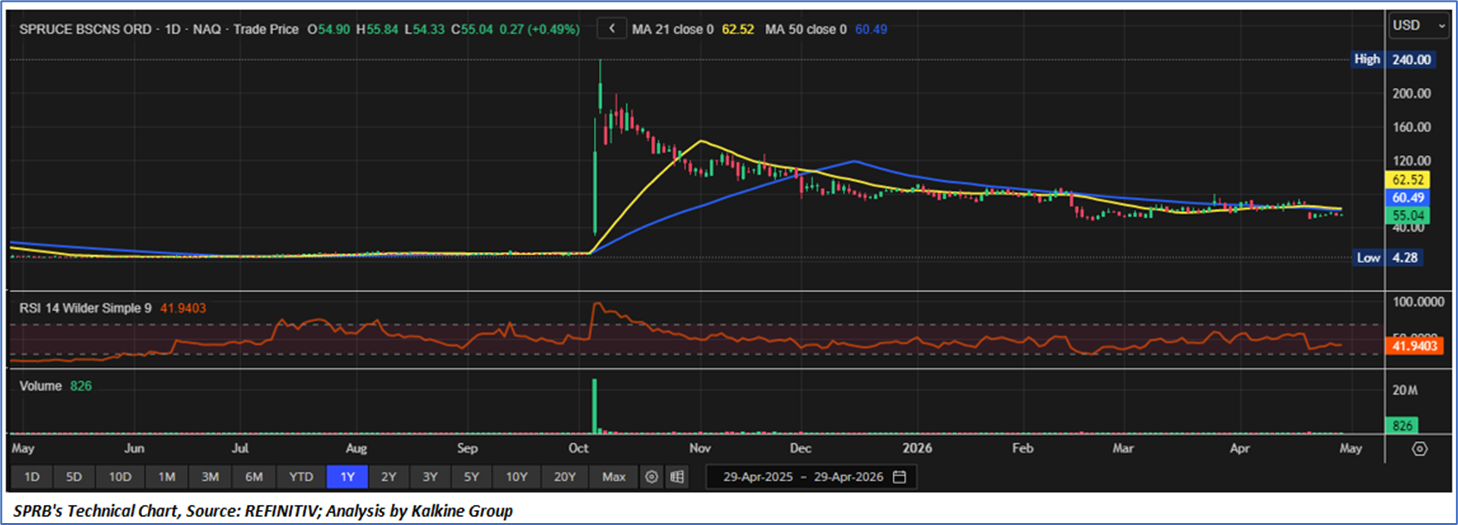
- Primary Trend Structure and Post-Spike Consolidation: SPRB remains in a volatile consolidation phase following its extraordinary parabolic rally in October, when the stock surged toward the USD 240.00 high before entering an extended corrective structure. Price is currently trading at USD 55.04, below both the 21-day moving average at USD 62.52 and the 50-day moving average at USD 60.49, indicating that short-to-medium term trend control remains mildly bearish. However, despite the prolonged retracement, the stock continues to hold materially above its historical low of USD 4.28, suggesting that a portion of the prior re-rating has been retained. Recent sideways action may indicate base formation after months of post-spike digestion.
- Momentum, Participation and Internal Conditions: The 14-day RSI at 41.94 reflects subdued momentum and places the stock slightly below neutral territory, implying limited buying conviction but not deeply oversold conditions. This setup often corresponds with consolidation rather than capitulation. Trading volume has contracted sharply to just 826 shares on the displayed session, signaling low liquidity and reduced participation, which can amplify price swings and widen spreads. In thinly traded biotech names, muted volume can also delay technical confirmations, meaning momentum indicators should be interpreted cautiously until stronger participation returns.
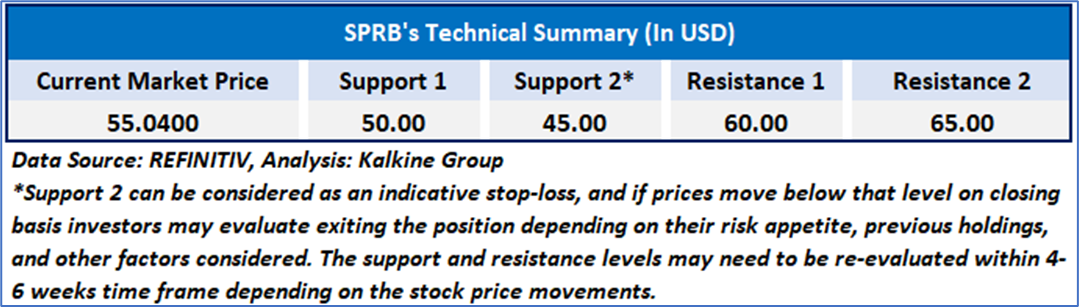
- Key Levels, Tactical Setup and Forward Bias: Immediate resistance is visible near the USD 60.50–62.50 zone, where both moving averages converge and may act as overhead supply. A sustained move above this cluster would improve the technical outlook and could reopen upside toward USD 75–80 On the downside, first support lies near USD 50.00, followed by stronger structural support around USD 40.00. A break below those levels could invite further weakness. Overall, the near-term bias remains neutral-to-cautious, with the stock requiring a decisive reclaim of moving averages and higher volume participation before a stronger bullish reversal case can be established.
Spruce Biosciences is transitioning into a pivotal stage as it advances TA-ERT toward a targeted Q4 2026 Biologics License Application submission, supported by constructive recent FDA interactions that may allow an accelerated approval pathway for MPS IIIB, an ultra-rare disease with no currently approved therapies. Clinical updates have shown encouraging biomarker reductions and functional outcome trends, while management has narrowed strategic focus toward this lead program, reducing total operating expenses by approximately 40% in 2025 and improving net loss to USD 39.0 million from USD 53.0 million in 2024. The company ended 2025 with USD 48.9 million in cash, which increased to an estimated USD 63.9 million following initial Avenue Capital funding, providing runway into early 2027. Spruce is also building commercial capabilities ahead of a potential launch, with added optionality from a Rare Pediatric Disease Priority Review Voucher if approved. However, the investment case remains highly dependent on regulatory success, adequate financing through commercialization, and effective execution in a small, specialized patient market.
As per the above-mentioned price action, important support near USD 50.00-USD 55.00, momentum in the stock over the last month, and technical indicators analysis, a ‘WATCH’ rating has been given for Spruce Biosciences, Inc. (NASDAQ: SPRB) at the current price of USD55.04, as of April 29, 2026, at 06:50 am PDT.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective, and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is April 29, 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...