The Real Brokerage (NASDAQ: REAX)
The Real Brokerage, Inc. (NASDAQ: REAX) engages in the provision of real estate brokerage services. It operates through the following segments: North American Brokerage, One Real Title, One Real Mortgage, and Real Wallet. The North American Brokerage segment generates revenue by processing real estate transactions which entitles the company to commissions. The One Real Title segment manages title insurance and closing services for residential and commercial transactions. The One Real Mortgage segment deals with mortgage transactions between borrowers and lenders. The Real Wallet segment offers interchange fees on company branded debit cards, interest income on certain deposit accounts, and interest income and various fees associated with credit lines.

Key Business and Financial Updates:
- Strategic Acquisition to Create a Global Real Estate Platform: The Real Brokerage Inc. announced an agreement to acquire RE/MAX Holdings in a transformational transaction that will create Real REMAX Group, a technology-enabled global real estate platform. The combined entity would unite Real’s AI-powered brokerage model with RE/MAX’s globally recognized franchise network spanning 120+ countries and territories. Together, the platform is expected to serve more than 180,000 real estate professionals, including over 145,000 RE/MAX agents and Real’s rapidly expanding agent base. The transaction values RE/MAX at approximately USD 880 million enterprise value and is expected to close in the second half of 2026, subject to shareholder and regulatory approvals.
- Strong Financial Growth and Improving Profitability: Real delivered robust standalone fiscal 2025 performance, with revenue increasing 56% year-over-year to USD 2.0 billion, while gross profit rose 44% to USD 165.7 million. Net loss improved significantly to USD (8.1) million from USD (26.5) million in 2024, reflecting stronger scale economics and improving cost discipline. Adjusted EBITDA increased to USD 62.9 million, up from USD 40.0 million in the prior year. In Q4 2025 alone, revenue rose 44% to USD 505.1 million, while adjusted EBITDA increased to USD 14.2 million, highlighting sustained momentum despite a challenging housing environment.
- Operational Expansion and Agent Network Growth: The company continued to gain market share through agent recruitment and transaction growth. Total agents on the platform increased 31% to 31,739 at year-end 2025, rising further to over 33,200 agents by March 2026. Closed transactions increased 54% to 185,314 for full-year 2025, while the total value of completed real estate transactions rose 53% to USD 75.3 billion. Management attributed this momentum to Real’s differentiated value proposition, flexible operating model, proprietary technology, and financial incentives for agents seeking productivity gains and higher earnings potential.
- Synergies, Diversification and Long-Term Value Creation: The RE/MAX transaction is expected to materially enhance earnings quality and diversification. On a pro forma basis, the combined company would have generated approximately USD 2.3 billion in annual revenue and USD 157 million in Adjusted EBITDA before synergies during 2025. Management expects approximately USD 30 million of annual run-rate cost synergies, largely from shared services, public company cost rationalization, and technology efficiencies, contributing around 100 basis points of margin expansion once fully realized. The transaction is also expected to be accretive to earnings and EBITDA margin within the first full year after closing.
- Ancillary Services and Strategic Outlook: Beyond brokerage operations, Real continued expanding adjacent revenue streams through mortgage, title, and fintech offerings. One Real Mortgage generated USD 6.0 million in 2025 revenue, while Real Wallet revenue rose to USD 889 thousand, supported by over 7,000 agent accounts and USD 22.5 million in deposits. With no debt at year-end 2025, USD 49.9 million in unrestricted cash and investments, continued share repurchases, and a larger post-merger operating footprint, Real appears positioned to pursue further scale, cross-selling opportunities, and margin expansion over the medium term.
Key Company specific risks for REAX:
- Housing Market Sensitivity Risk: REAX’s transaction volumes and agent productivity remain exposed to housing affordability pressures, mortgage rates, and broader real estate market activity.
- Integration Execution Risk: Successfully integrating the RE/MAX acquisition, achieving expected synergies, and retaining agents/franchisees will be critical to realizing projected value creation.
- Margin and Competition Risk: Intense competition from traditional brokerages and technology-enabled peers could pressure agent incentives, customer acquisition costs, and long-term margin expansion.
Technical Observation (on the daily chart):
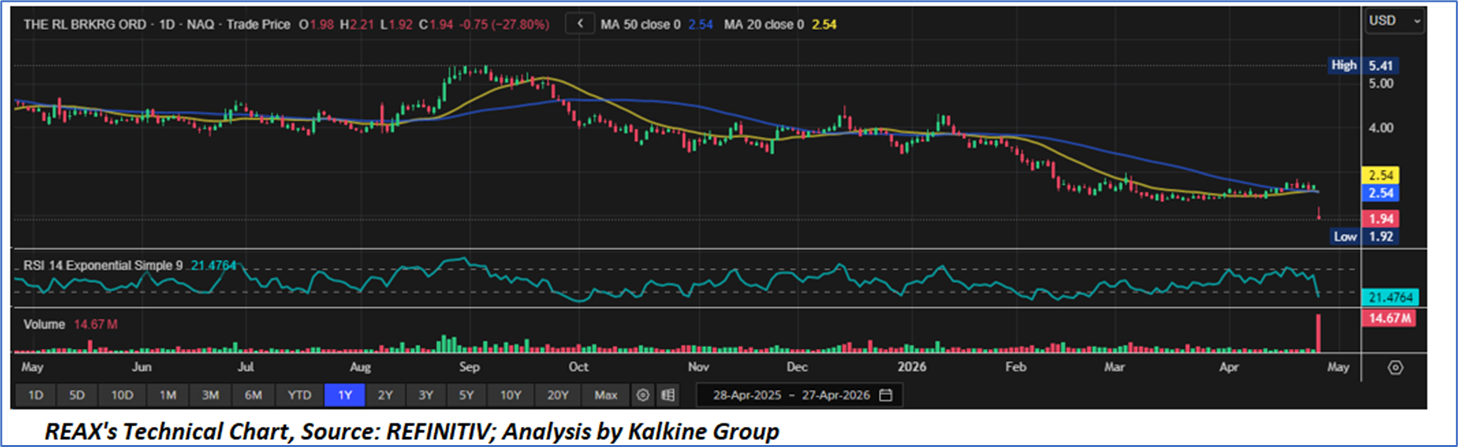
- Primary Trend Weakness and Breakdown Structure: REAX remains in a pronounced medium-term downtrend, with price declining sharply to USD 1.94 after a 80% single-session drop. The stock is trading materially below both the 20-day moving average at USD 2.54 and the 50-day moving average at USD 2.54, confirming sustained bearish trend control. Price action has consistently formed lower highs and lower lows since the September peak near USD 5.41, indicating persistent distribution pressure. The recent breakdown toward the USD 1.92 low suggests sentiment has weakened further and trend reversal signals have not yet emerged.
- Momentum, Oversold Conditions and Volume Signals: Momentum indicators show extreme weakness, with the 14-day RSI at 21.48, firmly in oversold territory. While such readings can sometimes precede technical rebounds, they more commonly reflect aggressive selling pressure when accompanied by elevated volume. The latest session’s volume spike to 67 million shares suggests capitulation-style activity or event-driven liquidation, significantly above prior average participation. Until RSI stabilizes and begins forming higher lows, momentum remains decisively bearish despite the possibility of short-term oversold bounces.
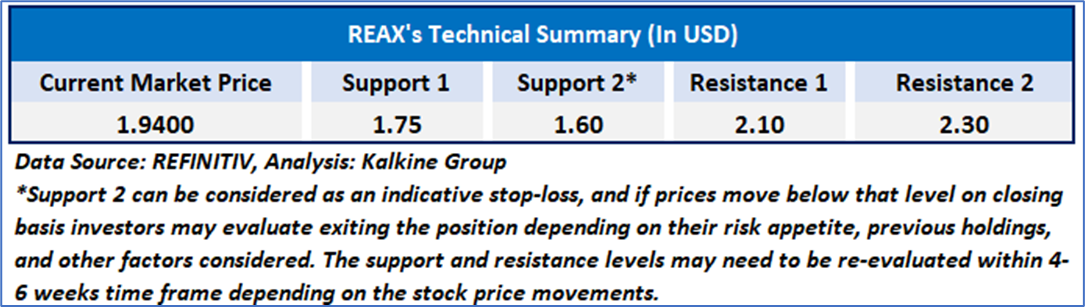
- Key Levels, Tactical Setup and Forward Bias: Immediate support is located near the recent low at USD 1.92; a decisive break below this level could expose downside risk toward psychological support near USD 1.50 and potentially lower. On the upside, first resistance is seen at USD 2.25–2.54, where the short-term moving average cluster now acts as overhead supply. A stronger recovery would require sustained closes above USD 2.54, which could open room toward USD 3.00+. For now, the prevailing technical bias remains cautious-to-bearish, and any recovery attempts may continue to face selling pressure until price reclaims key moving averages with stronger volume confirmation.
The Real Brokerage continues to position itself as a fast-growing technology-enabled real estate platform, supported by strong fiscal 2025 revenue growth of 56% to USD 2.0 billion, improving profitability, expanding agent count to more than 33,200, and rising transaction value of USD 75.3 billion. The proposed acquisition of RE/MAX could significantly broaden scale, adding global franchise reach, diversification benefits, and expected cost synergies, while strengthening long-term earnings potential. The company also maintains a debt-free balance sheet with USD 49.9 million in cash and investments, alongside growing ancillary businesses in mortgage, title, and fintech services. However, performance remains linked to housing market conditions, successful integration of the RE/MAX transaction, and competitive industry dynamics. From a market perspective, recent share price weakness and bearish technical trends suggest investors are balancing long-term strategic upside against near-term execution and macroeconomic uncertainties.
As per the above-mentioned price action, important resistance near USD 2.00-USD 2.20, momentum in the stock over the last month, and technical indicators analysis, a ‘WATCH’ rating has been given for The Real Brokerage, Inc. (NASDAQ: REAX), at the current price of USD1.94, as of April 27, 2026, at 10:50 am PDT.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective, and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is April 27, 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...