Insmed Inc
Insmed Inc (NASDAQ: INSM) is a global biopharmaceutical company focused on developing and commercializing therapies for serious diseases, particularly in pulmonary and inflammatory conditions. Its portfolio includes approved products such as ARIKAYCE for treating Mycobacterium avium complex lung disease, along with a pipeline of mid- to late-stage clinical programs including brensocatib, TPIP, INS1201, and the investigational monoclonal antibody INS1148. The company is also advancing early-stage research across innovative platforms such as gene therapy, AI-driven protein engineering, RNA technologies, and synthetic rescue, supporting long-term drug discovery and development.

Recent Business Development:
- Brinsupri Development Setback in HS Dampens Expansion Prospects: Insmed has discontinued the development of Brinsupri (brensocatib) for hidradenitis suppurativa (HS) after its Phase IIb CEDAR study failed to meet both primary and secondary efficacy endpoints, with results showing better outcomes in the placebo group and no meaningful clinical benefit despite a clean safety profile. This setback follows an earlier failure in a mid-stage study for chronic rhinosinusitis without nasal polyps, raising concerns about the drug’s effectiveness beyond its approved indication. Nevertheless, Brinsupri remains a key commercial asset for Insmed, having secured FDA approval in August 2025 as the first treatment for non-cystic fibrosis bronchiectasis, and currently stands as the company’s second marketed product alongside Arikayce.
Key Growth Aspects
- Robust Commercial Growth Driven by BRINSUPRI Launch: Insmed demonstrated a strong commercial inflection in FY2025, supported by the successful U.S. launch of BRINSUPRI, which generated USD 172.7 million in full-year revenues and USD 144.6 million in Q4 alone. This performance significantly contributed to total company revenues rising to USD 606.4 million, reflecting a 67% year-over-year increase. The launch trajectory exceeded expectations, positioning the product as a potential blockbuster with anticipated revenues of at least USD 1 billion in 2026, indicating strong physician adoption and commercial execution.
- Sustained Growth of ARIKAYCE Franchise: The ARIKAYCE franchise continued to deliver consistent growth, with FY2025 revenues reaching USD 433.8 million, marking a 19% year-over-year increase and surpassing guidance. Growth was broad-based across geographies, supported by increasing adoption and potential label expansion opportunities. The anticipated Phase 3 ENCORE data and subsequent regulatory submissions could further expand the addressable market, reinforcing ARIKAYCE as a stable and recurring revenue driver.
- Strong Pipeline Advancement and Clinical Momentum: Insmed maintained significant progress across its clinical pipeline, including Phase 3 development programs for TPIP and continued advancement of gene therapy and immunology assets. The FDA’s orphan drug designation for TPIP and multiple upcoming data readouts provide near-term catalysts. Additionally, the acquisition of INS1148 and ongoing development across respiratory, immunology, and rare disease segments highlight a diversified pipeline with long-term value creation potential.
- Solid Liquidity Position Supporting Strategic Investments: The company ended FY2025 with approximately USD 1.4 billion in cash, cash equivalents, and marketable securities, providing a strong liquidity buffer. This financial strength supports continued investment in commercialization, R&D, and pipeline expansion without immediate capital constraints. Management also indicated confidence in achieving cash flow positivity while maintaining flexibility for strategic initiatives, reinforcing balance sheet resilience.
Growth Challenges
- Widening Net Losses Amid Elevated Cost Structure: Despite strong revenue growth, Insmed reported a significant increase in net losses, with FY2025 net loss expanding to USD 1,276.8 million compared to USD 913.8 million in FY2024. The widening losses reflect the high cost base associated with commercialization efforts and pipeline investments, raising concerns regarding near-term profitability and earnings visibility.
- Escalation in R&D and SG&A Expenses: Operating expenses increased substantially, with R&D expenses rising to USD 771.1 million and SG&A expenses to USD 701.2 million in FY2025. These increases were driven by clinical development activities, compensation costs, and commercialization readiness for BRINSUPRI. While necessary for growth, the elevated spending pressures margins and contributes to continued operating losses.
- Dependence on Key Products for Revenue Growth: Insmed’s revenue base remains concentrated around BRINSUPRI and ARIKAYCE, making the company highly dependent on the continued success and expansion of these products. Any setbacks in commercialization, regulatory approvals, or competitive dynamics could materially impact revenue growth, highlighting limited diversification in near-term revenue streams.
- Regulatory and Clinical Execution Risks: The company’s growth outlook is closely tied to clinical trial outcomes and regulatory approvals, including Phase 3 readouts and label expansion efforts. Delays, unfavorable data, or regulatory hurdles could impact commercialization timelines and pipeline valuation. Additionally, reliance on confirmatory trials for ARIKAYCE’s broader approval introduces execution uncertainty.
Key Risks:
- High Cash Burn Risk: Continued elevated R&D and SG&A spending may delay profitability despite revenue growth.
- Regulatory Dependency: Future growth depends on successful clinical trials and regulatory approvals.
- Product Concentration Risk: Heavy reliance on BRINSUPRI and ARIKAYCE for revenue generation.
- Commercial Execution Risk: Failure to sustain launch momentum or achieve expected market penetration could impact forecasts.
Technical Observation (on the daily chart):
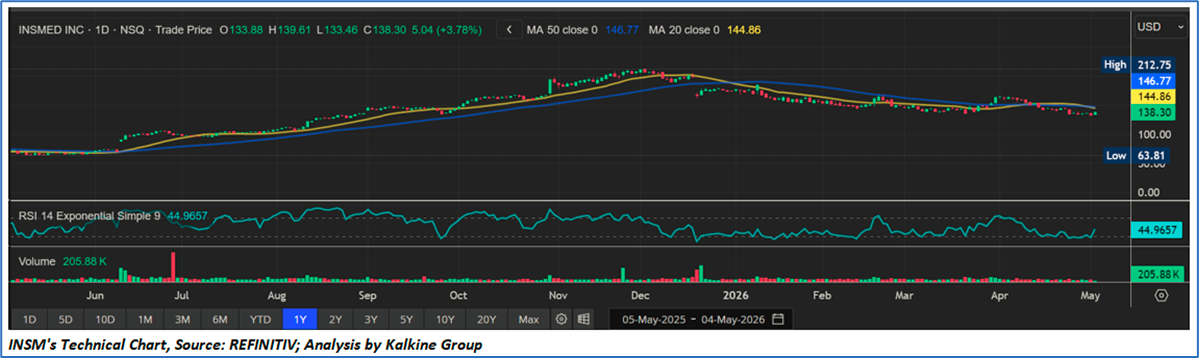
- The stock exhibited a strong uptrend in mid-2025, forming higher highs and higher lows while consistently trading above the 20-day and 50-day moving averages, indicating sustained bullish momentum.
- Toward late 2025, the trend reversed as the price peaked and entered a correction phase, breaking below key moving averages and forming lower highs, signaling weakening momentum and a shift in sentiment.
- In early 2026, the stock moved into a consolidation phase, trading within a narrow range with limited directional clarity and reduced volatility.
- The convergence of the 20-day and 50-day moving averages suggests indecision in the market and the absence of a strong trend.
- The RSI remains around the mid-40 level, indicating neutral momentum with a slight bearish bias, as it stays below the 50 mark without being oversold.
- Volume activity appears muted, reflecting limited participation and supporting the ongoing consolidation trend.
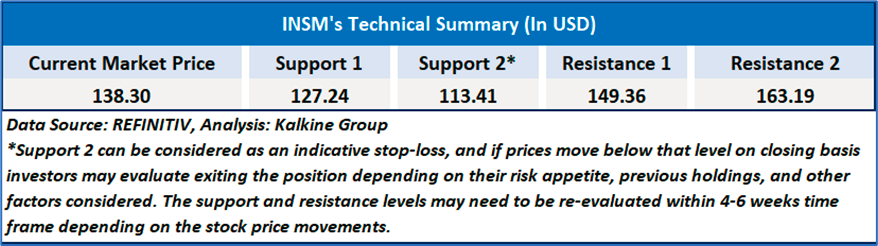
- Overall, the chart indicates a base-building phase, with future direction dependent on a breakout above resistance or a breakdown below support levels
Insmed presents a compelling growth narrative supported by a strong commercial launch of BRINSUPRI, consistent ARIKAYCE performance, and a robust pipeline with multiple clinical catalysts. However, the company continues to operate with substantial losses driven by high R&D and commercialization investments, alongside execution and regulatory risks. The overall outlook reflects a high-growth, high-investment profile with long-term potential balanced by near-term financial pressures..
As per the above-mentioned price action, recent key business and financial updates, momentum in the stock over the last month, and technical indicators analysis, a ‘Watch’ rating has been Insmed Inc (NASDAQ: INSM) at the current market price of USD 138.30 as of May 04,2026 at 7:11 am PDT.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is May 04,2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...