Affirm Holdings, Inc. (NASDAQ: AFRM) is a leading financial technology company and pioneer of the Buy Now, Pay Later (BNPL) model in the United States. Founded in 2012 by Max Levchin (co-founder of PayPal), Affirm operates a next-generation commerce and payments platform that enables consumers to pay for purchases in transparent, flexible installments — with no hidden fees, no compound interest, and no deceptive pricing. Its platform connects consumers, merchants, and capital partners through a vertically integrated fintech ecosystem, leveraging proprietary AI-driven credit decisioning to serve a broad consumer base across prime and near-prime credit segments.

Key Metrics:
- Revenue Growth: Affirm has posted a strong multi-year revenue trajectory, with net revenues rising from USD 1,349.0 million in FY2022 to USD 2,765.3 million in FY2025, representing a 4-year CAGR of approximately 27.2%. The company's consumption-driven model — tied to merchant GMV flow-through, interchange, and servicing fees — has proved resilient even through rising rate environments, with growth accelerating meaningfully as new merchant integrations ramped and existing accounts deepened penetration.
- Gross Profit Expansion: Gross profit grew from USD 693.3 million in FY2022 to USD 1,449.0 million in FY2025, implying a 4-year CAGR of 27.9%, slightly outpacing revenue growth. Gross margin stabilized in the 50–53% range, reflecting Affirm's balanced model between transaction revenue (lower margin) and high-margin interest and service income. The company's credit loss provisioning discipline has been central to preserving gross economics through credit cycles.
- Profitability Inflection: The most significant financial milestone has been Affirm's adjusted operating income turning positive, reaching USD 337.1 million in FY2025 from losses of USD 176–248 million in prior years. This trajectory reflects meaningful operating leverage, disciplined headcount management, and improving unit economics as the loan book scales and funding costs normalize. GAAP profitability remains the next milestone, expected to approach breakeven in FY2026 as operating leverage continues to compound.
Business Updates and Financial Highlights
Recent Updates:
- Amazon Partnership Deepened: Affirm extended and expanded its exclusive BNPL partnership with Amazon, now embedded across Amazon.com, Amazon Pay, and Whole Foods checkout flows. This integration alone accounts for an estimated 10–14% of total GMV.
- Apple Pay Integration: Affirm became one of the first BNPL providers natively integrated into Apple Pay via iOS 17+, dramatically expanding consumer touchpoints without incremental CAC. Millions of Apple device users can now access Affirm financing at checkout.
- Shopify Collaboration: Affirm renewed its Shopify partnership through 2028, cementing its position as the exclusive BNPL option for Shopify Pay Installments in the U.S. and Canada, covering millions of merchant storefronts.
- Affirm Card Launch: The Affirm Card, a debit card with built-in BNPL capabilities, surpassed 1.4 million active cardholders in FY2025, representing a strategic move into recurring, everyday spending categories beyond traditional e-commerce checkouts.
- B2B and Healthcare Expansion: Affirm launched tailored solutions for healthcare payment plans and enterprise B2B procurement financing, opening multi-billion dollar TAM extensions well beyond its traditional consumer retail roots.
- AI Underwriting Enhancements: Proprietary ML models now evaluate over 200+ data signals per application, resulting in improved loan performance and expanded credit access for underserved near-prime consumers without commensurate loss rate deterioration.
Insights of FY2025 Financial Results:
- Total Net Revenue: USD 2,765.3 million, up 19.3% YoY, driven by GMV expansion of 18% to USD 29.2 billion and improved monetization rates.
- Gross Merchandise Volume (GMV): USD 29.2 billion, reflecting robust consumer demand and new merchant vertical penetration. Transaction frequency per active consumer rose to approximately 4.7x annually.
- Adjusted Operating Income: USD 337.1 million (margin of ~12.2%), a dramatic improvement from the near-breakeven FY2024 figure, driven by operating leverage and disciplined cost management.
- Active Merchants: Approximately 320,000 active merchants on the platform as of FY2025 year-end, spanning e-commerce, retail, travel, healthcare, and enterprise verticals.
- Net Revenue Retention: ~136%, indicating strong cross-sell and GMV expansion within existing merchant cohorts — a key indicator of platform health and merchant stickiness.
- Credit Quality: Net charge-off rates improved modestly to ~3.8% of average loan balances, reflecting both model enhancements and a stable macroeconomic consumer credit backdrop. Provisions are well-reserved with an allowance coverage ratio of approximately 8.2%.
- Balance Sheet: Cash and equivalents of USD 2.4 billion as of FY2025 year-end. Total debt stood at approximately USD 7.2 billion, primarily comprising securitization facilities and warehouse lines — well within covenant thresholds.
Key Risks and Outlook
Key Risks:
- Regulatory and Legal Risk: The CFPB has signaled increased scrutiny of BNPL products, with proposed rules that could require credit card-like disclosures, dispute resolution rights, and periodic billing statements. Any adverse regulatory ruling could increase compliance costs and potentially dampen consumer demand.
- Credit and Economic Risk: Affirm's loan portfolio is primarily unsecured and susceptible to consumer credit deterioration in recessionary environments. A spike in unemployment or consumer stress could elevate charge-off rates and compress net interest margins.
- Interest Rate Sensitivity: While the rate environment has eased modestly from 2023 peaks, Affirm's cost of funds remains sensitive to duration mismatches between loan originations and ABS funding. Sustained elevated rates could impair spread economics.
- Competitive Landscape: Klarna, Afterpay (Block), PayPal Pay Later, and increasingly traditional card issuers (Citi Flex Pay, Chase Slate Edge) are expanding BNPL offerings. Differentiation will hinge on underwriting quality, merchant experience, and consumer trust.
- Concentration Risk: Amazon and Shopify collectively represent a disproportionate share of GMV. Any deterioration in these key partnerships could have an outsized impact on revenue and network effects.
- GAAP Profitability Timeline: Although adjusted operating income is positive and growing, GAAP net losses persist due to stock-based compensation and depreciation charges. Investors focused on GAAP metrics may apply a valuation discount until full GAAP profitability is achieved.
Outlook:
Affirm's strategic outlook remains constructive across multiple dimensions. Management has guided for continued GMV growth of approximately 15–20% in FY2026, with adjusted operating margin expanding to the 15–17% range on a base of approximately USD 3.2 billion in net revenues. The company expects the Affirm Card to reach 2 million+ active cardholders, further diversifying its revenue stream beyond traditional checkout-based BNPL. International expansion into Canada and exploratory discussions regarding UK and Australian markets represent additional medium-term optionality. The company's platform strategy — connecting consumers, merchants, and capital markets through a single fintech operating system — continues to accumulate defensible network advantages that become increasingly difficult for pure-play BNPL disruptors to replicate.
Technical Observation (on the daily chart):
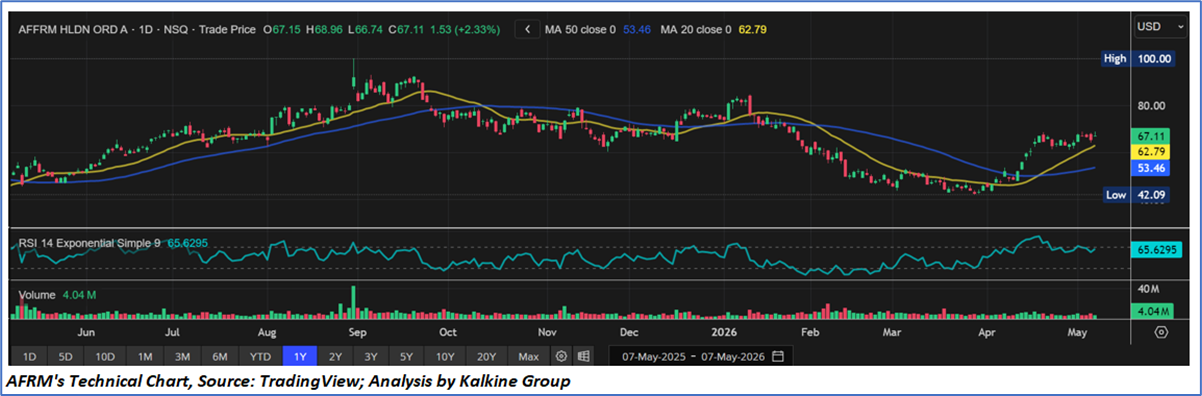
- Improving Trend Structure: Affirm Holdings, Inc. (NASDAQ: AFRM) is showing a constructive medium-term trend, supported by a strong recovery from recent lows and improving price momentum.
- Trading Above Key Moving Averages: The stock is currently trading above both the 20-day moving average (around USD 62.79) and the 50-day moving average (around USD 53.46), indicating strengthening bullish sentiment and a favorable technical setup.
- Higher Highs and Higher Lows Formation: Recent price action reflects a pattern of higher highs and higher lows, suggesting sustained buying interest and improving market confidence.
- Momentum Remains Supportive: The RSI is hovering near 65, indicating strong momentum while remaining below extreme overbought levels, which supports the continuation of the upward trend.
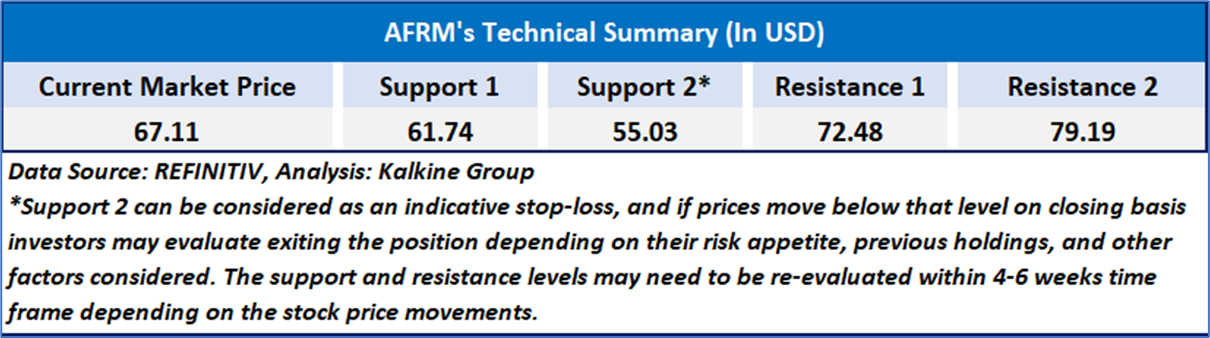
- Near-Term Outlook: If the stock sustains above the USD 62–63 support range, it may continue advancing toward higher resistance levels near USD 75–80 over the medium term.
- Risk Consideration: Despite the positive setup, short-term consolidation or mild pullbacks may emerge following the recent rally, particularly if the stock fails to hold above key moving averages.
Affirm presents a compelling risk-reward opportunity at the current price of USD 67.15. The company has successfully navigated the high interest rate cycle, demonstrating meaningful operating leverage and a decisive inflection toward adjusted profitability. With GMV compounding in the high-teens, Net Revenue Retention above 130%, and an expanding merchant network anchored by Amazon, Shopify, and Apple Pay, Affirm is building durable structural advantages in the BNPL segment. Its AI-powered underwriting model continues to differentiate credit quality while enabling penetration into new verticals including healthcare, travel, and enterprise B2B payments.
As per the above-mentioned price action, recent key business and financial updates, momentum in the stock over the last month, and technical indicators analysis, a ‘Buy’ rating has been given Affirm Holdings, Inc. (NASDAQ: AFRM) at the current market price of USD 67.11, as of May 07,2026 at 12:10 pm PDT.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is May 07,2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...