The Campbell’s Company
The Campbell’s Company (NASDAQ: CPB) is a North America-focused food and beverage manufacturer operating through two divisions: Meals & Beverages and Snacks. Its portfolio includes well-known brands such as Campbell’s, Goldfish, Pepperidge Farm, Rao’s, Kettle Brand, Snyder’s of Hanover, and V8. The company produces soups, sauces, snacks, beverages, and organic food products, while also supplying tailored food solutions to healthcare, restaurant, education, and hospitality sectors through its North American Foodservice division.

Key Growth Aspects
- Strength in the Meals & Beverages Portfolio: The company’s Meals & Beverages segment continued to demonstrate resilience during Q2 FY26, supported by stable consumer demand and strong brand positioning. In-market dollar consumption for this segment increased by approximately 2% year-over-year, reflecting sustained demand for cooking-related food products and at-home meal solutions. This performance highlights the segment’s ability to maintain relevance amid shifting consumer spending patterns and reinforces the importance of the company’s core food brands in household consumption trends.
- Strong Brand Momentum Driven by Rao’s: One of the most notable positive developments during the quarter was the continued growth of the Rao’s brand, which surpassed USD 1 billion in trailing twelve-month net sales. The brand recorded approximately 14.5% consumption growth during the quarter, supported by increasing household penetration and strong shelf productivity across U.S. retail markets. Rao’s premium positioning and strong consumer loyalty have made it one of the fastest-growing brands within the company’s portfolio, strengthening the company’s long-term growth prospects.
- Product Innovation Supporting Future Growth: The company continued to invest in innovation initiatives aimed at strengthening its leadership brands and expanding consumer engagement. A notable example includes the launch of Campbell’s Condensed Sauces, designed to address a growing demand for convenient at-home cooking solutions. The product platform targets a sizeable addressable market within the meal preparation category and aims to reinforce the brand’s position as a core ingredient in home cooking occasions.
- Sequential Improvement in Key Snack Brands: Despite broader challenges in the Snacks segment, the company reported encouraging signs of recovery in specific brands, particularly Goldfish. Sequential improvements in consumption trends were observed as the company refined its value architecture and simplified product offerings. Targeted innovation and improved retail execution have contributed to strengthening the brand’s performance among households with children, a highly resilient consumer cohort within the snacking category.
Growth Challenges
- Decline in Overall Revenue Performance: The company experienced a decline in overall revenue during Q2 FY26, with net sales decreasing by approximately 5% year-over-year to USD 2.6 billion. Organic net sales declined by around 3%, primarily due to unfavorable volume and product mix dynamics. These results reflect a challenging operating environment characterized by shifting consumer demand patterns and operational disruptions affecting certain business segments.
- Significant Profitability Pressure: Profitability metrics weakened considerably during the quarter as operating margins and earnings declined. Adjusted EBIT fell approximately 24% year-over-year to USD 282 million, while adjusted earnings per share declined by around 31% to USD 0.51. The decline was largely driven by lower gross profit, cost inflation, tariff impacts, and operational inefficiencies affecting the company’s supply chain and production activities.
- Weak Performance in the Snacks Segment: The Snacks business emerged as the primary drag on the company’s overall performance during the quarter. Organic net sales in this segment declined by approximately 6% year-over-year, largely due to lower consumption trends, execution challenges within the Fresh Bakery operations, and increased competitive intensity in the salty snacks category. These factors collectively pressured both sales volumes and segment operating earnings.
- Margin Pressure from Inflation and Tariffs: The company’s gross profit margin experienced a significant contraction due to persistent cost inflation and tariff-related pressures. Adjusted gross margin declined by approximately 270 basis points to 27.7%, reflecting rising input costs across raw materials, packaging, transportation, and supply chain expenses. Although cost-saving initiatives partially offset these headwinds, the overall cost environment continued to weigh on profitability.
Key Risks:
- Segment Execution Risk: Ongoing operational disruptions and execution challenges within the Snacks segment, particularly in Fresh Bakery and salty snacks categories, may continue to pressure volumes, market share, and segment profitability.
- Input Cost and Tariff Exposure: Persistent cost inflation across raw materials, packaging, labor, and transportation, along with tariff-related expenses, could further compress margins despite ongoing cost-saving initiatives.
- Competitive Intensity in Packaged Foods: Rising competition from private labels and branded food companies, particularly in snacks, soups, and sauces, may impact pricing power, shelf positioning, and consumer demand.
- Supply Chain and Operational Disruptions: Weather events, logistics constraints, and manufacturing inefficiencies could lead to shipment delays, increased operating costs, and temporary sales disruptions across key product categories.
Technical Observation (on the daily chart):
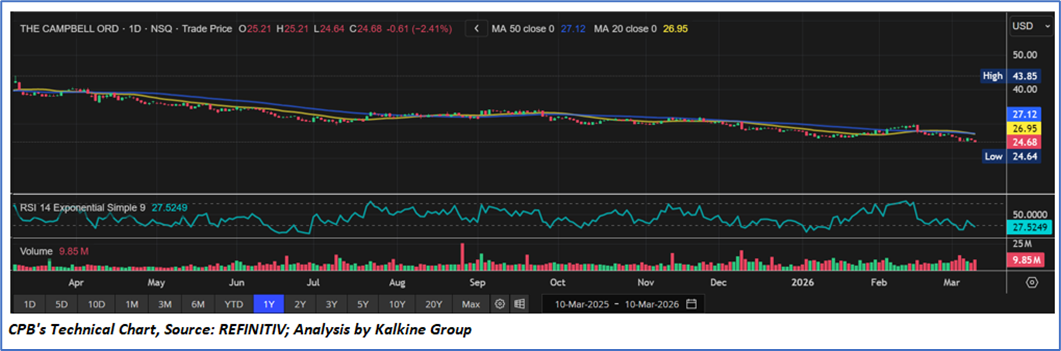
- The stock has been trading in a sustained downward trajectory over the past year, characterized by a sequence of lower highs and lower lows, indicating continued bearish momentum and weak investor sentiment.
- The price remains below both the 20-day moving average (USD 26.95) and the 50-day moving average (USD 27.12), suggesting that short-term trend indicators continue to act as overhead resistance and confirm the prevailing negative trend.
- The Relative Strength Index (RSI) is around 27 range, indicating oversold conditions and trending slightly downward, reflecting subdued momentum and the absence of strong buying pressure in the near term.
- Trading volumes appear relatively moderate with occasional spikes during declines, indicating intermittent selling pressure rather than strong accumulation by buyers.
The Campbell’s Company reported mixed operational and financial performance during Q2 FY26, reflecting both areas of resilience and near-term challenges. The company continued to benefit from stable consumer demand in its Meals & Beverages segment, supported by strong brand momentum from Rao’s, which surpassed USD 1 billion in trailing twelve-month net sales and drove consumption growth across the portfolio. However, overall results were weighed down by weaker performance in the Snacks segment, operational disruptions in Fresh Bakery, and heightened competitive intensity within salty snacks. These pressures contributed to declines in net sales, profitability, and margins, further exacerbated by cost inflation, tariffs, and temporary shipment delays. While the company’s strong brand portfolio and innovation initiatives support long-term growth potential, the near-term operating environment remains challenging, resulting in a balanced outlook for the business.
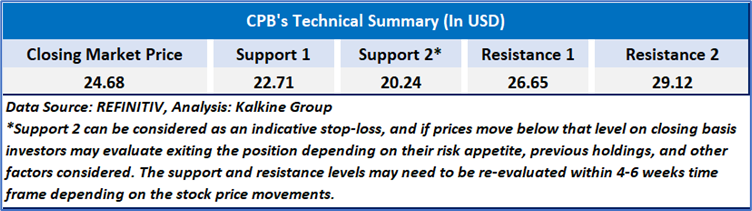
As per the above-mentioned price action, recent key business and financial updates, momentum in the stock over the last month, and technical indicators analysis, a ‘Watch’ rating has been The Campbell’s Company (NASDAQ: CPB) at the closing market price of USD 24.68 as of March 10,2026.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is March 10,2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...