Novo Nordisk A/S
Novo Nordisk A/S (NYSE: NVO) is a global healthcare company engaged in diabetes care. The Company is also engaged in the discovery, development, manufacturing and marketing of pharmaceutical products. The Company operates through two business segments: diabetes and obesity care, and biopharmaceuticals. The Company's diabetes and obesity care segment covers insulin, GLP-1, other protein-related products, such as glucagon, protein-related delivery systems and needles, and oral anti-diabetic drugs.

Key Business and Financial Updates:
- 2025 Financial Performance: Solid CER Growth Amid Transformation Costs: Novo Nordisk reported 10% sales growth and 6% operating profit growth at constant exchange rates (CER) for 2025, broadly in line with prior guidance. Net sales reached DKK 309.1 billion, up 6% in Danish kroner, while operating profit totalled DKK 127.7 billion, reflecting a 1% decline as reported but a 6% increase at CER. Excluding approximately DKK 8 billion in costs related to a company-wide transformation, operating profit would have risen 13% at CER. Growth was supported by strong demand in obesity care, where sales increased 31% at CER, and by continued expansion in International Operations.
- Business Mix and Product Momentum: Obesity and GLP-1 at the Core: Sales within Obesity and Diabetes care rose 10% at CER, driven primarily by obesity treatments and GLP-1 based therapies. Rare disease sales also advanced at mid-single-digit rates. In the United States, sales grew 8% at CER, partly benefiting from gross-to-net sales adjustments, while International Operations expanded 14% at CER. A key milestone was the US launch of once-daily oral semaglutide 25 mg under the Wegovy® brand in January 2026, with early prescription uptake reaching approximately 50,000 weekly prescriptions, largely through the self-pay channel. The company also progressed multiple next-generation pipeline assets, including CagriSema and zenagamtide.
- 2026 Outlook: Adjusted Sales and Operating Profit Expected to Decline at CER: For 2026, Novo Nordisk introduced new non-IFRS adjusted measures to enhance transparency by excluding exceptional and non-recurring items, notably the reversal of USD 4.2 billion in sales rebate provisions related to the US 340B Drug Pricing Program. On an adjusted basis, sales and operating profit are expected to decline between 5% and 13% at CER. Pricing headwinds in the US, including impacts from the “Most Favoured Nations” agreement and reduced realised prices, along with patent expiries for semaglutide in certain international markets, are expected to weigh on performance. On a non-adjusted basis, the mid-point guidance implies sales growth of approximately -1% and operating profit growth of 11% at CER.
- Clinical Update: CagriSema Trial Results and Regulatory Pathway: In February 2026, Novo Nordisk announced results from the REDEFINE 4 phase 3 trial comparing CagriSema with tirzepatide in people with obesity. While CagriSema achieved 23% weight loss after 84 weeks, it did not meet the primary endpoint of demonstrating non-inferiority versus tirzepatide. The treatment showed a safety profile consistent with the GLP-1 class, with mostly mild-to-moderate gastrointestinal events. CagriSema has been submitted to the US FDA based on earlier pivotal trials, with a regulatory decision anticipated in late 2026. Additional trials, including higher-dose combinations, are planned to further explore its full therapeutic potential.
- Capital Allocation and Strategic Positioning in a Competitive Market: Despite anticipated pricing and competitive pressures in 2026, Novo Nordisk continues to prioritise investment in research and commercial capabilities, particularly within its GLP-1 portfolio. Adjusted operating profit expectations reflect targeted R&D expansion and commercial investments, partly offset by savings from optimisation initiatives. The Board has proposed a total dividend of DKK 11.70 per share for 2025 and initiated a new share repurchase programme of up to DKK 15 billion. As the global GLP-1 market expands, Novo Nordisk’s strategic focus remains on increasing patient reach, launching higher-dose and oral formulations, and advancing next-generation assets, even as pricing dynamics and intensifying competition reshape the operating environment.
Key Company specific risks for NVO:
- Pricing and Reimbursement Pressure: Novo Nordisk faces material pricing headwinds, particularly in the United States, including the impact of the “Most Favoured Nations” framework, evolving rebate structures, and reduced obesity drug coverage in certain public programmes. Lower realised prices and adverse gross-to-net dynamics could weigh on revenue growth and margin expansion.
- Patent Expiry and Competitive Intensity: Loss of exclusivity for semaglutide in selecting international markets introduces generic risk, while intensifying competition in the GLP-1 and obesity segments—particularly from rival next-generation therapies—may pressure market share and pricing power. Clinical differentiation and lifecycle management will be critical to sustaining competitive positioning.
- Pipeline and Execution Risk: Future growth depends on successful regulatory approvals, clinical trial outcomes, and commercial execution of next-generation assets such as CagriSema and other metabolic therapies. Delays, unfavourable trial data, manufacturing constraints, or slower-than-expected uptake of new launches could affect earnings visibility and strategic momentum.
Technical Observation (on the daily chart):
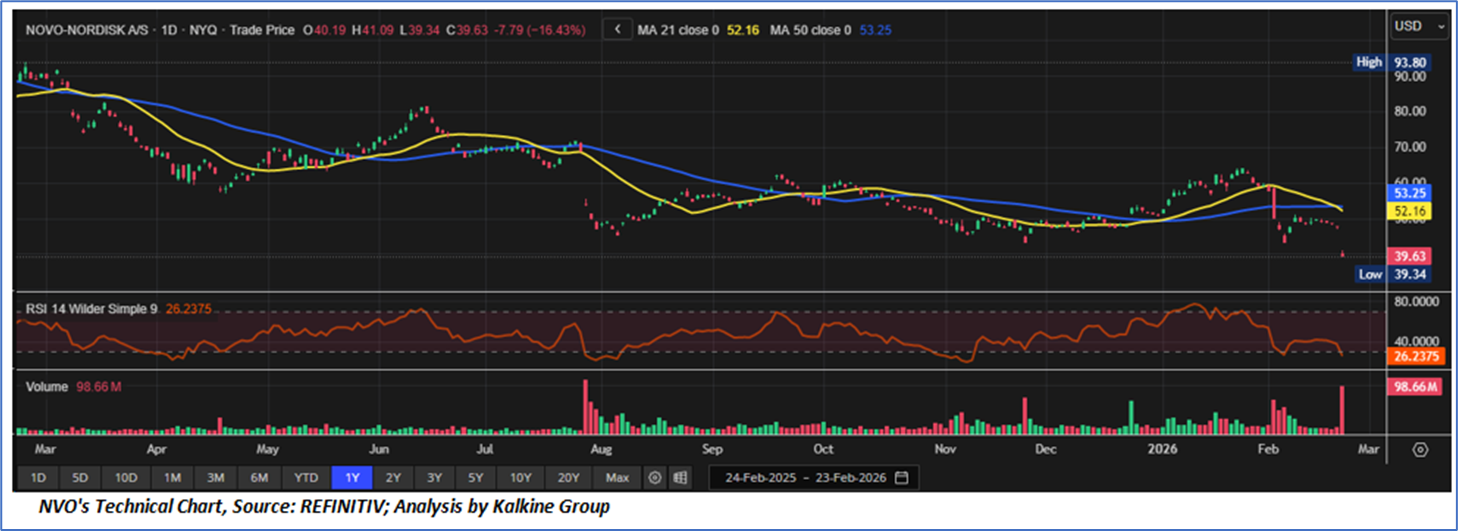
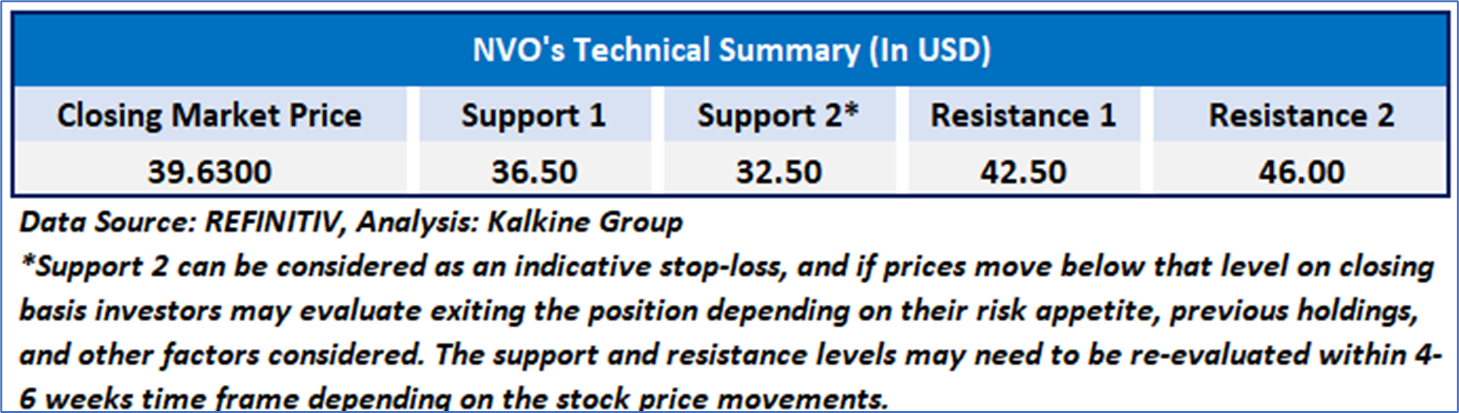
- Prevailing Trend Structure: Entrenched Downtrend with Breakdown Below Key Moving Averages: The daily chart for Novo Nordisk (NVO) reflects a pronounced medium-term downtrend, characterised by a sequence of lower highs and lower lows since mid-2025. Price action has decisively broken below both the 21-day and 50-day moving averages, with the shorter-term average trending beneath the longer-term average—an alignment typically associated with sustained technical weakness. The recent sharp decline toward the USD 39–40 range marks a breakdown below prior consolidation support, reinforcing bearish structural momentum unless a sustained recovery above dynamic resistance levels materialises.
- Momentum Indicators: Oversold Conditions with Limited Reversal Signals: The 14-day Relative Strength Index (RSI) has retreated into the mid-20s, indicating deeply oversold conditions. While such readings can precede short-term technical rebounds, they do not, in isolation, signal a durable trend reversal. Notably, the absence of clear bullish divergence between price and RSI during recent lows suggests that downside momentum remains dominant. Until momentum stabilises above the neutral 40–50 zone, rallies may be viewed as corrective within a broader declining framework.
- Volume and Participation Dynamics: Elevated Selling Pressure: Volume activity has expanded meaningfully during recent downward sessions, indicating heightened participation accompanying the price breakdown. This pattern is typically interpreted as distribution rather than orderly consolidation. The acceleration in turnover near new lows suggests that institutional positioning may be adjusting in response to evolving fundamentals. In aggregate, the technical configuration points to a stock under sustained pressure, with any stabilisation phase likely contingent upon reduced volatility and a reclaiming of short- to medium-term moving average resistance levels.
Novo Nordisk remains a global leader in diabetes and obesity care, delivering 10% sales growth and 6% operating profit growth at constant exchange rates in 2025, supported by strong demand for GLP-1–based therapies and obesity treatments, despite transformation-related costs. The company has expanded its product portfolio with the US launch of oral Wegovy® and continued pipeline progression, including CagriSema, although the latter did not meet its primary non-inferiority endpoint in a recent head-to-head trial. For 2026, adjusted sales and operating profit are expected to decline at CER, reflecting pricing headwinds in the US, patent expiries in certain international markets, and intensifying competition, partly offset by ongoing volume growth in the expanding global GLP-1 market. Capital allocation remains focused on R&D investment, commercial expansion, dividends, and share repurchases. Key risks include reimbursement pressure, competitive intensity, patent loss exposure, and pipeline execution uncertainty, while technically the stock remains in a medium-term downtrend with elevated selling pressure and oversold momentum conditions.
As per the above-mentioned price action, important support near USD 36.00- USD 38.00, momentum in the stock over the last month, and technical indicators analysis, a ‘WATCH’ rating has been given for Novo Nordisk A/S (NYSE: NVO), at the closing price of USD39.63, as of February 23, 2026.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective, and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is February 23, 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...