Company Overview
Rubrik, Inc (NYSE: RBRK) is a cloud-based data security and management company offering a Zero Trust Data Security platform. The company enables organizations to enhance business resilience by safeguarding critical data from cyber threats, insider risks, and operational disruptions. Rubrik’s core offering, the Rubrik Security Cloud (RSC), delivers comprehensive data protection across on-premises infrastructure, public cloud environments, and software-as-a-service (SaaS) applications.

Key Growth Drivers
- Strong Subscription-Led Revenue Momentum: Rubrik continues to deliver robust top-line growth, driven by strong subscription momentum. In Q3 FY2026, total revenue increased 48% year-over-year to USD 350.2 million, primarily supported by a 52% year-over-year rise in subscription revenue to USD 336.4 million. Subscription revenue now constitutes an overwhelming majority of total revenue, underscoring the scalability and resilience of the company’s recurring revenue model.
- Sustained Expansion in Recurring Revenue Base: Subscription Annual Recurring Revenue (ARR) rose 34% year-over-year to USD 1.35 billion as of October 31, 2025. This growth reflects continued customer acquisition and expansion within the existing customer base. The number of customers generating more than USD 100,000 in subscription ARR increased 27% year-over-year to 2,638, highlighting deeper penetration into large enterprise accounts and increasing wallet share.
- Improving Profitability and Operating Leverage: Profitability metrics showed meaningful improvement during the quarter. GAAP gross margin expanded to 80.5% from 76.2% in the prior-year period, while non-GAAP gross margin improved to 82.8%. Importantly, the subscription ARR contribution margin turned positive at 10.3%, compared with a negative margin in the year-ago quarter, indicating improving operating leverage as revenue growth outpaces cost expansion.
- Strengthening Cash Flow Profile and Balance Sheet: Rubrik generated USD 76.9 million in free cash flow during Q3 FY2026, a substantial improvement from USD 15.6 million in the corresponding prior-year period. Cash, cash equivalents, and short-term investments totaled USD 1.6 billion, providing ample financial flexibility to support continued investments in innovation, go-to-market initiatives, and strategic partnerships.
Growth Challenges and Risks
- Continued GAAP-Level Losses: Despite strong revenue growth and margin expansion, Rubrik remains loss-making on a GAAP basis. In Q3 FY2026, GAAP net loss per share narrowed to USD (0.32) from USD (0.71) in the prior-year quarter. While the trend is improving, the company has not yet achieved full accounting profitability.
- Elevated Stock-Based Compensation: Stock-based compensation remains a significant expense, totaling USD 82.5 million during the quarter. Although lower than the prior-year level, this continues to pressure GAAP earnings and introduces dilution risk over time as the company scales operations and retains talent through equity-based incentives.
- Dependence on Sustained High Growth Rates: Rubrik’s financial trajectory is highly dependent on maintaining strong double-digit growth in subscription ARR and enterprise deal wins. Any slowdown in enterprise IT spending, elongated sales cycles, or increased pricing pressure within the cybersecurity and data resilience market could adversely impact growth momentum and delay the path to profitability.
- Execution Risk Amid Platform Expansion: The company is expanding its platform across cyber resilience, identity security, and AI-driven operations. While strategically attractive, this expansion increases execution complexity, including risks related to product integration, customer adoption, and go-to-market alignment. Execution missteps could affect operating efficiency and slow monetization of newer offerings.
Key Risks:
- Sustained Growth Dependency: The company’s financial trajectory remains highly dependent on maintaining strong double-digit growth in subscription ARR and enterprise deal wins; any slowdown in customer additions or expansions could materially impact revenue visibility and operating leverage
- Path to GAAP Profitability: Despite improving margins and cash generation, the business continues to report GAAP losses, with elevated operating costs and stock-based compensation posing a risk to the timing and sustainability of full profitability
- Competitive and Technological Intensity: Operating in a rapidly evolving cybersecurity and AI landscape exposes the company to heightened competition from both established vendors and new entrants, increasing pressure on pricing, innovation cadence, and customer retention
- Execution Complexity at Scale: Ongoing expansion across cloud, identity, and AI-driven solutions increases operational and integration complexity, raising execution risk as the company scales its platform, partnerships, and global footprint.
Technical Observation (on the daily chart):
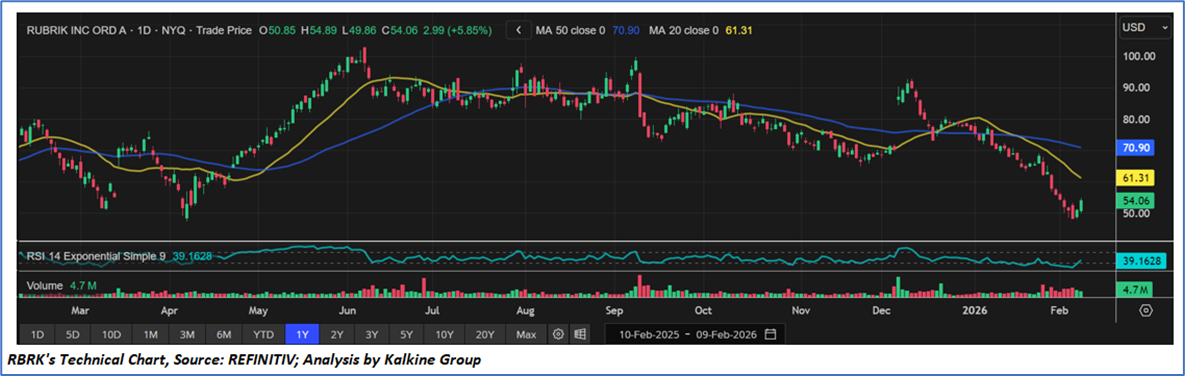
- The stock remains in a medium-term downtrend, with prices consistently trading below the declining 20-day and 50-day moving averages.
- The 50-day moving average at approximately USD 70.9 remains above the 20-day moving average near USD 61.3, confirming a bearish trend structure and sustained selling pressure.
- Recent pullbacks have repeatedly failed near the moving averages, indicating these levels are acting as overhead resistance rather than support.
- The Relative Strength Index (RSI-14) is positioned in the sub-40 range, reflecting weak momentum and limited buying interest, though conditions are not yet deeply oversold.
- The broader price structure continues to show lower highs and lower lows since the December peak, keeping the near-term trend bias negative.
- Trading volumes during recent rebounds remain subdued, suggesting a lack of strong buyer conviction.
Conclusion and Rating
Rubrik presents a balanced investment profile, combining strong subscription-led growth, expanding ARR, improving margins, and a sharp turnaround in free cash flow with ongoing profitability and execution challenges. While the business demonstrates clear operating leverage and a strengthening balance sheet, continued GAAP losses, elevated stock-based compensation, and reliance on sustaining high growth rates indicate that the company remains in a transition phase.
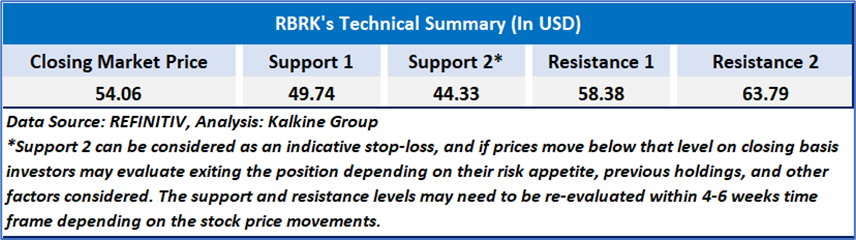
From a technical standpoint, the stock remains under pressure, trading below key moving averages with weak momentum indicators. Given the prevailing downtrend, current market volatility, and mixed risk-reward dynamics, a ‘Watch’ rating has been assigned to Rubrik, Inc (NYSE: RBRK) at the closing market price of USD 54.06 as of February 9, 2026.
Individuals may evaluate the stock based on clearly defined support and resistance levels and consider potential opportunities only if there is evidence of trend stabilization or improving momentum, while carefully weighing downside risks.
Risk Disclosures and Important Notes
Markets are currently experiencing elevated volatility due to macroeconomic uncertainties and ongoing geopolitical developments. As a result, a cautious investment approach is advisable.
This report incorporates both fundamental performance indicators and technical analysis, with greater emphasis on short-term technical signals. The assessment is intended for short-duration consideration and carries a higher-risk profile.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency figures, technical indicators, and analysis is February 9, 2026. Data has been sourced in part from REFINITIV.
Note 3: Investment decisions should be made based on an individual’s risk tolerance, investment horizon, and existing portfolio exposure.
Note 4: Target price refers to an estimated price level derived from relative valuation methods and/or technical analysis under both short-term and long-term scenarios and is subject to change.
Note 5: Kalkine reports are prepared using stock prices captured from the New York Stock Exchange (NYSE), NASDAQ, and/or REFINITIV. Price data may be subject to delays of 15–20 minutes. Information contained herein is subject to change without notice, and there is no assurance that future outcomes will align with the views expressed in this report.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...