Company Overview
Madison Air Solutions Corporation is a leading provider of mission-critical indoor air quality (IAQ) solutions, headquartered in Chicago, Illinois, with operations spanning two strategically important and complementary segments: Commercial and Residential. The company serves highly demanding environments where air quality has a direct impact on operational efficiency, regulatory compliance, human health, and productivity. Its portfolio comprises several established and respected brands, including Nortek Data Center Cooling, Nortek Air Solutions, AprilAire, and Big Ass Fans, each holding strong positions within their respective categories. For the fiscal year ended December 31, 2025, Madison Air reported net sales of USD 3.3 billion and net income of USD 124.3 million, supported by an Adjusted EBITDA margin of 26.7% and a workforce of more than 8,650 employees. The company addresses an estimated USD 40 billion North American total addressable market that is differentiated from the broader traditional HVAC sector, while its current market share of approximately 8% suggests meaningful long-term growth potential.
Initial Public Offering
The company launched its IPO on April 16th, 2026, under the ticker MAIR and sold approximately 82,692,308 shares of Class A Common Stock at USD 26.00 share. We had covered this IPO in our ‘Kalkine IPO Report’ on April 14, 2026, and had concluded that this IPO was “Attractive” given it given the financial performance of the company, use of proceeds, and associated risks.
Conclusion
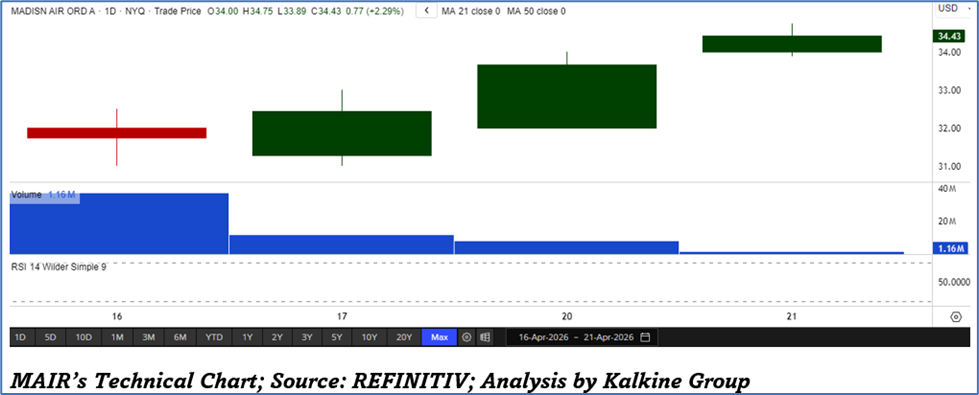
Investors who have invested in this IPO can consider ‘Exiting’ from their position at the current price of USD 34.43. as on April 21, 2026, at 10:10 am PDT, given:
- Decent gains: The stock has moved up more than ~32.42% from its IPO offering price of USD 26.00 per share.
- Leverage and Interest Burden Risks: Despite strong operating momentum, Madison Air Solutions Corporation (MAIR) is expected to remain meaningfully leveraged following the IPO, with pro forma adjusted total indebtedness of approximately USD 3,583.3 million even after applying offering proceeds toward debt reduction. The company is projected to incur annualized interest obligations of approximately USD 208.9 million, which may continue to suppress net earnings and cash flow flexibility. While deleveraging is a central objective of the transaction, the residual debt load could constrain strategic optionality, limit acquisition capacity, and heighten vulnerability during periods of weaker demand, tighter credit markets, or elevated interest rates.
- Governance and Shareholder Control Risks: MAIR’s post-listing governance structure presents a notable minority shareholder risk, as founder Larry Gies is expected to retain approximately 95.2% of total voting power through Class B shares. This concentrated control effectively allows the founder to determine board composition, major corporate actions, and strategic decisions with limited influence from public Class A shareholders. As a controlled company under NYSE standards, MAIR may also rely on exemptions from certain governance requirements, reducing independent oversight relative to widely held public peers. Such a structure may create valuation overhangs for institutional investors focused on governance alignment and shareholder rights.
- Acquisition and Cyclical Demand Risks: Madison Air has pursued an acquisition-led growth strategy, including the sizeable AprilAire transaction and recent AcoustiFLO acquisition, which introduces integration, execution, and synergy realization risks. Failure to successfully integrate acquired businesses could pressure margins, dilute returns on invested capital, or result in impairment charges over time. In parallel, portions of MAIR’s growth outlook are linked to cyclical end markets such as data centers, advanced manufacturing, construction refurbishment, and residential replacement demand, all of which can be sensitive to macroeconomic slowdowns, interest rate conditions, and reduced capital expenditure trends. This creates potential earnings volatility despite the company’s otherwise attractive long-term structural exposure.
*The reference data in this report has been partly sourced from Refinitiv.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...