Horizon Technology Finance Corporation
Horizon Technology Finance Corporation (NASDAQ: HRZN) is a specialty finance company that provides capital in the form of secured loans to venture capital-backed companies in the technology, life science, healthcare information and services, and sustainability industries. The Company's investment objective is to maximize its investment portfolio’s return by generating current income from the debt investments it makes and capital appreciation from the warrants it receives when making such debt investments.

Key Business and Financial Updates:
- Business Positioning: A Specialized Venture Lending Franchise with Sector-Focused Origination: Horizon Technology Finance Corporation (NASDAQ: HRZN), an affiliate of Monroe Capital, continues to operate as a leading specialty finance platform providing secured loans to venture capital- and private equity-backed companies, as well as select publicly traded firms. The company’s activity remains concentrated across structurally attractive innovation-led sectors, including technology, life science, healthcare information and services, and sustainability. This sector positioning enables HRZN to maintain elevated portfolio yields while pursuing credit-protected growth. During Q3 2025, management emphasized continued progress toward its strategic combination with Monroe Capital Corporation (MRCC), positioning the firm to compete for larger venture lending transactions and strengthen origination scale.
- Core Earnings Delivery: Net Investment Income Stability Supported by Higher Portfolio Yield: HRZN delivered solid core earnings for the third quarter of 2025, reporting net investment income (NII) of USD 14.0 million, equivalent to USD 0.32 per basic share, consistent with the prior-year per share outcome. Total investment income rose to USD 26.3 million (vs. USD 24.6 million in Q3 2024), primarily driven by higher fee and interest income from the debt portfolio. Notably, the company’s dollar-weighted annualized yield on average debt investments increased to 18.6% (vs. 15.9% in the prior-year period), reflecting improved yield realisation and the recognition of previously unrecorded interest income tied to settlements of two formerly non-accrual investments. Overall, the quarter demonstrated stable distributable earnings capacity and continued monetisation strength from the existing debt book.
- Portfolio Dynamics and Asset Quality: Scale Preservation with Credit Improvement Indicators: As of September 30, 2025, HRZN reported a total investment portfolio of USD 603.5 million, including a debt portfolio of 39 secured loans with aggregate fair value of USD 560.2 million, supplemented by warrant, equity, and other investments across over 100 portfolio companies. Importantly, portfolio actions during the quarter were not limited to new originations; HRZN also purchased the remaining assets of a co-lender for USD 22.5 million, with acquired assets valued at USD 36.5 million, an action described as accretive to NAV per share. From a credit standpoint, the company’s weighted average internal credit rating improved to 2.9, indicating a modest strengthening versus prior periods. While the presence of lower-rated credits remains a risk factor, management also reported constructive outcomes in two previously stressed positions, reinforcing its workout execution capability and downside management discipline.
- Liquidity, Capital Strategy, and Distributions: Strong Funding Flexibility and Income Continuity: HRZN entered the closing months of 2025 with substantial liquidity and financial flexibility. At quarter-end, the company reported USD 130.9 million in cash, with additional credit capacity supporting a total liquidity position of approximately USD 151.4 million. The balance sheet was further strengthened through capital actions including an accretive ATM issuance delivering USD 10.6 million in net proceeds and a USD 40 million convertible notes offering (5.50% due 2030), supporting capital availability for portfolio growth. HRZN also maintained an income-focused posture, declaring monthly distributions of USD 0.11 per share payable across January to March 2026 (totaling USD 0.33), underpinned by spillover income of USD 0.93 per share. While this provides near-term distribution coverage comfort, the company explicitly noted that future distribution levels will be reassessed in early 2026, incorporating operating results and potential merger impacts.
- Strategic Outlook: MRCC Merger as a Potential Catalyst for Scale, Origination Capability, and Competitive Positioning: A defining forward variable for HRZN is the proposed merger of MRCC into HRZN, subject to shareholder approvals and closing conditions. Management views the transaction as strategically important, with the combined platform expected to enhance access to larger venture lending deals and deepen alignment with Monroe Capital’s origination ecosystem. In the interim, HRZN’s committed backlog of USD 119 million and continued liquidity events from portfolio companies support a constructive operating runway. Nevertheless, investors should monitor key execution sensitivities including credit performance within lower-rated loans, capital markets dependence for growth funding, and integration risks associated with merger completion. Overall, HRZN’s Q3 2025 results reflect a yield-rich earnings profile, improved credit indicators, and a strategic pathway toward greater scale and competitive relevance within venture debt markets.
Key Company specific risks for HRZN:
- Credit Quality and Non-Accrual / Default Risk: HRZN lends primarily to venture capital- and private equity-backed companies, which inherently carry higher business-model and funding risk. A deterioration in portfolio credit—especially among internally lower-rated loans (ratings 1–2)—could lead to non-accruals, NAV erosion, and reduced net investment income, particularly if recovery outcomes are weaker than expected.
- Interest Rate and Spread Compression Risk: HRZN’s earnings are meaningfully driven by its ability to maintain high portfolio yields (18.6% reported). Any decline in base rates, tightening spreads in venture lending, or increased refinancing/prepayment activity could compress portfolio yield and reduce NII sustainability. Additionally, if funding costs rise faster than asset yields, net interest margins could weaken.
- Merger / Integration and Strategic Execution Risk (MRCC Combination): The proposed merger of MRCC into HRZN introduces execution and integration risk, including shareholder approvals, portfolio compatibility, operating integration, and potential changes in leverage, fee structure, or risk appetite. If the merger is delayed, does not close, or fails to deliver expected origination and scale benefits, HRZN’s strategic growth outlook and market positioning could weaken.
Technical Observation (on the daily chart):
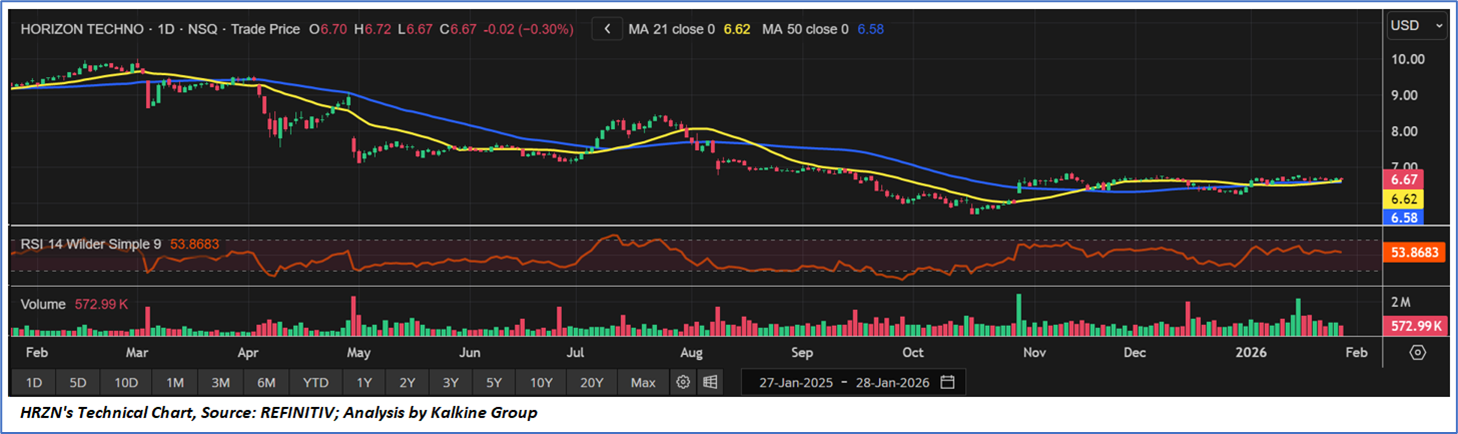
- Price Action and Structure: Range Consolidation with Base Formation: HRZN is currently displaying a compressed, range-bound structure on the daily chart after a prolonged decline earlier in the year. The stock is trading near USD ~6.67, with recent price action indicating that selling pressure has reduced and the market is attempting to form a stable consolidation base. Summary: HRZN is stabilizing, but has not yet broken out of its trading range.
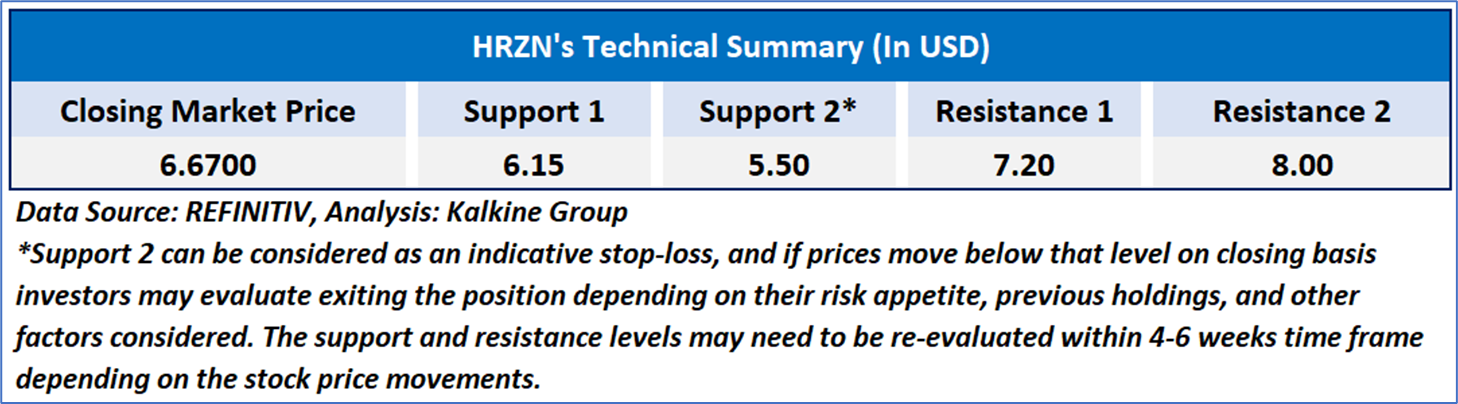
- Trend Assessment: Moving Averages Indicate Early Normalization: From a trend perspective, HRZN is trading slightly above the 21-day MA (~USD 6.62) and 50-day MA (~USD 6.58), with both averages flattening—signaling a shift from bearish conditions to a neutral-to-improving regime. A decisive breakout above USD 6.90–7.20 would be needed for stronger upside confirmation. Summary: Trend tone is improving, but confirmation requires clearing key resistance.
- Momentum Signals: Mild Positive RSI with Limited Accumulation Evidence: Momentum is moderately constructive, with the RSI (14) near ~54, marginally above the neutral level, indicating mild positive strength but not a high-conviction bullish trend. Volume remains moderate, suggesting limited institutional accumulation so far. Summary: Momentum is supportive, but a stronger rally needs higher volume and RSI expansion.
Horizon Technology Finance Corporation (NASDAQ: HRZN) is a specialty venture lending provider focused on secured loans to VC-backed companies across technology, life sciences, healthcare services, and sustainability, with returns driven by recurring interest income and warrant-linked upside. In Q3 2025, the company delivered stable core earnings with net investment income of USD 0.32 per share, supported by an elevated debt portfolio yield of 18.6%, while maintaining a sizeable USD 603.5 million investment portfolio and improved internal credit quality indicators. Liquidity remains adequate, with USD 130.9 million cash and meaningful additional borrowing capacity, enabling continued origination and portfolio activity alongside shareholder distributions of USD 0.11 per month through March 2026, supported by spillover income of USD 0.93 per share. Strategically, the proposed MRCC merger represents a potential catalyst for greater scale and origination competitiveness, although it introduces execution and integration sensitivities. From a technical standpoint, HRZN is in a stabilisation phase near USD ~6.67, with flattening moving averages and neutral momentum suggesting consolidation rather than a confirmed uptrend; overall, the profile remains balanced, with income strength and scale optionality offset by credit, rate, and merger execution risks.
As per the above-mentioned price action, important support near USD 6.00- USD 6.50, momentum in the stock over the last month, and technical indicators analysis, a ‘WATCH’ rating has been given for Horizon Technology Finance Corporation (NASDAQ: HRZN), at the closing price of USD6.67, as of January 28, 2026.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective, and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is January 28, 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...