Klarna Group Plc
Klarna Group Plc (NYSE: KLAR) is a United Kingdom-based technology company focused on developing commerce networks. The Company is an artificial intelligence (AI)-powered global payments network and shopping assistant. It provides consumers and merchants with a range of solutions, including payment, advertising and digital retail banking, through several channels.

Key Business and Financial Updates:
- Accelerating Revenue Scale Supported by Strong Consumer and Merchant Expansion: Klarna delivered a significant step-up in financial performance during Q4 2025, reporting its first billion-dollar revenue quarter at USD 1.08 billion, representing 38% year-over-year growth and exceeding management guidance . Gross Merchandise Volume (GMV) rose 32% YoY to USD 38.7 billion, while active consumers expanded 28% YoY to 118 million. Merchant reach also increased materially, with 966,000 merchants globally, including the addition of 285,000 merchants year-over-year. These metrics indicate that Klarna continues to strengthen both sides of its network, reinforcing scale advantages and distribution breadth.
- S. Market Momentum Emerging as a Key Growth Engine: The United States is increasingly becoming a strategically important contributor to Klarna’s growth profile. In Q4 2025, U.S. revenue advanced 58% YoY, accelerating from 51% in the prior quarter, while U.S. GMV increased 43% YoY . Klarna now serves 29 million U.S. consumers, with management noting that approximately 11% of the U.S. population used Klarna over the past twelve months. For investors, this demonstrates growing penetration in one of the world’s most valuable payments markets and may provide an important long-term earnings lever if adoption continues.
- Banking Product Penetration Enhancing Monetization per User: Klarna’s strategic transition beyond point-of-sale payments into broader banking products appears to be gaining traction. Consumers actively using banking-related services beyond payments rose 101% YoY to 15.8 million, and these users generate USD 107 in annual revenue per user, more than three times the base consumer population . Additionally, active Klarna Card users reached 2 million, while Fair Financing GMV grew 165% YoY in Q4, reaching 193% growth in December. This suggests that deeper engagement with existing users may drive higher lifetime value and improved monetization efficiency over time.
- Credit Quality and Capital-Light Growth Model Support Risk Management: Despite rapid growth in lending products, management reported that delinquency trends remain stable, with provision for credit losses improving to 65% of GMV in Q4 2025, down 7 basis points sequentially . Klarna also offloaded USD 1.6 billion of Fair Financing receivables during the quarter, generating a USD 73 million gain on sale. This forward-flow model enables balance sheet flexibility by transferring credit exposure to institutional investors while monetizing originated receivables, which may help sustain growth without proportionate capital intensity.
- Operational Leverage and Forward Outlook Strengthen Investment Case: Klarna continues to demonstrate meaningful operating leverage. Since Q4 2022, revenue has increased 104%, while adjusted operating expenses have declined 8%, supported by AI-enabled productivity and cost discipline . Revenue per employee reached USD 1.24 million, up 6x since 2022, while headcount declined 49%. Looking ahead, management guides for 2026 GMV above USD 155 billion, revenue exceeding 2.80% of GMV, and adjusted operating profit margins above 6.9% of revenue. For decision-making purposes, these indicators imply that Klarna is transitioning from scale-building toward a potentially more profitable monetization phase.
Key Risks for Klarna Group Plc (NYSE: KLAR):
- Execution and Development Risk in Large-Scale HPC Projects: Cipher’s strategy relies heavily on timely delivery of complex, capital-intensive hyperscale and HPC data center projects (e.g., the AWS lease and the 1-GW Colchis site); delays in construction, interconnection approvals, cooling deployment, or cost overruns could materially impact revenue realization, returns on invested capital, and customer confidence.
- Customer Concentration and Contract Dependency Risk: A growing share of Cipher’s long-term revenue visibility is tied to a small number of Tier-1 counterparties under multi-year contracts; any renegotiation, deferral, termination, or counterparty credit deterioration—particularly from hyperscalers or AI hosting partners—could have a disproportionate adverse effect on cash flows and valuation.
- Capital Structure, Funding, and Market Volatility Risk: Cipher’s expansion requires substantial upfront capital, reflected in recent convertible debt issuance and anticipated project financing; adverse movements in capital markets, higher interest rates, equity dilution, or volatility in bitcoin prices (which still influence cash generation and investor sentiment) could constrain funding flexibility and elevate balance-sheet risk.
Technical Observation (on the daily chart):
- Persistent Primary Downtrend with Early Stabilisation Signals: KLAR continues to trade within a well-defined long-term bearish structure, as evidenced by the sustained sequence of lower highs and lower lows since late 2025. Price action remains beneath both the 21-day moving average (13.41) and the 50-day moving average (15.41), confirming that the prevailing intermediate-term trend remains negative. However, the narrowing spread between spot price (13.96) and the short-term moving average, coupled with recent horizontal consolidation near multi-month lows, suggests that downside momentum may be moderating. This price compression phase often precedes either a continuation breakdown or an early-stage basing reversal, making the current zone technically consequential.
- Momentum Recovery Attempt Supported by RSI Rebound: The 14-day Relative Strength Index is currently positioned near 49.15, reflecting a notable recovery from previously subdued momentum readings. This indicates that selling pressure has materially eased, with the oscillator approaching neutral territory after spending prolonged periods below equilibrium levels. While RSI has not yet entered bullish momentum territory above 50–55, the current trajectory implies improving internal strength and the potential for a near-term sentiment shift. Should RSI establish sustained strength above the midpoint while price remains stable, it would increase the probability of a technical rebound toward overhead resistance bands.
- Key Resistance Thresholds and Tactical Breakout Framework: From a tactical perspective, immediate resistance is observed near the 21-day moving average at 13.41, followed by the more structurally significant 50-day moving average at 15.41. A decisive close above the latter would represent the first meaningful medium-term trend improvement in several months and could trigger short-covering or momentum reallocation flows. On the downside, the recent consolidation floor around the 12.80–13.00 zone remains critical support; failure to defend this range may expose the stock to renewed weakness. Accordingly, KLAR presently appears to be in a transitional technical phase where confirmation through volume-supported breakout or support failure will likely determine the next directional move.
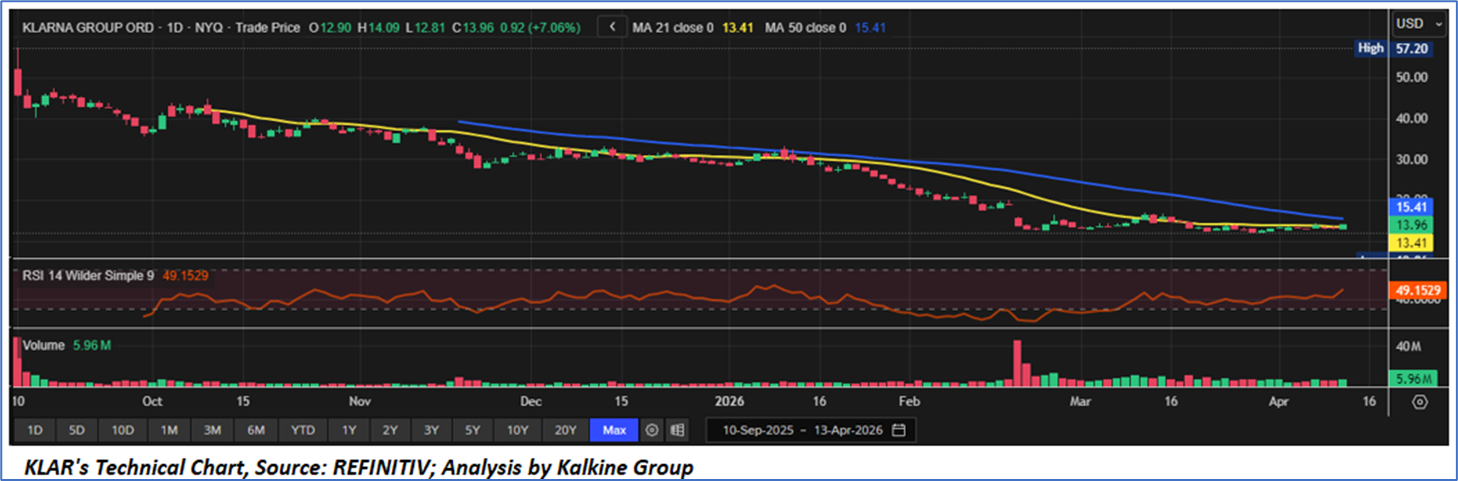

Klarna Group Plc (NYSE: KLAR) continues to demonstrate robust operational momentum, supported by strong Q4 2025 performance including revenue growth of 38% year-over-year to USD 1.08 billion, GMV expansion of 32% to USD 38.7 billion, accelerating U.S. market penetration, and increasing monetization through higher adoption of banking products such as Klarna Card and Fair Financing . The company also benefits from improving operating leverage, disciplined cost control, stable credit metrics, and a constructive 2026 outlook, indicating progress toward a more profitable scaled platform. However, execution risks linked to credit product expansion, regulatory complexity, and competitive intensity remain relevant considerations. From a technical perspective, the stock remains within a broader downtrend but is showing early stabilization signals, with RSI recovering toward neutral levels and price consolidating near support, suggesting KLAR may be entering a decisive phase where either a breakout above resistance or renewed weakness could define the next medium-term move.
As per the above-mentioned price action, important support near USD 13.00- USD 13.50, momentum in the stock over the last month, and technical indicators analysis, a ‘Speculative Buy’ rating has been given for Klarna Group Plc (NYSE: KLAR), at the closing price of USD 13.96, as of April 13, 2026.

Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective, and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is April 13, 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...