Netflix, Inc
Netflix, Inc (NASDAQ: NFLX) is a global entertainment company that provides streaming services across more than 190 countries, offering a wide range of TV series, films, and games through paid memberships. The company acquires, licenses, and produces original content, while enabling users to watch content anytime across internet-connected devices. It is expanding its platform through initiatives such as gaming, advertising, live programming, and in-house content production, supported by ongoing investments in technology and cloud infrastructure.

Result Update for the quarter ended 31 March 2026 (Q1FY26)
- Strong Revenue Growth Supported by Membership, Pricing and Advertising Momentum: The company delivered robust top-line performance during the latest quarter, with revenue rising 16% year over year to USD 12,250 million, or 14% on a foreign exchange neutral basis. Growth was primarily driven by continued expansion in paid memberships, improved pricing strategies, and a meaningful contribution from advertising revenue. Performance exceeded internal expectations, supported by stronger-than-anticipated subscriber additions and favorable currency movements net of hedging impacts.
- Operating Profitability Expands Ahead of Expectations: Operating income increased 18% year over year to approximately USD 3,957 million, reflecting improved scale efficiencies and revenue outperformance. Operating margin expanded to 32.3% compared with 31.7% in the prior-year period, indicating disciplined cost management alongside revenue growth. Both operating income and margin came in ahead of guidance, largely due to stronger revenue realization during the quarter.
- Sharp Increase in Net Income and Earnings Per Share: Net income rose significantly to USD 5,283 million from USD 2,890 million in the prior-year quarter, while diluted earnings per share increased to USD 1.23 from USD 0.66, reflecting an 86% year-over-year improvement. The strong earnings growth was driven by higher operating profits and the inclusion of a one-time USD 2.8 billion termination fee recognized under interest and other income, which materially supported bottom-line expansion.
- Engagement and Content Strategy Driving User Experience: Operationally, the company continued to enhance user engagement, with its internal engagement metric reaching an all-time high during the quarter. The content strategy remained focused on high-impact series and films, supplemented by live events, video podcasts, and gaming initiatives. Notable content releases and live programming contributed to strong viewer traction and subscriber growth across key markets, reinforcing the platform’s positioning as a primary entertainment destination.
- Technology Integration and Product Innovation Strengthen Platform: The company continued to leverage advanced technologies, including artificial intelligence, to enhance content discovery, personalization, and user experience. Strategic initiatives included the acquisition of a generative AI-focused company to empower creators, as well as ongoing enhancements to the mobile interface, including the rollout of vertical video features. These efforts are aimed at improving engagement, discovery, and overall platform efficiency.
- Monetization Initiatives Gain Traction Across Pricing and Advertising: Monetization efforts showed meaningful progress, supported by successful pricing adjustments and a rapidly scaling advertising business. The ad-supported tier continued to see strong adoption, contributing significantly to new subscriber additions. Advertising revenue remains on track to reach approximately USD 3 billion in 2026, representing a doubling from the prior year, highlighting the growing importance of this revenue stream.
- Strong Cash Flow Generation and Capital Allocation Discipline: Cash flow performance improved substantially, with operating cash flow rising to USD 5,290 million compared with USD 2,789 million in the prior-year period. Free cash flow increased to USD 5,094 million, supported in part by the termination fee inflow. The company maintained a balanced capital allocation strategy, prioritizing reinvestment in content and technology while returning capital through share repurchases, with USD 1.3 billion deployed during the quarter and significant authorization remaining.
Key Risks:
- Intensifying Competitive Landscape: Increasing competition from global streaming platforms, digital media players, and short-form content providers may impact subscriber growth and engagement
- Content Cost and Margin Pressure: Rising investments in content creation and acquisition, along with amortization timing, could weigh on operating margins
- Subscriber Growth and Pricing Sensitivity: Reliance on continued membership expansion and pricing actions exposes revenue to potential churn and consumer resistance
- Advertising and Technology Execution Risks: Challenges in scaling the advertising business and implementing AI-driven initiatives may affect monetization efficiency.
Technical Observation (on the daily chart):
- The stock appears to be transitioning from a prior downtrend into a recovery phase, forming higher lows since February and attempting to establish a short-term uptrend
- Moving Averages: Price has moved above both the 20-day moving average (97.87) and the 50-day moving average (~91.61), indicating improving momentum and a potential bullish crossover continuation
- Near-term support is placed around 98 (20-day MA), with stronger support at 92 (50-day MA). A breakdown below these could weaken the recovery structure
- RSI is elevated near 69–70, approaching overbought territory, suggesting strong momentum but also indicating a possibility of short-term consolidation or pullback
- Recent price recovery has been supported by moderate volume spikes, indicating improving buying interest, though not yet indicative of aggressive accumulation.
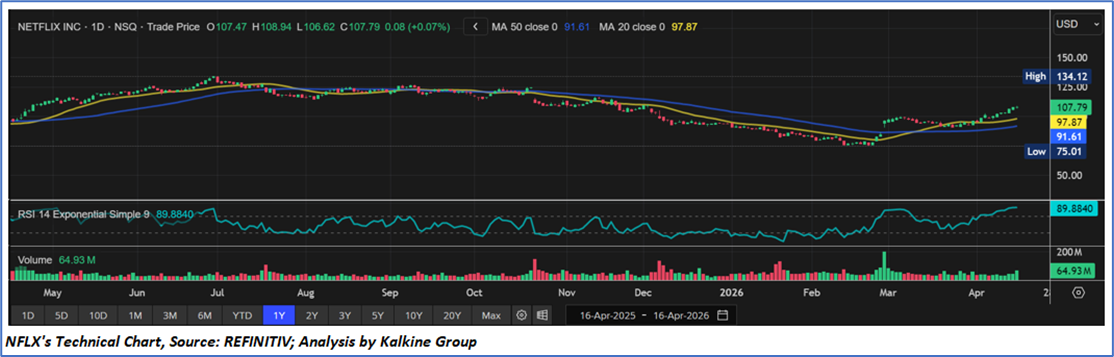
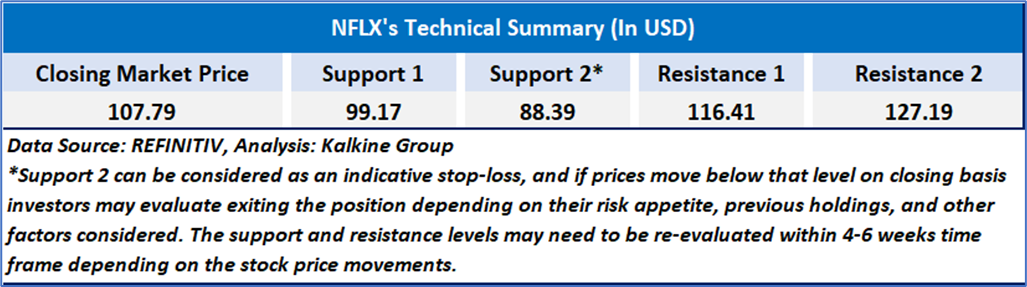
As per the above-mentioned price action, recent key business and financial updates, momentum in the stock over the last month, and technical indicators analysis, a ‘Watch’ rating has been Netflix, Inc (NASDAQ: NFLX) at the closing market price of USD 107.79 as of April 16,2026.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is April 16,2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...