Joby Aviation Inc
Joby Aviation Inc (NASDAQ: JOBY) is a transportation-focused company developing an all-electric vertical take-off and landing (eVTOL) air taxi. The company is actively engaged in the design and testing of a piloted eVTOL aircraft intended for commercial use. Joby’s aircraft is engineered to carry a pilot and up to four passengers, or an estimated payload of approximately 1,000 pounds, while achieving cruising speeds of up to 200 miles per hour.

Key Growth Aspects
- Meaningful Progress Toward Regulatory Certification: Joby Aviation has entered the final stage of the FAA Type Certification process with the commencement of power-on testing for its first FAA-conforming aircraft built for Type Inspection Authorization (TIA). This milestone reflects over a decade of collaboration with the FAA and signals convergence of aircraft design, manufacturing processes, and certification strategy into a single validated platform. The transition to TIA positions the company to begin “for-credit” flight testing with FAA pilots in 2026, materially reducing regulatory uncertainty around commercialization.
- Demonstrated Operational and Technological Maturity: The company has exhibited a high level of operational maturity through extensive real-world testing. During 2025, Joby conducted more than 600 flights alongside thousands of ground-based tests, including its first successful point-to-point flights in shared airspace between Marina and Monterey, California. In addition, regularly scheduled demonstration flights at World Expo 2025 in Osaka showcased the aircraft to hundreds of thousands of attendees, reinforcing confidence in the company’s readiness for commercial deployment.
- Scalable Manufacturing and Strategic Partnerships: Joby has made tangible progress in scaling its manufacturing footprint, producing fifteen times more type-design conforming parts than in all of 2024 and initiating propeller blade manufacturing at its Dayton, Ohio facility. Supported by its partnership with Toyota, the company has validated a modular manufacturing approach that could eventually support production of up to 500 aircraft annually. These developments strengthen Joby’s long-term ability to meet anticipated demand once certification is achieved.
- Strong Liquidity and Expanding Ecosystem: The company ended Q3 2025 with a robust liquidity position, holding USD 978.1 million in cash, cash equivalents, and marketable securities, supplemented by an additional USD 576 million raised through an equity offering in October 2025. Alongside this financial strength, Joby expanded its ecosystem through the acquisition of Blade, which transported approximately 40,000 passengers during the quarter, and by deepening its partnership with Uber to integrate Blade services into the Uber app, supporting future demand generation ahead of full commercial launch.
Growth Challenges
- Significant and Widening Net Losses: Despite operational progress, Joby continues to incur substantial financial losses. In Q3 2025, the company reported a net loss of USD 401.2 million, a sharp increase compared with the net loss recorded in the same quarter of the prior year. The deterioration was driven by higher operating losses as the organization scaled, along with large non-cash losses related to the revaluation of warrants and earn-out shares, highlighting the financial strain associated with its pre-revenue growth phase.
- High Cash Burn and Ongoing Capital Dependence: The company’s operations remain heavily cash-intensive, with estimated cash usage for full-year 2025 projected at the upper end of the USD 500–USD 540 million range. Although Joby currently maintains a strong balance sheet, its business model is still reliant on external financing to fund certification, manufacturing scale-up, and early commercial operations. This dependence exposes shareholders to dilution risk and ties long-term execution closely to capital market conditions.
- Limited Revenue Visibility and Early-Stage Commercialization: Revenue generation remains modest relative to the company’s cost base. Q3 2025 revenue totaled USD 22.6 million, largely attributable to the Blade acquisition, government-related activities, and engineering services rather than core air taxi operations. The absence of certified, large-scale passenger services underscores the early-stage nature of Joby’s commercialization and limits near-term visibility into sustainable operating revenues.
- Execution and Regulatory Risks Remain Elevated: While certification progress has been substantial, the most complex phases of testing and regulatory approval are still ahead. Any delays in FAA certification, challenges in scaling manufacturing to targeted volumes, or complications in launching operations across international markets could materially affect timelines and costs. Additionally, ambitious initiatives in autonomous and defense applications, though strategically attractive, add layers of technical and execution risk to an already complex development roadmap.
Technical Observation (on the daily chart):
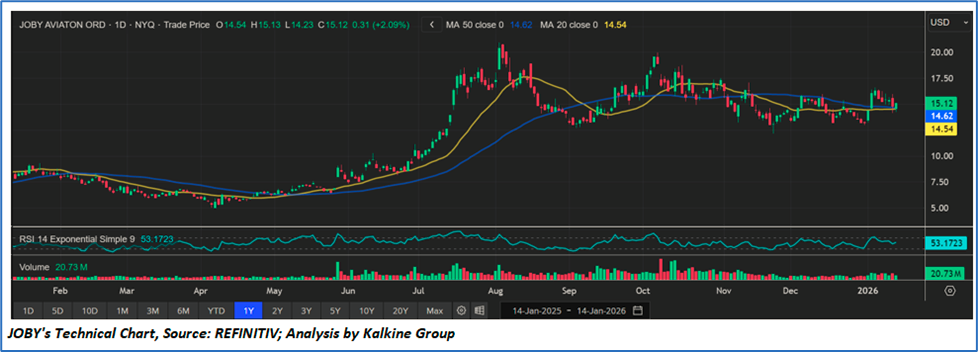
Joby Aviation’s daily chart indicates a consolidation phase following a strong mid-year rally, with the stock trading in a narrow range and hovering around its 20-day and 50-day moving averages. The flat and closely aligned moving averages, combined with an RSI near the mid-50s, point to neutral momentum and the absence of a clear directional bias. Volume remains subdued, suggesting limited conviction from either buyers or sellers. Overall, the technical setup reflects a pause or base-building phase, with the next decisive move likely to emerge from a breakout beyond the established range.
Joby Aviation presents a mixed investment rationale, combining strong strategic progress with meaningful financial and execution risks. On the positive side, the company has reached the final stage of FAA certification, demonstrated operational maturity through extensive flight testing and global demonstrations, scaled manufacturing capabilities, and maintained a strong liquidity position supported by recent capital raising and ecosystem expansion via Blade and strategic partnerships. However, these strengths are offset by substantial and widening net losses, high cash burn, limited recurring revenue from core air taxi operations, and continued dependence on timely certification and flawless execution. As a result, Joby remains a high-potential but high-risk proposition, with long-term value creation contingent on regulatory approval, successful commercialization, and disciplined capital management.
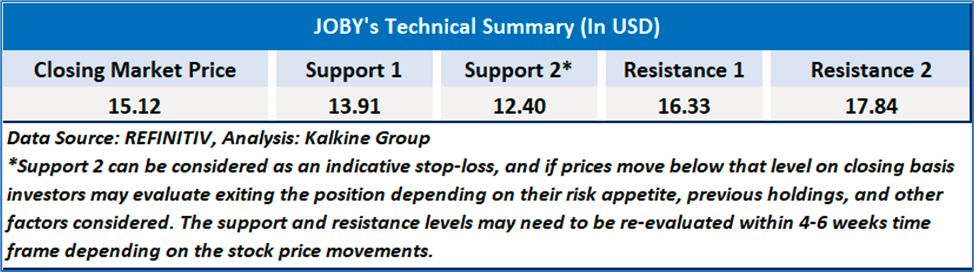
As per the above-mentioned price action, recent key business and financial updates, momentum in the stock over the last month, and technical indicators analysis, a ‘Watch’ rating has been Joby Aviation Inc (NASDAQ: JOBY) at the closing market price of USD 15.12 as of Jan 14,2026.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is January 14,2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...