LCNB Corporation
LCNB Corp. (NASDAQ: LCNB) is a financial holding company. The Company operates, through its wholly owned subsidiary, LCNB National Bank (the Bank), which serves customers and communities in Southwest and South-Central Ohio. The Bank operates over 36 offices; one branch office in Boone County, Kentucky. It offers various loan products, such as commercial and industrial loans, commercial and residential real estate loans, agricultural loans, construction loans, various types of consumer loans, and small business administration loans.
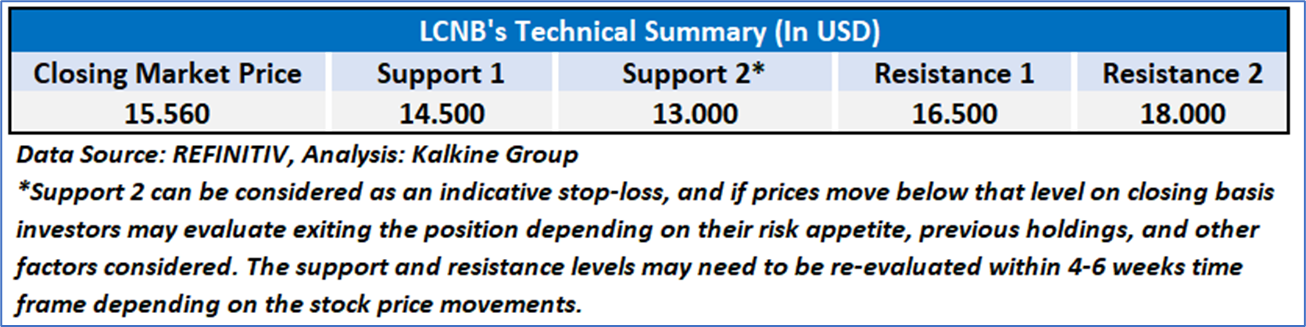
As per our previous US Dividend Income Report published on ‘LCNB’ on July 23, 2025, we provided a ‘Buy’ stance on the stock at USD 15.56 based on “solid fundamentals, consistent dividend payments of USD 0.44 per share year-to-date in 2025, stable total assets of USD 2.31 billion, improved return on average assets of 1.04% in Q2 2025, successful integration of recent acquisitions, and attractive current valuations” and the stock price has now moved up by ~8.35% since then and has attained resistance 1 and moving towards resistance 2.
Noted below are the details of support and resistance levels provided in our previous report:
Rationales For “Sell” at Current Levels:
- Premium to Tangible Book Amid Moderate Return Profile: LCNB currently trades at a valuation that appears to embed a meaningful premium over its tangible book value, which stood at USD 12.45 per share as of FY2025, reflecting a 13.6% year-over-year increase . While this improvement underscores solid capital accretion, the bank’s return on average assets of approximately 1.02% remains indicative of a steady, rather than high-growth, earnings profile. In such a context, elevated valuation multiples suggest that the market may be pricing in sustained above-trend profitability and balance sheet expansion, assumptions that may not be fully supported by the current return metrics.
- Earnings Momentum Supported by Cyclical Interest Rate Tailwinds: The bank’s earnings trajectory in FY2025 benefited materially from expansion in net interest margins, which increased to 3.50% from 2.91% in the prior year . This improvement was largely driven by favorable shifts in funding costs and asset yields, reflective of a supportive interest rate environment. However, such margin expansion is inherently cyclical and subject to normalization as monetary conditions evolve. Consequently, the sustainability of recent earnings growth may be more constrained than current valuation levels imply, particularly if rate dynamics stabilize or reverse.
- Muted Balance Sheet Growth Relative to Valuation Expectations: Despite robust profitability metrics, LCNB’s balance sheet exhibited modest contraction during the period, with total assets declining by 2.9% and net loans decreasing by 1.1% year-over-year . Additionally, deposits experienced a slight reduction, reflecting ongoing funding optimization strategies. This divergence—where earnings improve but core balance sheet growth remains subdued—suggests that the institution is not currently in a high-expansion phase. Given that premium valuations are typically supported by concurrent growth and profitability, this imbalance may indicate that market expectations are somewhat ahead of underlying growth trends.
- Emerging Indicators of Credit Cost Normalization: While overall asset quality remains sound, with nonperforming loans at low levels, the fourth quarter of FY2025 saw an increase in provisioning for credit losses to USD 1.5 million, compared to USD 0.6 million in the prior-year period . Although management has characterized this as largely attributable to an isolated exposure, it nonetheless reflects early signs of normalization in credit costs following a benign credit cycle. At current valuation levels, the market appears to be discounting a continuation of favorable credit conditions, potentially underestimating the impact of incremental provisioning on forward earnings stability.
Daily Chart
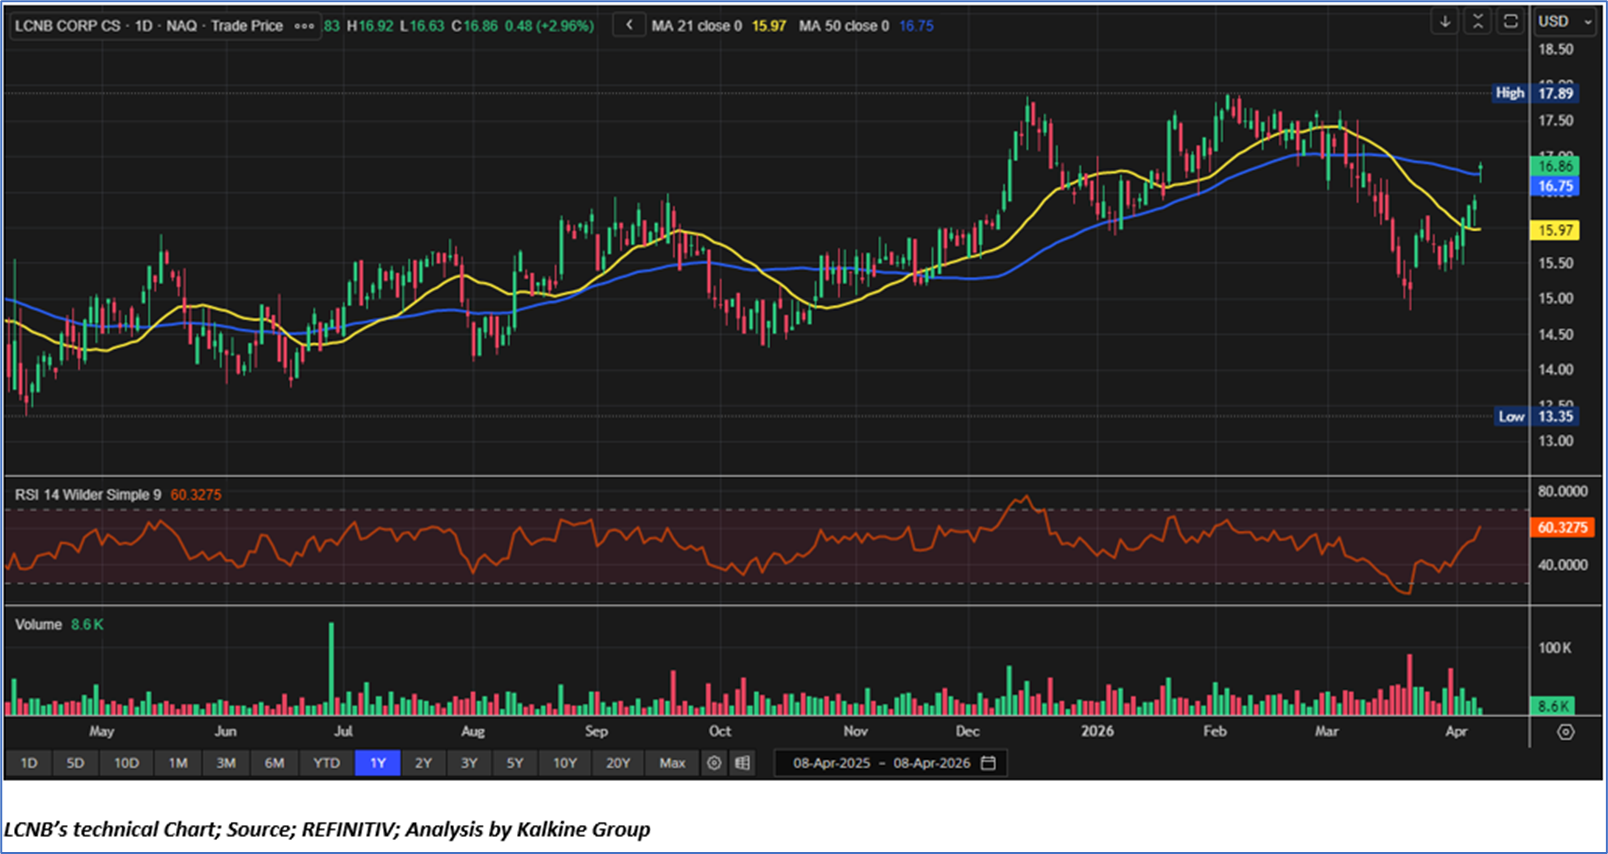
Considering the moderation in near-term earnings momentum (with quarterly net income declining year-over-year), reliance on cyclical net interest margin expansion for profitability, muted balance sheet growth reflected in declining loans and deposits, early signs of credit cost normalization with elevated provisioning, and limited visibility on sustained high returns despite stable asset quality and consistent dividend payouts, a ‘Sell’ rating is assigned to the ‘LCNB’ at the current market price of USD 16.86, as of April 08, 2026, at 7:10 am PDT.
Note: This report may be updated with details around fundamental and technical analysis, price chart in due course, as appropriate.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is April 08, 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...