
Constellation Brands, Inc.
Constellation Brands, Inc. (NYSE: STZ) operates as a global beverage alcohol company engaged in the production, marketing, and distribution of beer, wine, and spirits across the United States, Mexico, New Zealand, and Italy. The company’s portfolio includes well-known brands such as Corona Extra, Modelo Especial, Robert Mondavi Winery, Kim Crawford, The Prisoner Wine Company, High West, Casa Noble, and Mi CAMPO, and its business is organized into the Beer, Wine and Spirits, and Corporate Operations and Other segments.
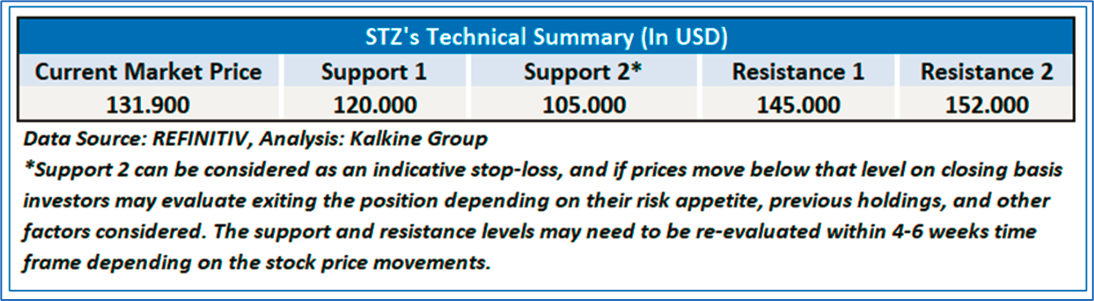
As per Global Tariff Report published on ‘STZ’ on Nov 24, 2025, Kalkine provided an ‘Buy’ stance on the stock at USD 131.9 based on fundamental analysis and the stock price has now moved up by ~ 15.34% since then.
Noted below are the details of support and resistance levels provided in our previous report:
Rationale:
- Hispanic Consumer Sensitivity Weighing on Beer Demand: Constellation Brands’ recent slowdown in beer sales is closely linked to reduced consumption among Hispanic consumers, who account for more than half of its beer customer base. Management commentary indicates that economic pressures and concerns around immigration-related issues have led to fewer social occasions where beer is typically consumed, resulting in notable volume declines for core brands, particularly in regions with higher Hispanic population concentration.
- Challenging Consumer Environment and Demand Softness: Constellation Brands continues to operate in a challenging macroeconomic environment marked by subdued consumer demand across beer, wine, and spirits categories. During the third quarter of fiscal 2026, overall enterprise dollar sales declined year over year, reflecting cautious consumer spending amid persistent inflationary pressures and elevated economic uncertainty. The weakness was particularly pronounced among Hispanic consumers, a core demographic for the company’s Beer Business, exacerbated by higher unemployment rates and slowing activity in labor-intensive sectors such as construction. These factors collectively weighed on volumes and constrained near-term demand visibility.
- Volume Declines and Margin Pressures in the Beer Business: Despite maintaining market share gains, the Beer Business experienced a contraction in volumes, with depletions declining by approximately 3% during the quarter. Shipment volumes fell by 2.2% year over year, primarily due to weaker consumption trends in key geographies with higher Hispanic population exposure. While pricing actions partially offset volume pressure, operating income still declined modestly, and margins faced headwinds from unfavorable fixed-cost absorption, higher depreciation, and increased aluminum tariff-related costs. These factors underscore the sensitivity of profitability to sustained volume softness in the company’s largest segment.
- Severe Earnings Deterioration in the Wine and Spirits Segment: The Wine and Spirits Business remained a significant drag on consolidated performance, reflecting the impact of recent divestitures and underlying structural challenges. Reported net sales in the segment declined by over 50% year over year, while operating income fell approximately 65%, resulting in a sharp contraction in operating margin from 22.1% to 15.8%. On an organic basis, profitability remained under pressure due to strategic pricing actions, changes in distributor contractual payments, and unfavorable fixed-cost absorption. Management’s outlook for fiscal 2026 points to a near-complete erosion of organic operating income in this segment, highlighting continued earnings volatility.
- Earnings Contraction and Cautious Forward Outlook: At the enterprise level, Constellation Brands reported a decline in reported operating income and a mid-teen percentage drop in reported earnings per share for the quarter. While leverage metrics remained within targeted levels, the company’s fiscal 2026 outlook signals further pressure, with expectations of declining organic net sales and lower comparable operating income. Incremental risks from tariffs, higher depreciation, and fixed-cost absorption are expected to weigh on margins in the near term, limiting earnings growth despite ongoing cost optimization initiatives and capital investments.
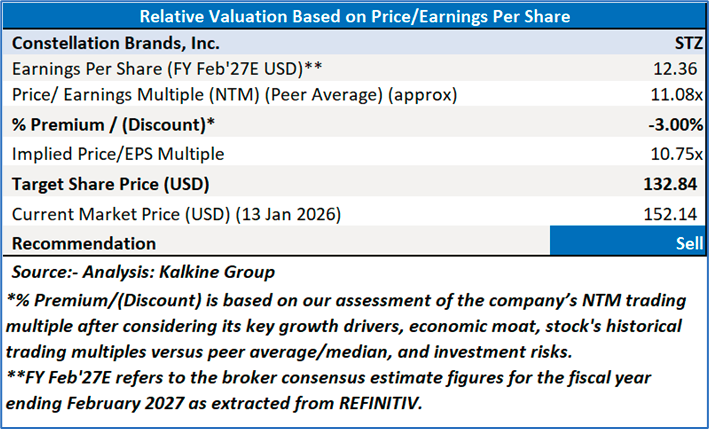
Valuation (Using Price/Earning Multiple)
Share Price Chart
Conclusion
Despite recent weakness in depletions and a sharp correction in the stock’s valuation, the company’s long-term growth narrative remains under debate. While core brands have seen volume pressure, distribution penetration remains materially below industry leaders, suggesting untapped runway. Additionally, management has observed relatively stronger demand trends in lower-Hispanic-density regions, raising expectations that comparisons could improve if current consumer headwinds stabilize.
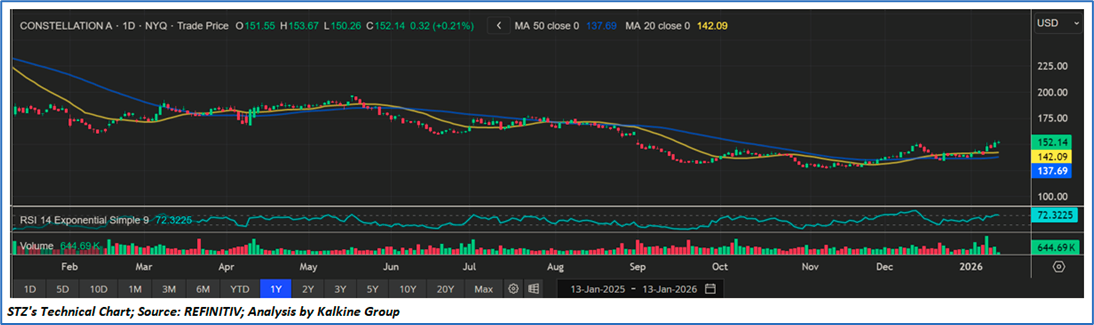
Due to ongoing softness in beer volumes driven by reduced consumption among the company’s core Hispanic consumer base, uneven regional demand trends, heightened sensitivity to macro and social factors affecting social occasions, and uncertainty around the timing of a normalization in growth, a "Sell" recommendation on Constellation Brands, Inc. (NYSE: STZ) has been given at the current market price of USD 152.14 as on 13 January 2026 at 9:05 am PST.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is 13 January 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level which the stock is expected to reach as per the relative valuation method and/or technical analysis taking into consideration both short-term and long-term scenario.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the London Stock Exchange (LSE) and or REFINITIV. Typically, both sources (LSE and or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.’
Note 6: Dividend Yield may vary as per the stock price movement.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...