
Carnival Corporation
Carnival Corporation (NYSE: CCL) is an international cruise and leisure travel operator with a diversified portfolio of well-established cruise brands, including AIDA Cruises, Carnival Cruise Line, Costa Cruises, Cunard, Holland America Line, P&O Cruises in Australia and the UK, Princess Cruises, and Seabourn.
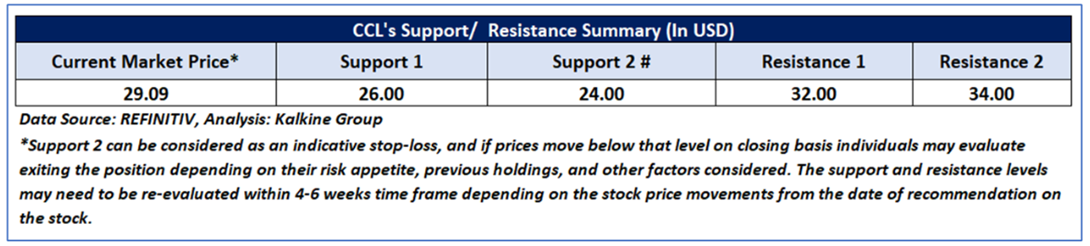
As per Global Travel and Leisure Report published on ‘CCL’ on Jul 17, 2025, Kalkine provided an ‘Buy’ stance on the stock at USD 29.09 based on fundamental analysis and the stock price has now moved up by ~ 10.45% since then.
Noted below are the details of support and resistance levels provided in our previous report:
Rationale:
- Record Financial Performance Largely Reflected in Valuation: The company delivered a record FY2025 performance, with adjusted net income of approximately USD 3.1 billion, adjusted EBITDA of USD 7.2 billion, and operating income of USD 4.5 billion, all marking multi-year highs. Net yields reached record levels, while return on invested capital exceeded 13%, the highest in nearly two decades. Given the sharp earnings recovery and margin expansion already realized, a significant portion of the fundamental turnaround appears to be embedded in the current stock price, supporting a case for booking notional gains after a strong run-up.
- Balance Sheet Repair and Investment-Grade Milestone Achieved: Carnival has materially strengthened its balance sheet, reducing net debt by over USD 10 billion from peak levels and improving net debt to adjusted EBITDA to 3.4x, resulting in an investment-grade rating from Fitch. The successful refinancing of USD 19 billion of debt and lower interest expense materially reduce financial risk. With this long-anticipated deleveraging milestone now achieved, the associated re-rating catalyst is largely realized, limiting incremental upside from balance-sheet normalization alone.
- Dividend Reinstatement Signals Maturity of Recovery Phase: The reinstatement of a quarterly dividend at USD 0.15 per share reflects management confidence in sustainable cash flows and capital discipline. While supportive for shareholder returns, dividend reinstatement also signals a transition from recovery-driven upside to a more normalized return profile. For investors who entered during the distressed or early recovery phase, this shift strengthens the rationale to lock in notional gains as the risk-reward balance becomes more symmetrical.
- Forward Growth Expectations Appear Moderated: Management guidance for FY2026 implies adjusted net income growth of around 12% on capacity growth of less than 1%, with net yield growth moderating to approximately 2.5% in constant currency. At the same time, adjusted cruise costs excluding fuel are expected to rise by over 3%. While operational momentum remains healthy, the pace of incremental improvement is normalizing compared to the outsized gains of FY2024–FY2025, suggesting more measured upside from current levels.
- Strong Bookings and Demand Already Well Telegraphed: The company has highlighted historically high booked occupancy and pricing for 2026, with roughly two-thirds of capacity already sold at elevated rates. Record booking volumes for 2026 and 2027 further underscore demand strength. However, the high visibility of these positives reduces the likelihood of positive surprises, as forward demand strength is now well understood and increasingly priced into market expectations.
- Execution and Structural Upside Priced In: Strategic initiatives such as disciplined capacity growth, fleet upgrades, exclusive destination development, and the proposed simplification of the dual-listed corporate structure enhance long-term value and liquidity. However, these initiatives are medium-term in nature and unlikely to act as immediate catalysts following the stock’s strong appreciation. With execution risks and macro sensitivities remaining, the near-term risk-reward appears balanced, reinforcing a prudent case for booking notional gains.
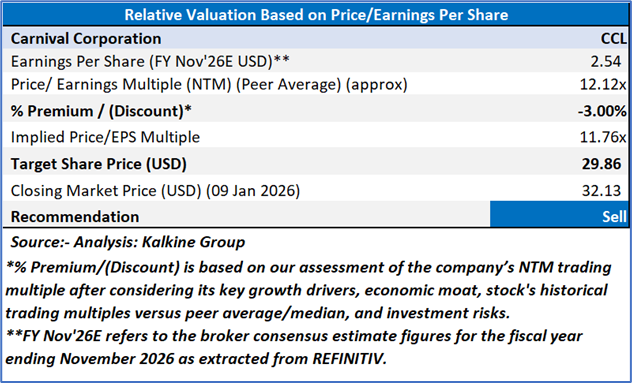
Valuation (Using P/E Multiple)
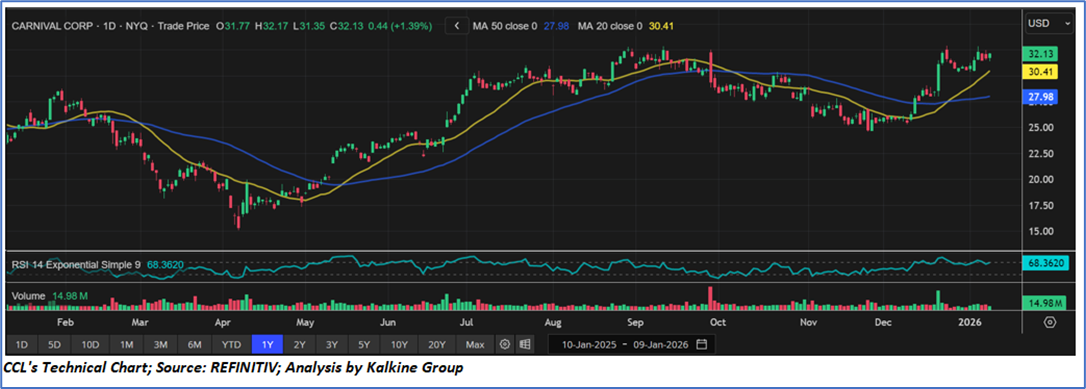
Share Price Chart
Conclusion
CCL delivered a strong re-rating following a record FY2025 performance marked by sharp earnings growth, margin expansion, and return on invested capital exceeding 13%, alongside a materially strengthened balance sheet that has achieved investment-grade leverage and enabled dividend reinstatement, all of which indicate that the recovery-driven upside is largely reflected in current valuations. While demand visibility remains robust with historically high forward bookings and pricing, FY2026 guidance points to a moderation in incremental growth amid rising operating costs and limited capacity expansion. With key catalysts such as deleveraging, refinancing, and structural improvements now largely realized and well telegraphed to the market, the near-term risk–reward appears more balanced, supporting a rationale for booking notional gains after the recent run-up.
With record earnings, balance sheet normalization, dividend reinstatement, and forward growth already well priced in, a "Sell" recommendation on Carnival Corporation (NYSE: CCL) has been given at the closing market price of USD 32.13 as on 09 January 2026.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is 09 January 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level which the stock is expected to reach as per the relative valuation method and/or technical analysis taking into consideration both short-term and long-term scenario.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the London Stock Exchange (LSE) and or REFINITIV. Typically, both sources (LSE and or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.’
Note 6: Dividend Yield may vary as per the stock price movement.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...