Devon Energy Corporation
Devon Energy Corporation (NYSE: DVN) is an oil and gas producer in the United States with a diversified multi-basin portfolio headlined by an acreage position in the Delaware Basin. The Company is primarily engaged in the exploration, development and production of oil, natural gas and natural gas liquids (NGLs). It owns a portfolio of assets located in the Delaware Basin, Rockies, Eagle Ford and Anadarko Basin.

Key Business and Financial Updates:
- Strategic Transformation Through the Proposed Coterra Energy Merger: Devon Energy Corporation outlined a transformative strategic development through its proposed merger with Coterra Energy, which management believes will significantly strengthen the company’s long-term positioning. The transaction is expected to combine complementary shale portfolios, particularly across leading U.S. basins, with the Delaware Basin anticipated to account for more than half of the combined entity’s production and cash flow. Management highlighted that the integration of overlapping operational footprints could enable efficiency improvements, infrastructure optimization, and best-practice implementation. As a result, the company expects approximately USD 1 billion in annual pre-tax run-rate synergies by 2027, reinforcing the strategic rationale for the combination.
- Strong Operational Performance and Free Cash Flow Generation: Devon reported a robust operational performance for both the fourth quarter and full year of 2025, supported by disciplined execution across its asset base. Production exceeded guidance, primarily driven by strong well performance and effective base production management. Operating costs improved during the year as reliability initiatives and operational efficiencies enhanced overall performance. Capital expenditures also finished approximately 4% below guidance, reflecting continued gains in drilling and completion efficiency. These operational improvements collectively enabled the company to generate around USD 700 million in free cash flow during the fourth quarter, demonstrating consistent operational discipline.
- Capital Efficiency and Reserve Performance Strengthen Asset Quality: Devon’s operational strategy continues to deliver strong capital efficiency and asset productivity relative to industry peers. The company reported a reserve replacement rate of 193% of production, with finding and development costs slightly above USD 6 per BOE, highlighting the strength of its multi-basin portfolio. Additionally, well productivity remains significantly above peer averages, while capital efficiency metrics outperform the industry benchmark. These factors have enabled Devon to enhance output while reducing capital intensity, reinforcing the company’s ability to generate sustainable free cash flow across commodity cycles.
- Business Optimization Program Driving Structural Cost Improvements: Devon’s business optimization program has emerged as a key driver of operational and financial improvements. Within less than a year of implementation, the company has already achieved approximately 85% of its USD 1 billion pre-tax optimization target, with the remaining savings expected to be realized during 2026. The initiative includes multiple operational improvements such as artificial intelligence-enabled production optimization, advanced analytics for drilling performance, and condition-based maintenance programs. Management indicated that more than 100 active operational workstreams are currently underway, reflecting a broader shift toward continuous efficiency improvements embedded across the organization.
- Financial Discipline, Shareholder Returns, and Strategic Investments: From a financial perspective, Devon maintained a strong balance sheet and capital return framework. The company generated USD 3.1 billion in free cash flow during 2025, enabling approximately USD 2.2 billion to be returned to shareholders through dividends, share repurchases, and debt reduction. The quarterly dividend was increased by 9% to USD 0.24 per share, and management indicated the potential for further dividend increases and expanded share repurchases following the completion of the Coterra merger. In addition to its core upstream investments, Devon has also pursued strategic opportunities such as its investment in Fervo Energy, a geothermal technology developer leveraging horizontal drilling and subsurface expertise, reflecting a broader effort to explore long-term energy transition opportunities.
Key Company specific risks for DVN:
- Commodity Price Volatility Risk: Devon Energy’s financial performance remains highly sensitive to fluctuations in crude oil, natural gas, and natural gas liquids prices. Changes in global energy demand, geopolitical developments, or supply dynamics can significantly influence realized pricing, which directly affects revenue, cash flow generation, and capital investment returns across the company’s upstream portfolio.
- Operational and Basin Concentration Risk: A substantial portion of Devon’s production and cash flow is derived from U.S. shale basins, particularly the Delaware Basin. While these assets offer strong productivity, operational disruptions, infrastructure constraints, or changes in regional regulatory frameworks could impact production volumes, operating costs, and development efficiency within these core operating areas.
- Execution and Integration Risk from Strategic Transactions: The company’s proposed merger with Coterra Energy and ongoing business optimization initiatives introduce execution risks related to integration, operational alignment, and realization of projected synergies. Delays in achieving cost efficiencies, integration challenges, or changes in capital allocation priorities could affect the expected financial benefits and long-term value creation from these strategic initiatives.
Technical Observation (on the daily chart):
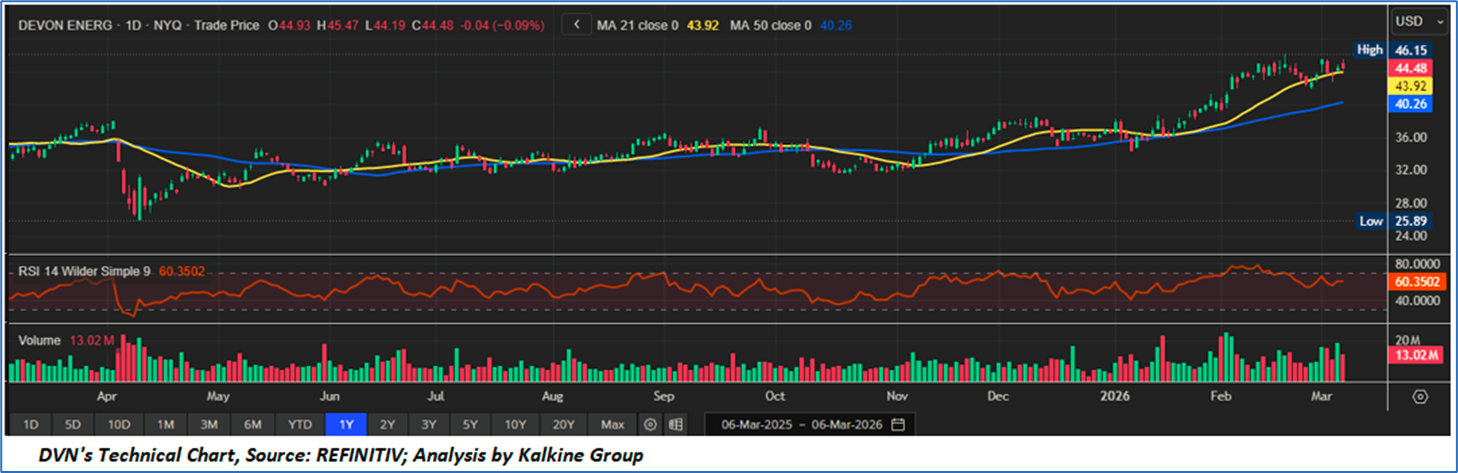
- Sustained Uptrend Supported by Moving Average Alignment: Devon Energy exhibits a constructive technical structure on the daily chart, with the stock trading around USD 44.48, comfortably above both the 21-day moving average (~USD 43.92) and the 50-day moving average (~USD 40.26). The positive slope of these moving averages indicates continued upward momentum following the recovery from mid-2025 levels. Price action has formed a sequence of higher highs and higher lows, suggesting that the broader trend remains intact and supported by consistent buying interest. This alignment typically reflects a stable medium-term bullish trend environment.
- Momentum Indicators Reflect Healthy but Controlled Strength: The Relative Strength Index (RSI) is currently positioned near 60, which signals strengthening momentum while remaining below the typical overbought threshold of 70. This placement indicates that buying pressure is present but not excessively stretched, leaving room for potential continuation without immediate technical exhaustion. Additionally, trading volumes have remained relatively stable during recent advances, implying that the upward movement is supported by sustained market participation rather than short-term speculative activity.
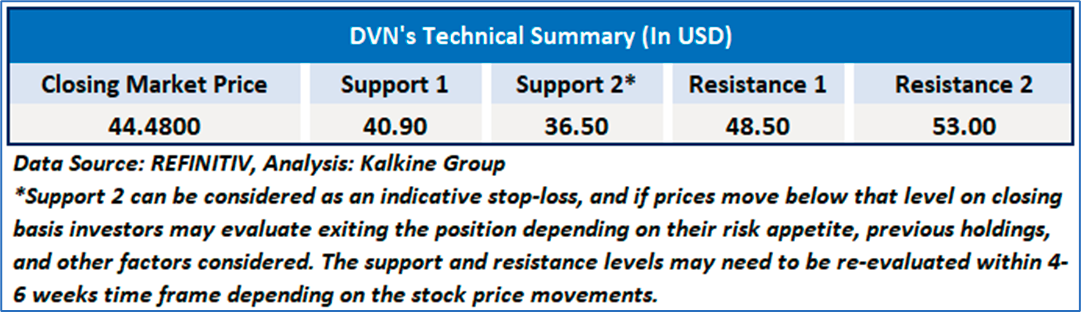
- Key Support and Resistance Levels Define the Technical Outlook: From a structural perspective, the recent high near USD 46.15 represents the immediate resistance level that the stock may need to overcome to confirm continuation of the prevailing uptrend. On the downside, the 21-day moving average (~USD 43.92) serves as the first dynamic support, followed by stronger support around the 50-day moving average (~USD 40.26). As long as price remains above these levels, the overall technical configuration suggests a stable consolidation within an ongoing upward trend, with market participants likely monitoring these support zones for signs of sustained strength or potential retracement.
Devon Energy Corporation operates a diversified U.S. shale portfolio with core assets across the Delaware Basin, Rockies, Eagle Ford, and Anadarko regions, focusing on oil, natural gas, and natural gas liquids production. The company reported solid operational performance in 2025, supported by production levels exceeding guidance, improved operating costs, and capital spending below initial estimates, which collectively enabled strong free cash flow generation. Devon’s capital efficiency and reserve performance remained robust, highlighted by a reserve replacement rate of 193% and competitive development costs, reinforcing the strength of its multi-basin asset base. The company is also advancing a business optimization program that has already achieved roughly 85% of its USD 1 billion cost improvement target through technology adoption, operational efficiency initiatives, and AI-enabled production optimization. Strategically, the proposed merger with Coterra Energy is expected to enhance scale across key U.S. shale basins and potentially generate approximately USD 1 billion in annual synergies by 2027, while Devon continues to prioritize financial discipline, shareholder returns through dividends and buybacks, and selective investments such as its stake in geothermal developer Fervo Energy. However, the company’s outlook remains influenced by commodity price volatility, basin concentration risks, and the execution of strategic initiatives, while technically the stock continues to trade within a constructive uptrend supported by key moving averages and stable market participation.
As per the above-mentioned price action, important resistance near USD 46.00- USD 48.00, momentum in the stock over the last month, and technical indicators analysis, a ‘WATCH’ rating has been given for Devon Energy Corporation (NYSE: DVN), at the closing price of USD44.48, as of March 06, 2026.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective, and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is March 06, 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...