Western Digital Corporation
Western Digital Corporation (NASDAQ: WDC) is a developer, manufacturer and provider of data storage devices and solutions. It delivers hard disk drives (HDD) solutions for everyone from students, gamers, and home offices to enterprises and public clouds. The Company manufactures, markets, and sells data storage devices and solutions in the United States and in foreign countries through its sales personnel, dealers, distributors, retailers, and subsidiaries.

Key Business and Financial Updates:
- Strong Financial Performance Driven by AI-Led Storage Demand: Western Digital reported robust financial performance in fiscal Q2 2026, reflecting strong demand for high-capacity storage solutions driven by the expansion of artificial intelligence and cloud computing. Revenue reached USD 3 billion, representing 25% year-over-year growth, while diluted earnings per share increased 78% to USD 2.13, exceeding the company’s guidance range. Profitability improved significantly, with gross margin rising to 46.1%, an increase of 770 basis points year over year and 220 basis points sequentially, supported by favorable product mix and operational efficiency. Operating income surpassed USD 1 billion, translating into an operating margin of 33.8%, underscoring the company’s ability to convert revenue growth into substantial earnings expansion amid accelerating data storage demand.
- Cloud Segment Dominance and Record Storage Shipments: The company’s growth was primarily driven by strong demand from hyperscale cloud customers. The cloud segment generated USD 2.7 billion in revenue, accounting for 89% of total revenue and growing 28% year over year. Meanwhile, the client segment contributed USD 176 million (6% of revenue) with 26% growth, while the consumer segment declined 3% to USD 168 million, reflecting weaker retail storage demand. Western Digital shipped 215 exabytes of storage during the quarter, a 22% increase year over year, including over 3.5 million ePMR drives totaling 103 exabytes. The increasing adoption of UltraSMR technology, which accounted for more than 50% of nearline drive shipments, further enhanced storage density and operational efficiency for large-scale data center customers.
- Technology Roadmap Focused on High-Capacity and Next-Generation Storage: Western Digital continues to advance its technology roadmap to support the rapidly growing storage requirements of AI workloads and cloud infrastructure. The company is accelerating the development of Heat-Assisted Magnetic Recording (HAMR) and next-generation ePMR drives, with qualification processes already underway with hyperscale customers. These technologies aim to significantly increase storage capacity while improving total cost of ownership for cloud operators. Additionally, the company launched UltraSMR-enabled JBOD platforms, enabling broader adoption of high-density storage architectures. Strategic investments in internal laser intellectual property and collaboration with Qolab on advanced nanofabrication for quantum hardware highlight Western Digital’s commitment to long-term innovation and differentiation in high-performance storage technologies.
- Operational Efficiency, Cash Generation, and Capital Allocation: Operational discipline and cost optimization remained key contributors to profitability. Operating expenses totaled USD 372 million, declining as a percentage of revenue due to improved operating leverage. The company also achieved a 10% year-over-year reduction in cost per terabyte, driven by higher capacity drives and manufacturing efficiencies. Strong cash generation was evident with operating cash flow of USD 745 million and free cash flow of USD 653 million, representing a 21.6% free cash flow margin. Western Digital returned substantial capital to shareholders, including USD 615 million in share repurchases and dividend payments during the quarter. Since the launch of its capital return program in fiscal 2025, the company has returned USD 1.4 billion to shareholders. The balance sheet remained solid with USD 2 billion in cash, USD 3.2 billion in total liquidity, and a net leverage ratio well below one turn.
- Positive Outlook Supported by Long-Term Customer Agreements: Looking ahead, Western Digital expects continued growth driven by sustained demand from hyperscale cloud providers and increasing AI-related data storage needs. For fiscal Q3 2026, the company forecasts revenue of approximately USD 3.2 billion (±USD 100 million), implying around 40% year-over-year growth at the midpoint, with gross margins expected between 47% and 48%. The company has secured firm purchase orders with its top seven customers through calendar 2026, along with long-term agreements extending to 2027 and 2028 with several major clients, providing greater revenue visibility. Management indicated that production capacity is largely committed for 2026, highlighting strong industry demand and reinforcing Western Digital’s positioning as a key supplier of high-capacity storage solutions in the AI-driven data economy.
Key Company specific risks for WDC:
- Cyclicality in the Data Storage and Semiconductor Market: Western Digital operates within the highly cyclical semiconductor and data storage industry, where demand is closely linked to broader technology spending and data center investment cycles. While the current surge in artificial intelligence and cloud computing has significantly increased demand for high-capacity storage, any slowdown in hyperscale capital expenditure or enterprise IT spending could materially impact nearline drive shipments and pricing power. Historically, the storage market has experienced sharp inventory corrections when supply outpaces demand, which can lead to rapid declines in average selling prices and profitability.
- Technology Transition and Competitive Pressure: Western Digital faces ongoing technological competition from alternative storage solutions, particularly solid-state drives (SSDs) and flash memory technologies. Although hard disk drives remain cost-effective for large-scale data storage, continued advancements in NAND flash density and declining flash costs could gradually reduce the economic advantage of HDDs in certain workloads. In addition, the successful commercialization of next-generation technologies such as Heat-Assisted Magnetic Recording (HAMR) and advanced ePMR drives is critical for maintaining competitiveness in high-capacity storage. Any delays in these technology transitions could allow competitors to gain share in hyperscale cloud storage deployments.
- Customer Concentration and Hyperscale Dependence: A substantial portion of Western Digital’s revenue is derived from a limited number of hyperscale cloud customers. In the latest quarter, the cloud segment accounted for approximately 89% of total revenue, highlighting significant exposure to large data center operators. While long-term supply agreements provide visibility, the concentration of revenue among a few major clients introduces risk related to contract renegotiations, shifts in procurement strategies, or changes in storage architecture preferences. Any reduction in demand from key hyperscale customers could have a disproportionate impact on revenue growth and capacity utilization.
Technical Observation (on the daily chart):
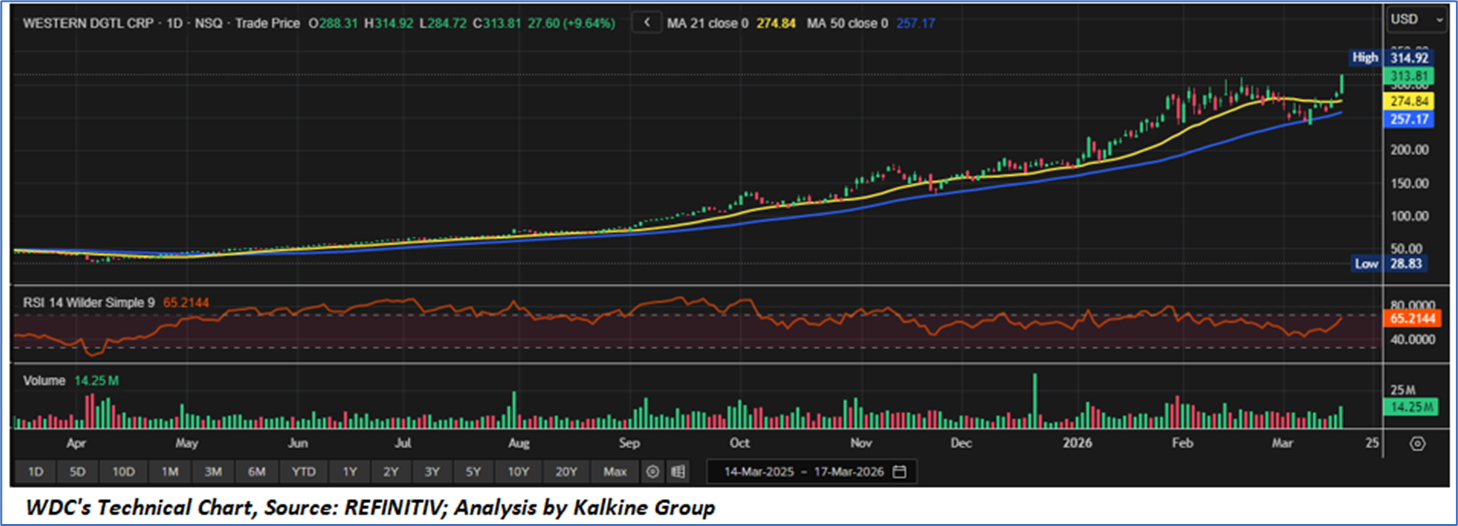
- Price Trend and Moving Average Structure: The technical structure of Western Digital Corporation (WDC) reflects a sustained bullish trend characterized by a consistent sequence of higher highs and higher lows over the past several months. The stock recently closed at approximately USD 313.81, approaching its recent high near USD 314.92, indicating strong upward momentum. Importantly, the price remains decisively above both the 21-day moving average (USD 274.84) and the 50-day moving average (USD 257.17), suggesting that the intermediate and short-term trend structures remain firmly positive. The widening gap between the current price and these moving averages highlights persistent institutional accumulation and continued strength in the prevailing upward trend.
- Momentum Indicators and Relative Strength: Momentum indicators further reinforce the constructive technical outlook. The Relative Strength Index (RSI) is currently positioned around 65, which places it in a moderately strong momentum zone without entering the overbought threshold typically associated with readings above 70. This positioning indicates that the stock retains upward momentum while still leaving room for additional price appreciation before reaching technically stretched levels. The gradual rise in RSI alongside the price trend also suggests improving market participation and sustained buying pressure rather than short-term speculative spikes.
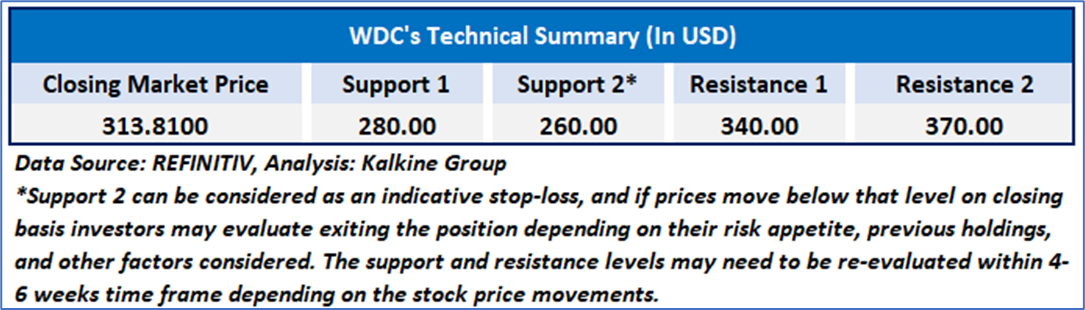
- Volume Activity and Key Technical Levels: Trading volume patterns remain supportive of the prevailing uptrend, with periodic spikes indicating renewed investor interest during price advances. The recent consolidation just below the USD 315 resistance zone suggests that the market is testing a critical breakout level. A decisive move above this resistance could potentially open the path toward higher price discovery, while the USD 274–USD 257 range, defined by the 21-day and 50-day moving averages, may serve as key technical support in the event of short-term consolidation. Overall, the chart structure indicates a technically constructive setup with strong trend support, stable momentum, and favorable positioning relative to major moving averages.
Western Digital Corporation (NASDAQ: WDC) is a global developer and provider of data storage devices and solutions, serving a wide range of customers from individual consumers to enterprise and hyperscale cloud operators. In fiscal Q2 2026, the company delivered strong financial performance driven by rising demand for high-capacity storage associated with the rapid expansion of artificial intelligence and cloud infrastructure. Revenue increased 25% year over year to USD 3 billion, while diluted earnings per share rose 78% to USD 2.13, supported by improved product mix, operational efficiency, and strong demand for nearline drives. Growth was primarily led by the cloud segment, which accounted for approximately 89% of total revenue, alongside record storage shipments and increasing adoption of higher-capacity technologies such as UltraSMR and ePMR. Western Digital continues to advance its technology roadmap through developments in HAMR and next-generation recording technologies aimed at improving storage density and cost efficiency for hyperscale customers. Strong cash flow generation, disciplined cost management, and shareholder returns through dividends and buybacks further supported financial performance, while long-term purchase agreements with major customers provide improved revenue visibility. Nevertheless, the company remains exposed to industry cyclicality, technological competition from alternative storage solutions, and a high concentration of revenue among hyperscale cloud customers. From a technical perspective, the stock exhibits a constructive trend with sustained upward momentum, trading above key moving averages and approaching a critical resistance level, suggesting continued positive market sentiment subject to broader industry and macroeconomic conditions.
As per the above-mentioned price action, important support near USD 280.00- USD 300.00, momentum in the stock over the last month, and technical indicators analysis, a ‘WATCH’ rating has been given for Western Digital Corporation (NASDAQ: WDC), at the closing price of USD 313.81, as of March 17, 2026.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective, and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is March 17, 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...