Federal Home Loan Mortgage Corporation
Federal Home Loan Mortgage Corporation (OTC: FMCC) is a government-sponsored enterprise that supports the U.S. housing market by purchasing, securitizing, and guaranteeing residential mortgage loans. It operates through Single-Family and Multifamily segments, providing liquidity to lenders, managing credit risk, and investing in mortgage-related assets while facilitating home financing and rental housing availability.

Key Growth Aspects
- Sustained Earnings and Strengthened Capital Position: Freddie Mac continued to demonstrate resilient profitability despite a challenging macroeconomic backdrop, reporting full-year net income of USD 10.7 billion and maintaining strong quarterly earnings of USD 2.8 billion. The company’s net worth increased to approximately USD 70 billion, reflecting consistent capital accumulation and balance sheet strengthening. This financial stability supports its ability to withstand market volatility while continuing to fund large-scale mortgage operations.
- Growth in Core Mortgage Portfolio and Interest Income: The company benefited from steady expansion in its mortgage portfolio, which reached over USD 3.2 trillion, driving an 8–10% increase in net interest income across periods. Lower funding costs and continued loan acquisitions further supported margin expansion. This highlights Freddie Mac’s ability to generate stable, recurring income from its core lending operations despite fluctuations in broader financial markets.
- Strong Housing Market Impact and Social Mandate Execution: Freddie Mac played a significant role in supporting housing accessibility, financing approximately 1.7 million households during 2025, with a majority of loans directed toward low- to moderate-income families. Additionally, first-time homebuyers accounted for over half of purchase loans, reinforcing its strategic importance in promoting homeownership and affordability, which remains a key policy-driven strength.
- Increased Business Activity and Operational Efficiency: New business activity showed notable improvement, rising 12% year-over-year to USD 389 billion, supported by higher refinancing volumes. Investments in technology and process optimization enhanced operational efficiency, reduced origination friction, and improved lender engagement. This positions the company to scale efficiently while maintaining competitive cost structures.
Growth Challenges
- Decline in Net Income Driven by Revenue Pressure: Despite maintaining strong absolute earnings, Freddie Mac reported a decline in profitability, with full-year net income falling by approximately 10% year-over-year. This was primarily driven by a contraction in total revenues, indicating pressure on overall earnings quality and highlighting sensitivity to market-driven income components.
- Sharp Contraction in Non-Interest Income: A significant weakness emerged in non-interest income, which declined sharply due to a shift from investment gains to losses, falling over 50% year-over-year. This volatility underscores the company’s exposure to market movements, particularly interest rate changes and spread dynamics, which can materially impact earnings outside its core lending operations.
- Rising Credit Loss Provisions and Risk Build-Up: The provision for credit losses increased substantially to USD 1.3 billion for FY2025, reflecting reserve builds across both Single-Family and Multifamily segments. This trend indicates a cautious outlook on credit quality, driven by evolving housing market conditions and potential deterioration in borrower performance.
- Weakness in Multifamily Segment Performance: The Multifamily segment exhibited notable deterioration, with net income declining 39% year-over-year and revenues falling 17%. This was primarily due to lower transaction activity, reduced securitization gains, and higher credit costs associated with strategic shifts and weaker loan performance, signaling segment-specific headwinds.
Key Risks:
- Interest Rate Sensitivity: Earnings remain exposed to fluctuations in interest rates and mortgage spreads, impacting both demand and non-interest income volatility.
- Credit Risk Exposure: Rising delinquencies or deterioration in housing market conditions could lead to higher credit losses and reserve build-ups.
- Regulatory and Government Oversight: Ongoing conservatorship and dependence on U.S. policy decisions create uncertainty around capital structure and long-term strategic flexibility.
- Housing Market Cyclicality: Slowdown in home purchases or refinancing activity could weaken loan volumes, securitization income, and overall revenue growth.
Technical Observation (on the daily chart):
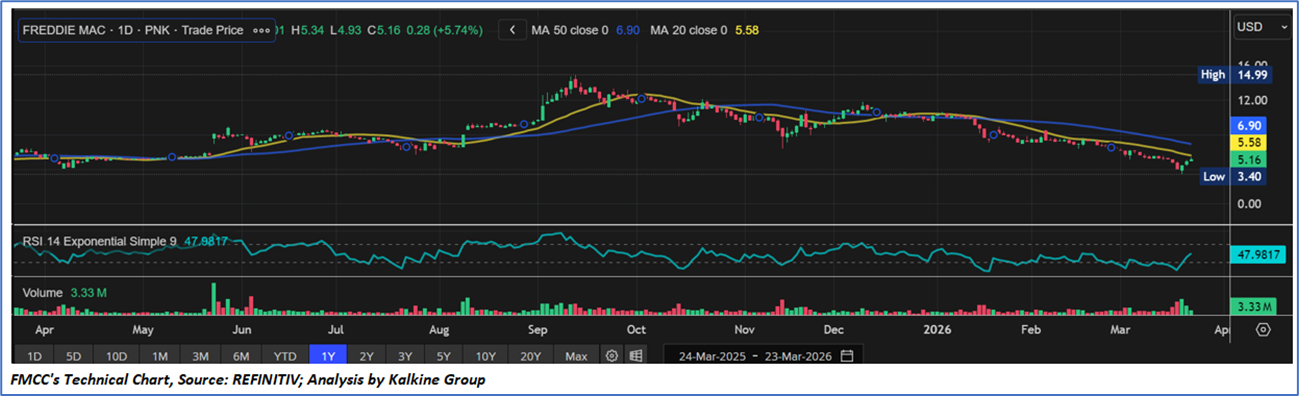
- The stock has moved from an earlier uptrend into a clear downtrend, forming lower highs and lower lows since its peak, indicating continued selling pressure.
- The price is still trading below both the 20-day (around USD 5.58) and 50-day (around USD 6.90) moving averages, reflecting a bearish trend, although recent price movement suggests a possible short-term recovery.
- RSI is near 48, indicating neutral momentum with slight improvement, suggesting the stock may be entering a consolidation phase.
- Increased trading volume near recent lows suggests some buying interest emerging after the decline.
Freddie Mac’s FY2025 performance reflects a balance between structural strength and emerging pressures, as stable earnings, a growing mortgage portfolio, and strong net interest income underscore the resilience of its core lending franchise, while its continued role in supporting housing affordability reinforces its strategic importance. However, declining net income, sharp weakness in non-interest income due to investment losses, rising credit loss provisions, and softness in the multifamily segment highlight increasing sensitivity to interest rate movements and credit conditions, suggesting a more moderated earnings outlook despite a fundamentally solid operating base.
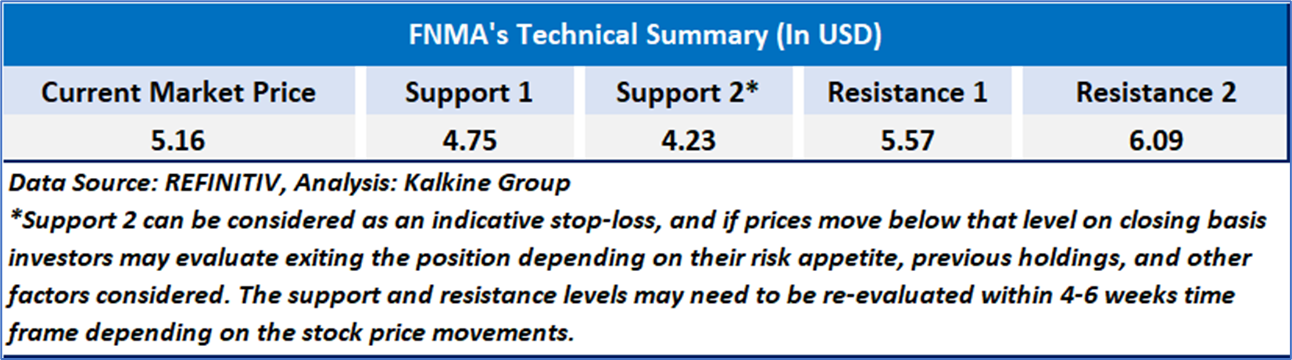
As per the above-mentioned price action, recent key business and financial updates, momentum in the stock over the last month, and technical indicators analysis, a ‘Watch’ rating has been Federal Home Loan Mortgage Corporation (OTC: FMCC) at the current market price of USD 5.16 as of March 23,2026 at 9:45 am PDT.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is March 23,2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...