Solaris Energy Infrastructure, Inc
Solaris Energy Infrastructure, Inc (NYSE: SEI) delivers mobile, scalable equipment-driven solutions supporting distributed power generation and the handling of raw materials utilized in oil and natural gas well completions. The company operates through two primary segments: Solaris Power Solutions and Solaris Logistics Solutions.

Consolidated Financial Performance
- Record Quarterly Revenue and Earnings Expansion: Solaris Energy Infrastructure, Inc. delivered record financial performance during the third quarter of 2025, reflecting strong operational execution and accelerating demand within its core markets. The company generated consolidated revenue of USD 167 million and Adjusted EBITDA of USD 68 million during the quarter. Adjusted EBITDA increased by 12% sequentially and more than tripled compared to the corresponding quarter of the prior year, underscoring the rapid scaling of the Power Solutions segment. Net income for the quarter amounted to approximately USD 24.8 million, demonstrating solid bottom-line profitability alongside expanding operating capacity.
Power Solutions Segment Performance
- Accelerated Capacity Deployment and Earnings Contribution: The Power Solutions segment remained the primary growth engine of the company. During Q3 2025, Solaris operated approximately 760 megawatts (MW) of revenue-generating capacity, representing an increase of more than 27% from the prior quarter. Segment Adjusted EBITDA for Power Solutions reached USD 58 million, reflecting a 27% sequential increase. Notably, the segment contributed more than 60% of consolidated revenue and over three-quarters of segment-level Adjusted EBITDA, highlighting its growing strategic and financial importance.
- Strategic Expansion of Generation Fleet: Solaris significantly expanded its long-term capacity outlook during the quarter. In addition to a previously announced 80 MW order, the company secured additional generation capacity totaling a pproximately 500 MW. As a result, pro forma expected generation capacity is projected to reach approximately 2.2 gigawatts (2,200 MW) by early 2028, compared to the prior plan of 1.7 gigawatts.
Capital expenditures associated with the 500 MW expansion are estimated at approximately USD 450 million, primarily relating to turbine procurement and emissions control systems. At full fleet deployment of 2,200 MW, pro forma potential Adjusted EBITDA is estimated between USD 575 million and USD 625 million attributable to Solaris, illustrating the substantial earnings leverage embedded within the company’s growth trajectory.
Logistics Solutions Segment Performance
- Stable Cash Flow and Operational Efficiency: The Logistics Solutions segment continued to provide stable cash flow and operational resilience. During Q3 2025, the segment averaged 84 fully utilized systems, reflecting an 11% sequential decline amid softer lower-48 oil and gas activity. Despite near-term industry softness, the business continues to generate significant free cash flow and remains a critical component of the natural gas value chain supporting Power Solutions.
Operational efficiency improved meaningfully, with multiple Solaris systems deployed on approximately 90% of customer locations year-to-date, compared to roughly 60% in the prior year and 40% two years ago. This increasing system density enhances throughput efficiency and reinforces Solaris’ positioning as a preferred partner in advanced completions designs.
Capital Structure Optimization and Financial Flexibility
- Convertible Financing and Balance Sheet Strengthening: During early October 2025, Solaris raised approximately USD 748 million through senior convertible notes due 2031 with a 0.25% coupon. Proceeds were used to repay the existing term loan and to fund incremental generation orders. This refinancing materially enhanced financial flexibility by removing restrictive covenants and reducing near-term financing costs.
The company expects approximately USD 45 million in combined interest and amortization savings over the next four quarters compared to the prior capital structure. Pro forma consolidated debt following the convertible issuance stands at approximately USD 975 million, with sufficient liquidity and operating cash flow generation to support ongoing capital deployment.
Strategic Initiatives and Vertical Integration
- Acquisition-Led Capability Expansion: Solaris expanded its technical and operational capabilities during the quarter through the acquisition of HVMVLV, a provider of high, medium, and low voltage distribution and regulation equipment. This transaction strengthens Solaris’ vertically integrated, power-agnostic offering and expands exposure to high-growth end markets.
The acquisition complements Solaris’ ability to provide integrated solutions including natural gas turbines, reciprocating engines, grid power, battery energy storage systems (BESS), fuel cells, and renewable technologies. By broadening its in-house engineering and distribution capabilities, the company enhances execution certainty and long-term contract competitiveness.
Outlook and Earnings Guidance
- Strengthened Forward Guidance and Growth Visibility: For Q4 2025, Solaris expects Total Adjusted EBITDA between USD 65 million and USD 70 million, increased from prior guidance of USD 58 million to USD 63 million. Additionally, the company introduced Q1 2026 Total Adjusted EBITDA guidance of USD 70 million to USD 75 million, reflecting continued ramp-up of generation capacity. Over the longer term, management estimates that pro forma earnings before additional scope or new opportunities could exceed USD 600 million at full fleet deployment. The company remains focused on delivering strong returns on invested capital in Power Solutions while maintaining market leadership and cash flow strength in Logistics Solutions.
Key Risks:
- Execution and Project Delivery Risk: Rapid expansion toward a 2.2 GW operated fleet and integration of newly acquired capabilities (e.g., HVMVLV) require precise execution; delays in turbine deliveries, commissioning, or site development could impact earnings realization.
- Customer Concentration and Data Center Demand Risk: A significant portion of growth is linked to large-scale data center and AI infrastructure projects; any slowdown in hyperscaler investment cycles or project deferrals may affect utilization and long-term contracts.
- Capital Intensity and Leverage Exposure: Ongoing fleet expansion requires substantial capital expenditure (including ~500 MW of new orders), increasing balance sheet leverage and exposing the company to refinancing, interest rate, and capital market risks.
- Commodity and Energy Market Volatility: Logistics Solutions performance remains tied to lower-48 oil and gas activity levels, while Power Solutions depends on natural gas availability and pricing, potentially affecting margins and demand stability.
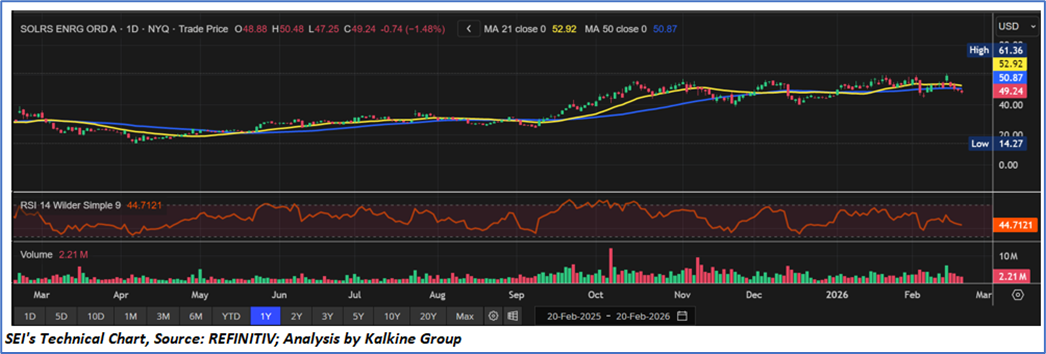
Technical Observation (on the daily chart):
- The stock rallied significantly from its prior lows near USD 14 and established a strong uptrend into late 2025, marking a high near USD 61. It is now trading around USD 49, consolidating within a broad USD 47–55 range.
- The price is currently trading below both the 21-day moving average (USD 52.92) and the 50-day moving average (USD 50.87), indicating short-term bearish pressure. The inability to sustain above these averages suggests loss of near-term momentum.
- The 14-day RSI is at 44.7, positioned below the neutral 50 level but not yet in oversold territory. This reflects weakening momentum without extreme selling pressure, leaving room for further downside if support fails.
- Volume spikes during prior upward moves indicate strong accumulation during the breakout phase. However, recent consolidation has been accompanied by moderate volume, suggesting a pause rather than aggressive distribution.
Solaris Energy Infrastructure demonstrated substantial operational scaling, strong financial performance, disciplined capital allocation, and enhanced strategic positioning during the third quarter of 2025. Record revenue and earnings, accelerated capacity expansion toward a 2.2 GW fleet, strengthened balance sheet flexibility, and continued Logistics segment cash flow collectively reinforce the company’s ability to capitalize on accelerating power demand driven by large-scale data center and artificial intelligence infrastructure investments.
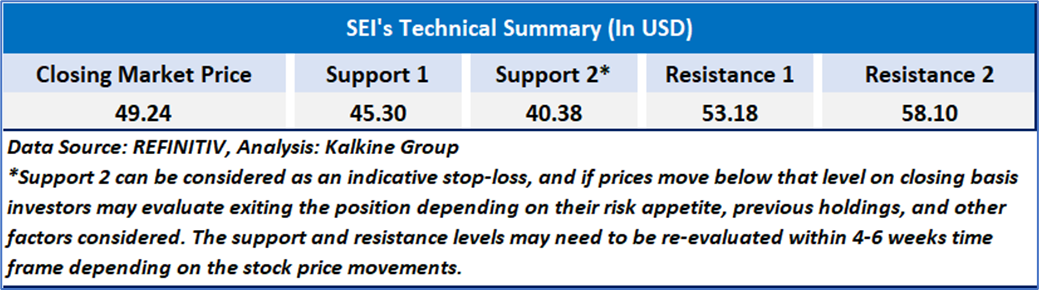
Based on above-guidance production during Q4FY25, disciplined cost management, portfolio optimization, and strengthened balance sheet, a ‘Watch’ rating has been given Solaris Energy Infrastructure, Inc (NYSE: SEI) at the closing market price of USD 49.24 as of Feb 20,2026.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective, and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is February 20,2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...