SoundHound AI Inc
SoundHound AI, Inc. (NASDAQ: SOUN) is engaged in conversational intelligence, offering voice and conversational artificial intelligence (AI) solutions that let businesses offer experiences to their customers. Through its proprietary technology, its voice AI delivers speed and accuracy in numerous languages to product creators and service providers across retail, financial services, healthcare, automotive, smart devices, and restaurants via AI-driven products, such as Smart Answering, Smart Ordering, Dynamic Drive Thru, and Amelia AI Agents.

Key Business and Financial Updates:
- Strategic Context: SoundHound’s Role in Enterprise-Scale Conversational AI: SoundHound AI, Inc. (Nasdaq: SOUN) reported its third-quarter 2025 financial results reflecting accelerating commercial traction across global enterprise markets. As a specialist in voice and conversational AI, the company is expanding deployments across millions of endpoints, with increasing relevance across diversified industries. Management highlighted that enterprise AI adoption is strengthening materially, positioning SoundHound to benefit from sustained demand for natural language interfaces and AI-enabled workflow orchestration. The company’s strategic posture continues to center on scaling its voice AI platform while building leadership in agentic AI through its Agentic+ framework.
- Q3 2025 Financial Performance: Record Revenue Growth with Margin Transparency: SoundHound delivered a record third quarter with revenue of USD 42.0 million, representing a 68% year-over-year increase. Profitability metrics reflected a mixed GAAP versus non-GAAP picture: GAAP gross margin was 42.6%, while non-GAAP gross margin was 59.3%, indicating strong underlying unit economics when excluding non-operating impacts. The company reported a GAAP net loss of USD 109.3 million, compared to a non-GAAP net loss of USD 13.0 million, with the variance largely attributable to the mark-to-market treatment of contingent acquisition liabilities tied to earnout structures. On an earnings basis, GAAP EPS was a loss of USD 0.27, while non-GAAP EPS was a loss of USD 0.03. Adjusted EBITDA remained negative at (USD 14.5) million, though it showed modest improvement versus the comparable period.
- Platform and Product Advancements: Acceleration of Agentic AI and Voice Commerce: During the quarter, SoundHound advanced its product roadmap materially, most notably through the Amelia 7.3 update, which incorporated Speech-to-Meaning® to improve latency performance and deliver more natural user interactions. This enhancement further strengthens the company’s Agentic+ framework, combining generative AI, autonomous multi-agent orchestration, and deterministic models. In voice commerce, SoundHound expanded its in-vehicle monetization capabilities beyond voice ordering to include restaurant reservations and parking payments, with several global OEMs engaged for launches expected in 2026. In addition, the company secured significant traction in IoT and robotics through a large deal to integrate SoundHound Chat AI into a minimum commitment of double-digit millions of AI-enabled smart devices from a China-based customer.
- Commercial Execution: Deepening Penetration Across High-Value Verticals: SoundHound expanded and renewed relationships across multiple verticals, reflecting both diversification and increased enterprise adoption. In automotive, the company progressed deployments with major global brands, including expanded availability of its flagship Chat AI voice technology in Jeep vehicles across Europe, growing engagement with Togg in Germany, and new agreements with commercial fleet and two-wheeler manufacturers (including India). In financial services, multiple top global institutions increased enterprise service purchases and renewed contracts, complemented by a new agreement supporting U.S. credit unions. Healthcare and insurance also saw notable progress through deployments and renewals, including contact-center modernization with agentic AI. Restaurants remained a meaningful scale driver, with deployments and franchise wins across multiple nationally recognized chains and full-rollout expansions across major brands. Additional momentum was recorded in retail, IT services, energy, telecommunications, and channel partnerships—most notably through a strategic agreement with Telarus to expand Amelia 7 and Autonomics distribution across enterprise CX and EX ecosystems.
- Financial Strength and Forward Outlook: Liquidity Supported Growth with Raised Guidance: SoundHound ended Q3 2025 with a strong liquidity profile, reporting USD 269 million in cash and cash equivalents and no debt, providing strategic flexibility to invest aggressively in platform development and commercial scaling. Over the first nine months of 2025, operating cash outflows remained broadly stable year-on-year, while financing inflows expanded, strengthening the overall cash position. Reflecting confidence in sustained demand and execution momentum, SoundHound raised its full-year 2025 revenue outlook and now expects revenue in the range of USD 165 million to USD 180 million, reinforcing management’s view that the company is entering a higher growth phase driven by multi-vertical adoption of conversational and agentic AI solutions.
Key Company specific risks for SOUN:
- Profitability and Cash Burn Risk: Despite strong revenue growth, SOUN remains loss-making, with negative Adjusted EBITDA and significant GAAP losses (partly impacted by non-cash items). The key risk is that the company may continue burning cash for an extended period, requiring sustained financing access and limiting valuation support during risk-off markets.
- Execution and Scalability Risk Across Multiple Verticals: SoundHound operates across many end-markets (automotive, restaurants, IoT, financial services, healthcare, etc.). While diversification is positive, it increases complexity. A key risk is delays in deployments, weak conversion of pilots into scaled rollouts, or inability to meet enterprise-grade reliability and latency requirements, which could slow growth and damage credibility.
- Competitive and Platform Substitution Risk: Conversational AI and agentic AI are highly competitive spaces, with pressure from large ecosystem players (Big Tech, hyperscalers, and LLM platform providers). There is a risk that enterprise customers may shift to bundled AI stacks (cloud + voice + AI agents), reducing SOUN’s differentiation and pricing power, particularly if competitors offer integrated solutions at lower marginal cost.
Technical Observation (on the daily chart):
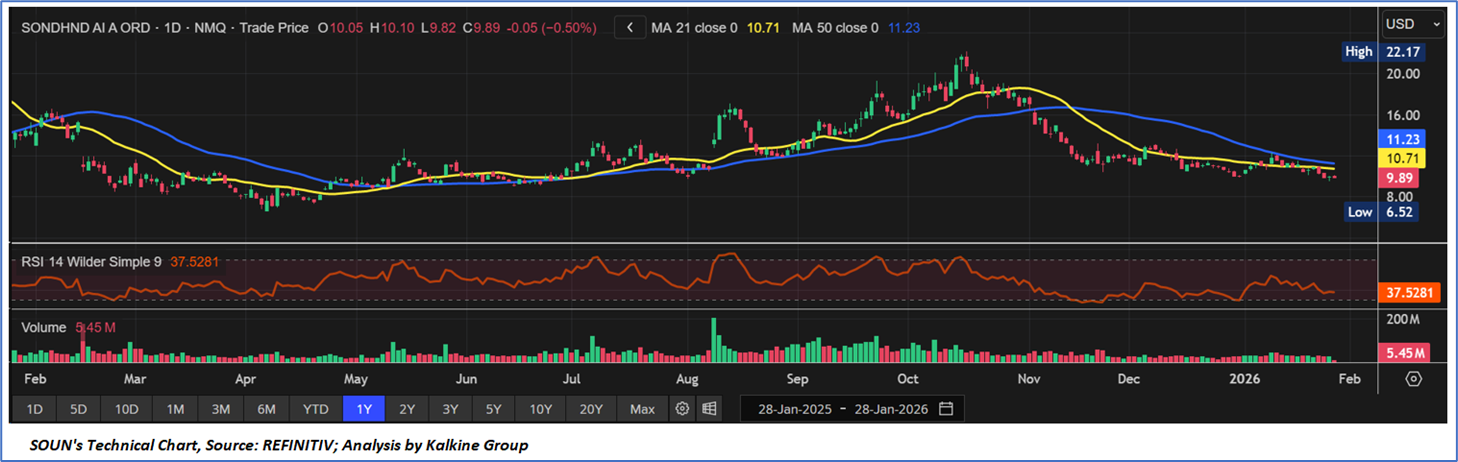
- Price Structure and Trend Direction: Post-Peak Correction Dominates: SOUN is currently in a corrective phase after reversing sharply from its prior high near USD 22.17. The stock has shifted into a lower-high / lower-low pattern, indicating that bullish momentum has weakened and the price is now consolidating closer to USD ~9.89. In summary, the chart reflects a clear loss of trend strength after the October peak.
- Moving Average Positioning: Bearish-to-Neutral Regime with Overhead Resistance: The stock is trading below both the 21-day MA (~USD 10.71) and 50-day MA (~USD 11.23), with these averages flattening or turning down—typically signalling a bearish-to-neutral technical regime. The 50-day MA is acting as key overhead resistance and reclaiming USD 11–12 is necessary for trend improvement. In summary, price action remains capped unless SOUN decisively regains key moving averages.
- Momentum and Confirmation Signals: Weak RSI Suggests Limited Upside Conviction: Momentum remains soft, with the RSI (14) near ~37.53, staying below the neutral 50 mark and reflecting continued selling pressure. While not extremely oversold, the RSI suggests limited bullish conviction unless momentum improves materially. In summary, SOUN appears in an early bottoming attempt, but confirmation requires RSI recovery and stronger breakout volume.

SoundHound AI, Inc. (NASDAQ: SOUN) is strengthening its position as a specialized leader in conversational and voice AI, supported by expanding enterprise adoption across diversified end markets including automotive, restaurants, financial services, healthcare, IoT and smart devices. The company delivered a record Q3 2025 revenue of USD 42.0 million (+68% YoY) and raised its full-year 2025 revenue outlook to USD 165–180 million, reinforcing accelerating commercial traction and increasing confidence in medium-term demand. Strategic progress remains anchored in the expansion of the Agentic+ framework and product enhancements such as Amelia 7.3 (Speech-to-Meaning®), alongside growing voice commerce opportunities targeted for broader OEM launches in 2026, while its balance sheet remains robust with USD 269 million cash and no debt. Although the investment profile continues to carry key risks—most notably ongoing losses/cash burn, execution complexity across multiple verticals, and competitive substitution risk from bundled AI stacks—the current setup remains moderately constructive as the stock appears to be forming an early base; a sustained move above USD 11–12 with improving momentum would materially strengthen the bullish technical case.
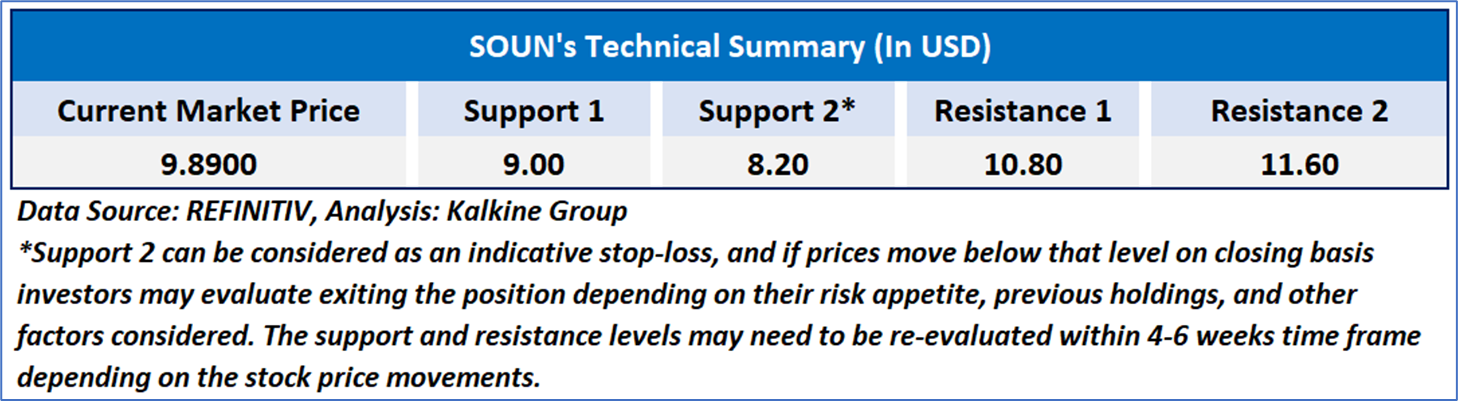
As per the above-mentioned price action, important support around USD 9.50- USD10.00, momentum in the stock over the last month, and technical indicators analysis, a ‘Speculative Buy’ rating has been given for SoundHound AI, Inc. (NASDAQ: SOUN), at the current price of USD9.89, as of January 28, 2026, 07:10 am PST.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective, and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is January 28, 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...