Sprinklr Inc
Sprinklr, Inc. (NYSE: CXM) is an enterprise software provider focused on customer-facing operations. Its AI-powered Unified Customer Experience Management (Unified-CXM) platform helps service, marketing, and other front-office teams work seamlessly across organizational silos, engage customers across digital channels, and apply AI-driven insights to enhance the overall customer experience.
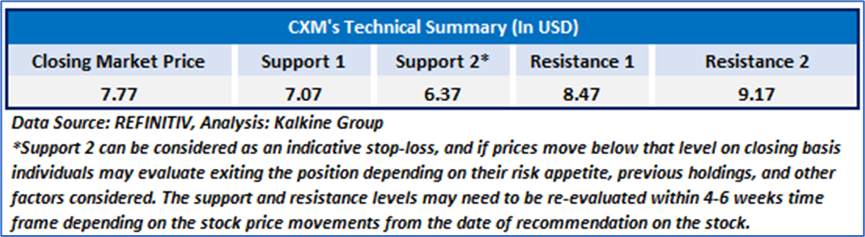
As per our previous US Diversified Opportunities Report published on ‘CXM’ on December 04, 2025, we provided a ‘Buy’ stance on the stock at USD 7.77 based on “consistent revenue growth, margin expansion, and robust operating cash flow generation, supported by strong enterprise adoption of its AI-driven Unified-CXM platform. Its improvements in operating efficiency, durable subscription business model, and recognized leadership across customer-experience categories position the company favorably for sustained long-term value creation. Henceforth, based on potential valuation upside, trading levels, and company's improving performance in the third quarter”.
Noted below are the details of support and resistance levels provided in our previous report:
Rationales For “Sell” at Current Levels:
- Moderation in Growth Trajectory and Subscription Momentum: Sprinklr reported relatively modest revenue growth of 9% year-over-year in Q4 FY2026, with subscription revenue—the core driver—expanding at an even slower pace of 6%. This deceleration highlights a moderation in demand momentum and raises concerns regarding the company’s ability to sustain high-growth SaaS characteristics in an increasingly competitive and mature market environment.
- Earnings Quality Concerns Amid GAAP Profitability Weakness: Despite improvements in non-GAAP metrics, GAAP profitability remains subdued, with diluted earnings per share declining sharply year-over-year in the fourth quarter. The divergence between GAAP and non-GAAP performance raises concerns regarding earnings quality, cost structure sustainability, and the extent of adjustments required to present underlying profitability.
- Stagnation in Remaining Performance Obligations (RPO): The company reported largely flat RPO and marginal growth in RPO, indicating limited expansion in future contracted revenue visibility. This stagnation suggests potential challenges in pipeline conversion, deal expansion, or new customer acquisition, which may constrain forward revenue growth and reduce confidence in medium-term demand sustainability.
- Margin Expansion Potential Constrained by Investment Needs: While operating margins have improved, the need for continued investment in innovation, sales execution, and platform capabilities may limit further margin expansion. As the company progresses through its transformation phase, sustaining profitability gains without compromising growth initiatives remains a key execution challenge.
- Macro Sensitivity and Execution Risks in Transformation Phase: Management has indicated caution in light of evolving macroeconomic conditions, underscoring exposure to enterprise spending cycles and potential delays in customer decision-making. Additionally, ongoing transformation initiatives introduce execution risks, particularly in aligning product innovation, go-to-market strategies, and customer engagement models, which may impact near-term performance stability.
Daily Chart
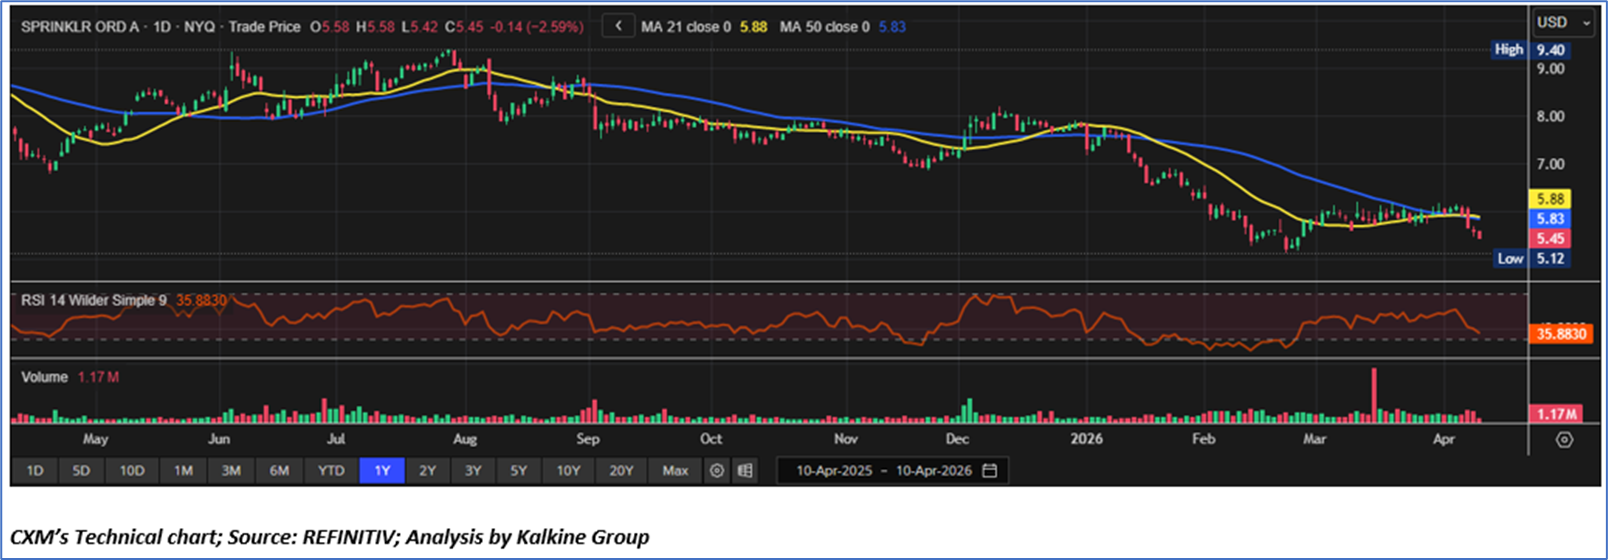
Considering the moderation in revenue growth (with subscription revenue expansion lagging overall growth), weakening earnings quality reflected in a sharp decline in GAAP earnings per share, stagnation in remaining performance obligations indicating limited forward revenue visibility, constrained margin expansion amid ongoing investment requirements, and elevated execution risks associated with its ongoing transformation in a macro-sensitive enterprise spending environment, a ‘Sell’ rating is assigned to the ‘CXM’ at the current market price of USD 5.45, as of April 10, 2026, at 07:50 am PDT.
Note: This report may be updated with details around fundamental and technical analysis, price chart in due course, as appropriate.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is April 10, 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...