Alphabet Inc
Alphabet Inc (NASDAQ: GOOGL) operates as a diversified holding company with three primary business segments: Google Services, Google Cloud, and Other Bets. Google Services encompasses a broad portfolio of consumer-facing products and platforms, including digital advertising, Android, Chrome, hardware devices, Google Maps, Google Play, Search, and YouTube. Meanwhile, Google Cloud delivers enterprise-focused solutions such as cloud infrastructure, platform services, productivity and collaboration tools, along with other technology services tailored for business customers.

Fiscal Year 2025 Results for the year ended December 31, 2025
- Strong Revenue Momentum Drives Record Annual Performance: Alphabet Inc. delivered a robust close to fiscal year 2025, with consolidated revenues rising 18% year over year in the fourth quarter to USD 113.8 billion, while full-year revenues increased 15% to USD 402.8 billion, marking the first time the Company surpassed the USD 400 billion annual revenue threshold. This growth reflected sustained strength across Google Services and a sharp acceleration within Google Cloud, supported by expanding AI-driven product adoption and resilient advertising demand. The Company also achieved 17% constant currency growth in the quarter, underscoring solid underlying operational momentum.
- Core Google Services Continue to Anchor Profitability: Google Services remained the primary revenue engine, generating USD 95.9 billion in Q4 2025, representing a 14% year-over-year increase. Search and related advertising revenues expanded 17%, demonstrating continued user engagement and advertiser demand, while YouTube advertising posted 9% growth despite a competitive digital ad landscape. Subscription-based revenues across platforms and devices rose 17%, driven by rising adoption of YouTube Premium and Google One, contributing to a growing base of over 325 million paid consumer subscriptions. This segment also delivered a notable operating margin expansion to approximately 42%, reinforcing its role as Alphabet’s profit backbone.
- Google Cloud Emerges as a High-Growth Profit Contributor: Google Cloud recorded exceptional performance, with quarterly revenues surging 48% year over year to USD 17.7 billion, supported by accelerating demand for enterprise AI infrastructure, generative AI solutions, and core cloud services. The segment achieved a meaningful improvement in profitability, with operating income rising to USD 5.3 billion and operating margins expanding to roughly 30%, compared to 17.5% in the prior-year period. Cloud’s annualized revenue run rate surpassed USD 70 billion, signaling Alphabet’s increasing competitiveness within enterprise technology markets.
- Operating Profit Expands Despite Heavy AI Investment: Alphabet’s consolidated operating income increased 16% year over year in Q4 2025 to USD 35.9 billion, while full-year operating profit rose to USD 129.0 billion. Operating margins remained resilient at approximately 31.6% for the quarter and 32% for the full year, even as the Company sharply increased investments in research, AI infrastructure, and shared technology platforms. Research and development spending rose over 40% year over year in the quarter, reflecting Alphabet’s strategic focus on scaling proprietary AI models such as Gemini.
- Earnings Growth Accelerates Through Operating Leverage: Net income for the fourth quarter climbed 30% year over year to USD 34.5 billion, while diluted earnings per share rose 31% to USD 2.82. For the full year, Alphabet generated USD 132.2 billion in net income, representing a 32% annual increase. These gains were supported by strong revenue expansion, improving segment profitability—particularly within Cloud—and favorable contributions from investment-related income. The Company’s ability to scale profits while absorbing higher operating costs highlights effective cost discipline and growing operating leverage across its platforms.
- Cash Generation Remains Robust Amid Rising Capital Expenditures: Alphabet continued to produce substantial operating cash flows, generating USD 164.7 billion for the full year 2025. Trailing twelve-month free cash flow remained solid at approximately USD 73.3 billion, despite a sharp rise in capital expenditures driven by data center expansion and AI infrastructure investments. Quarterly capital spending nearly doubled year over year to USD 27.9 billion by Q4 2025, reflecting the Company’s aggressive push to meet rising demand for cloud computing and artificial intelligence capabilities.
- Strategic AI Expansion Shapes Long-Term Growth Trajectory: Operationally, Alphabet made significant progress in scaling its AI ecosystem, with Gemini models now processing over 10 billion tokens per minute via enterprise API usage and the Gemini application reaching more than 750 million monthly active users. These advances directly supported higher engagement across Search, YouTube, and Cloud platforms. Management signaled continued acceleration in infrastructure investment for 2026, projecting capital expenditures between USD 175 billion and USD 185 billion, underscoring Alphabet’s long-term commitment to AI leadership as a central growth driver across its businesses.
Key Risks:
- Heavy dependence on digital advertising revenues exposes Alphabet to economic slowdowns and shifts in advertiser spending behavior.
- Rapidly rising capital expenditures for AI infrastructure and data centers could pressure free cash flow and returns if demand growth moderates.
- Intensifying competition in cloud computing and generative AI from hyperscalers and specialized providers may impact pricing power and margins.
- Ongoing regulatory scrutiny and antitrust actions across major markets could constrain business practices, acquisitions, and monetization strategies.
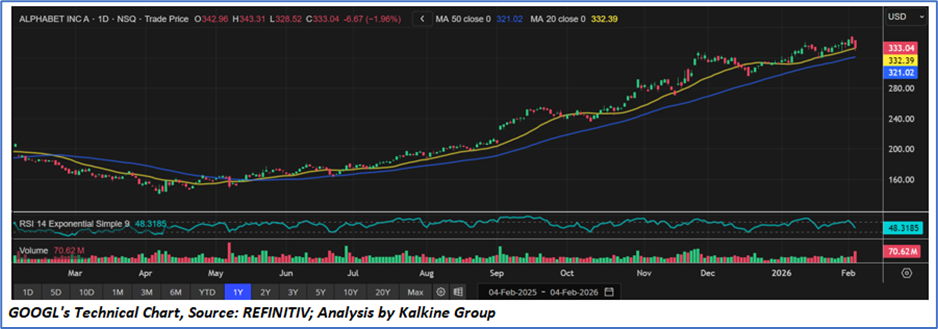
Technical Observation (on the daily chart):
- The stock remains in a strong primary uptrend, marked by a steady pattern of higher highs and higher lows over recent months.
- Price continues to trade above both the 20-day and 50-day moving averages, with the shorter-term average leading higher; a classic bullish trend signal.
- Recent sideways movement near highs reflects healthy consolidation rather than weakness, indicating controlled profit-taking.
- The 20-day moving average is acting as immediate dynamic support, while the 50-day moving average provides a solid medium-term support base.
- RSI is positioned in the neutral zone around 45–50, showing balanced momentum and no overbought conditions.
- Trading volumes remain steady, suggesting the absence of strong selling pressure or distribution.
Conclusion
Alphabet delivered a strong close to fiscal year 2025, with fourth-quarter revenues rising 18% year over year to USD 113.8 billion and full-year revenues increasing 15% to USD 402.8 billion, marking its first year above the USD 400 billion milestone. Growth was driven by resilient Google Services advertising performance and a sharp acceleration in Google Cloud, which posted 48% quarterly revenue growth and meaningful margin expansion as enterprise AI demand surged. Operating income increased 16% in Q4 and reached USD 129.0 billion for the full year, while net income climbed 30% in the quarter and 32% annually, reflecting improving operating leverage despite higher AI investments. Strong cash generation continued alongside elevated capital expenditures aimed at scaling AI and cloud infrastructure, positioning Alphabet for sustained long-term growth.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is February 04,2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 NZ
 UK
 US
 AU
 IND

 CA

 Please wait processing your request...