
 NZ
 UK
 US
 AU
 IND

 CA

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
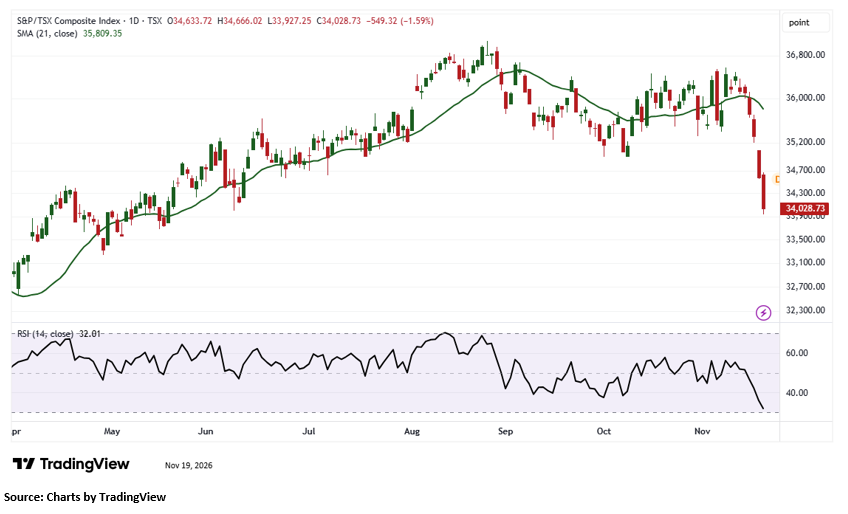
The S&P/TSX Composite index is expected to open lower, weighed down by weakness across the basic materials and industrials sectors. From a technical perspective, the index continues to trade below its 21-day Simple Moving Average (SMA), which is acting as a key dynamic resistance level and restricting recovery attempts. Immediate support is positioned near 33,600, while resistance is placed around 34,400. A sustained hold above support could help stabilise market sentiment, attract renewed buying interest and support a recovery towards the resistance level of 34,400. However, a decisive break below 33,600 could weaken the technical structure, intensify selling pressure and expose the index to further downside risks. Overall, the near-term outlook remains cautious, with the index’s ability to defend immediate support likely to determine its next directional move.
Global Macro Backdrop
United States - Political developments and economic outlook
US Equity markets fell sharply on Thursday as investors reassessed the outlook for artificial-intelligence spending, technology valuations and interest rates. The much-anticipated market debut of Anthropic failed to reverse broader weakness in AI-linked equities, while concerns about the persistence of Inflation weighed on risk appetite.
All three major US benchmarks finished lower. The Dow Jones Industrial Average declined 2.19% to 49,097.06, the S&P 500 lost 2.02% to 7,175.83 and the Nasdaq Composite fell 2.25% to 23,879.20. Declines extended across the market, illustrating broad investor caution rather than weakness confined to one technology subgroup.
The Federal Reserve policy outlook remained a central concern, with financial markets pricing a December interest-rate increase amid persistent inflation. The firm US dollar and elevated Treasury yields reinforced pressure on precious metals and richly valued growth shares.
Canadian equities were affected by both the US technology selloff and lower precious-metal prices. The TSX materials and technology groups were the weakest major sectors, while corporate transaction reports created selective gains in telecommunications shares.
China - Industrial activity and Commodity demand
China’s manufacturing, infrastructure and construction activity continued to influence expectations for copper and other industrial metals. Investors balanced potential Supply constraints against the prospect of slower Demand and tighter financing conditions.
Industrial metals remained vulnerable to US dollar strength and concerns over global activity. Weakness across the commodity complex reduced investor appetite for Canadian-listed miners, while gold-related selling was the more immediate driver of losses in the materials sector.
Global bond yields and risk appetite
Global risk appetite deteriorated as North American benchmarks fell and commodity-linked Canadian shares extended their losses. The TSX’s sixth consecutive decline coincided with lower precious-metal prices and continued scepticism about the durability of the AI Investment cycle.
Higher-for-longer interest-rate expectations continued to influence discount rates, currency markets and equity valuations. The combination of persistent inflation and weakening investor sentiment increased volatility, even though some defensive and transaction-driven individual stocks outperformed.
Canadian Market Focus
The S&P/TSX Composite Index fell 549.32 points (1.59%) to 34,028.73 on November 19, its lowest close since May 19. The benchmark has now declined for six consecutive sessions, the longest losing run since December 2024. All major TSX sectors ended in negative territory as declines in miners and technology stocks spread across the market.
The Canadian economic outlook remained influenced by October CPI inflation of 3.1% year over year and softer employment conditions. Investors continued to evaluate what the combination means for future Bank of Canada decisions, consumer demand and domestic financing conditions.
Materials shares declined 2.9%, hurt by a renewed drop in gold prices to a 14-month low. Technology lost 3.3%, including a 5.2% fall in Shopify. Heavily weighted financials and energy each closed approximately 1.0% lower, limiting the market’s ability to stabilise.
Canadian banking regulation was another development, as the federal banking regulator proposed adjustments intended to improve competition between dominant lenders and smaller banks and Credit unions. The proposals added a sector-specific policy consideration to an already cautious trading session.
Company-specific moves were pronounced. TELUS surged approximately 13.7% amid reports of preliminary discussions involving BCE, while Quebecor Class B advanced 7.5% and Headwater Exploration gained 3.8%. In contrast, Seabridge Gold fell about 29.3%, NovaGold Resources declined around 9.2% and Perpetua Resources lost 7.9%.
Commodity view - what moved the TSX
- Crude: Crude oil traded around $82 per barrel on Friday and remained on track for a third consecutive weekly decline, as signs of abundant global supply outweighed concerns over potential renewed US strikes on Iran.
- Gold: Gold prices fell toward $3,500 an ounce on Friday, reaching their lowest levels since September 2025 and heading for a sharp weekly decline of nearly 9%.
- Silver: Silver prices fell toward $42 an ounce on Friday, reaching their lowest levels since September 2025 and heading for a sharp weekly decline of more than 13%.
- Copper: Copper futures sank to around $5.50 per pound in November, their lowest level in over seven months, as risks to Data Center development clouded the demand outlook.
Forex Watch
USD/CAD: The Canadian dollar weakened to around 1.43 per USD in mid-November, its lowest level since March 2025, as softer-than-expected inflation eased bets of another rate hike by the Bank of Canada.
Canadian October CPI inflation of 3.1% and softer labour-market conditions continued to shape domestic monetary-policy expectations. Meanwhile, a more restrictive US rate outlook supported the US dollar and limited the potential benefit to the Canadian currency from relatively steady crude oil.
US dollar: The greenback remained relatively firm as investors priced persistent inflation and further Federal Reserve tightening. A firmer dollar created additional pressure on gold and other US-dollar-denominated commodities.
Canadian dollar implications: A weaker loonie can raise the translated value of foreign-currency Revenue for exporters while increasing the Canadian-dollar cost of imported equipment and materials. Currency hedging and Debt exposure continue to matter for Canadian-listed businesses.
Key Market Drivers
- TSX closing performance: The Composite declined 549.32 points (1.59%) to 34,028.73, its lowest close since May 19 and sixth consecutive daily loss.
- Materials and technology: Materials dropped 2.9% and technology lost 3.3%, led by weakness in metal miners and Shopify.
- US market selloff: The Dow fell 2.19%, the S&P 500 lost 2.02% and the Nasdaq slipped 2.25% as AI-related optimism weakened.
- Monetary policy: Expectations for a December Federal Reserve rate increase and a firm dollar pressured Growth Stocks and precious metals.
- Crude oil: US WTI futures settled 0.1% lower at US$83.21 per barrel amid conflicting supply signals.
- Gold and silver: December gold futures settled at US$3,685.50 per ounce; silver remained under pressure alongside bullion.
- Industrial metals: Uncertain Chinese demand and dollar strength pressured investor sentiment toward diversified miners.
- USD/CAD: The loonie traded near 70 US cents amid diverging North American interest-rate expectations.
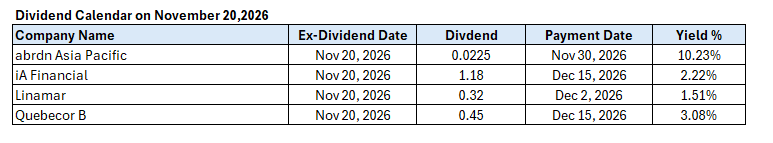
- Corporate stock movers: TELUS, Quebecor and Headwater Exploration advanced; Seabridge Gold, NovaGold and Perpetua Resources declined.
- Market breadth: Declining TSX issues outnumbered advancers 852 to 144, with 59 unchanged; the TSX 60 VIX rose to 19.51.
Market Outlook
The November 19 session extended the TSX Composite’s losing streak to six days. The benchmark dropped 1.59% to 34,028.73, its lowest level in six months. Broad declines in materials, technology, financials and energy indicated an entrenched risk-off tone across Canadian equities.
Wall Street recorded steep losses, with all three major US benchmarks falling more than 2%. Anthropic’s heavily watched market debut failed to revive enthusiasm for artificial intelligence, reinforcing concern over valuations and the sustainability of technology-related spending.
Canada’s October CPI reading of 3.1% remained an important domestic macroeconomic signal. Bank of Canada policy expectations and proposed banking-sector regulatory changes also mattered, but the immediate market direction was dominated by weaker precious metals, US equities and investor risk appetite.
Commodity markets were unsettled. December gold futures fell to US$3,685.50 per ounce, while US WTI crude was broadly flat at US$83.21 per barrel. Softer metals sentiment weighed on Mining stocks, even as uncertainty around the Strait of Hormuz continued to influence oil prices.
In the near term, investors should monitor the 34,000 area as immediate technical support and 34,500 as initial resistance. Precious-metal prices, global technology sentiment, US Treasury yields and corporate developments in telecommunications may shape the next directional move.
Overall view: The near-term TSX outlook remains cautious after six successive declines and deeply negative market breadth. A sustained rebound above 34,400 could improve confidence, but further weakness below 33,600 would expose the index to additional downside risk.

 Nov 20, 2026
 Please wait processing your request...