
 NZ
 UK
 US
 AU
 IND

 CA

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity

While most investors were winding down for the year-end holidays, Colonial Coal International Corp. (TSXV: CAD) staged a massive breakout on December 29, 2025, surging 18.33% to close near its 52-week high. For a pure-play metallurgical coal developer, this isn't just a "Santa Claus rally"—it’s a signal that the market is repricing the value of high-grade steel-making coal.
Key Drivers: What Fuelled the Dec 29 Surge?
The sudden spike in CAD's share price can be attributed to a "perfect storm" of macro and micro factors:
Source: Kalkine Group
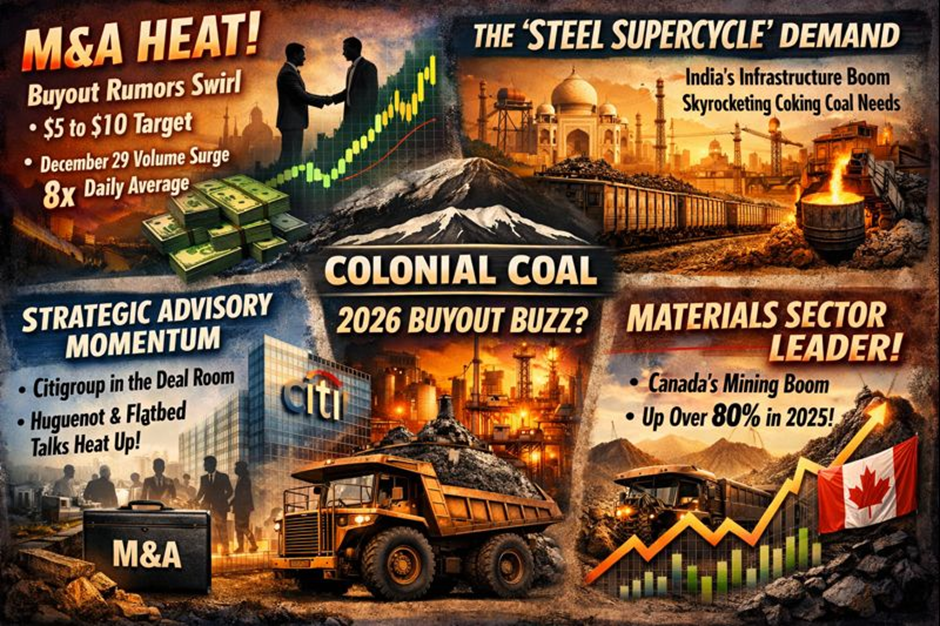
- M&A Heat: Rumors of a potential buyout have long circled Colonial Coal, with price tags of $5.00 to $10.00 per share previously floated by analysts. On December 29, unusual volume (nearly 8x the daily average) suggests institutional positioning ahead of a possible 2026 acquisition announcement.
- The "Steel Supercycle" Demand: Metallurgical (coking) coal is essential for steel. With India's infrastructure projects hitting a fever pitch in late 2025, the demand for high-quality Canadian coking coal has skyrocketed.
- Strategic Advisory Momentum: Citigroup has been acting as the financial advisor for the company’s potential sale. Market chatter indicates that negotiations for the Huguenot and Flatbed projects may have entered a critical stage.
- Materials Sector Leadership: In 2025, the Canadian materials sector outperformed the US market significantly (up over 80%). Colonial Coal is a primary beneficiary of this capital rotation into hard assets.
Business Model: The "Exit Strategy" Specialist
Unlike traditional miners that focus on decades of production, Colonial Coal’s business model is "Develop to Sell."
- Acquisition & Resource Definition: They identify high-potential metallurgical coal deposits in the Peace River Coalfield of B.C.
- Permitting & PEA: They advance projects through Preliminary Economic Assessments (PEA) and environmental baselines to "de-risk" them for majors.
- Monetization: The ultimate goal is a total corporate sale or a joint venture where a "Major" (like BHP or Glencore) pays a massive premium for the proven reserves.
Latest Updates: Financial & Operational (Q4 2025)
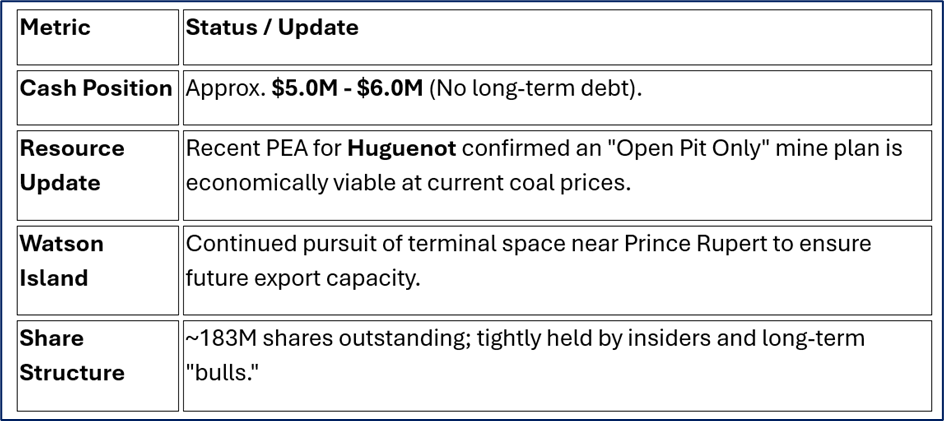
Source: Company Data
SWOT Analysis: A Strategic Deep Dive
Source: Kalkine Group
Strengths
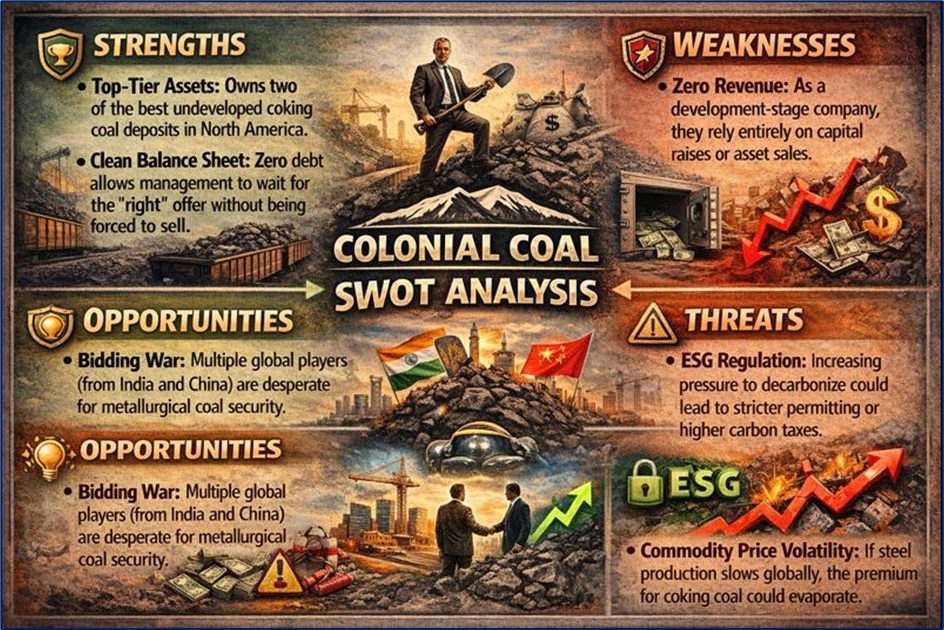
- Top-Tier Assets: Owns two of the best undeveloped coking coal deposits in North America.
- Clean Balance Sheet: Zero debt allows management to wait for the "right" offer without being forced to sell.
- Board Expertise: Led by David Austin, a veteran with a track record of selling coal assets for hundreds of millions.
Weaknesses
- Zero Revenue: As a development-stage company, they rely entirely on capital raises or asset sales.
- Project Concentration: Value is tied to only two main projects; a failure in one would be catastrophic.
Opportunities
- Bidding War: Multiple global players (from India and China) are desperate for metallurgical coal security.
- Infrastructure Growth: The 22% CAGR in "Smart City" projects globally ensures a decade-long floor for steel demand.
Threats
- ESG Regulation: Increasing pressure to decarbonize could lead to stricter permitting or higher carbon taxes.
- Commodity Price Volatility: If steel production slows globally, the premium for coking coal could evaporate.
Risks to Watch
Investors should remain cautious. The stock is highly volatile and sensitive to "takeover" news. If a deal fails to materialize in early 2026, the stock could see a sharp "tax-loss harvesting" or profit-taking correction. Additionally, environmental litigation in British Columbia remains a perennial hurdle for all resource developers.
Conclusion
The 18.33% gain on December 29, 2025, underscores Colonial Coal’s status as a high-conviction "lottery ticket" for a massive M&A event. While the fundamentals of the metallurgical coal market are the strongest they've been in years, the investment remains a speculative play on a corporate exit.

 Nov 04, 2026
 Please wait processing your request...